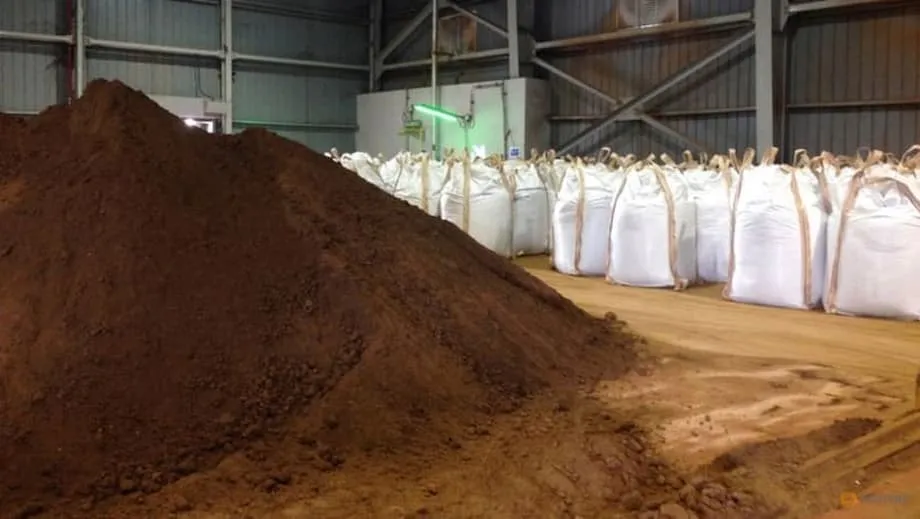
A RM747.2 Billion Resource and a Bigger Industrial Goal
Malaysia's New Industrial Master Plan 2030 values the country's rare earth resources at RM747.2 billion, about US$175 billion, and sets out the potential to attract RM100 billion, or US$23 billion, in investment and create 4,000 jobs. The ambition is to build an industry that reaches from mining to manufacturing magnets, keeping more of the economic benefits inside Malaysia.
Contents
- A RM747.2 Billion Resource and a Bigger Industrial Goal
- Why These Minerals Matter
- Keeping More Production Inside Malaysia
- Partnerships Connect Local Deposits to Factories
- The Technology Gap Behind the Ambition
- The Dates That Shaped the Strategy
- Who Controls Mining Decisions?
- Forests, Water and Waste at the Center of Development
- Balancing China and the United States
- Investment Potential Meets a Volatile Market
- Malaysia's Place in a Wider Supply Network
- The Bottom Line
As of August 21, 2025, Malaysia already has an important foothold: the Lynas Advanced Materials Plant in Gebeng, Pahang. Owned by Australia's Lynas Rare Earths, it is the largest heavy rare earth processing facility outside China and processes around 1,500 tonnes of heavy rare earths annually. It separates minerals including dysprosium and terbium, which are needed for powerful magnets used in electric vehicles and renewable energy systems.
Lynas has invested more than US$700 million in Malaysia since the plant opened in 2012 and contributed more than US$1 billion to the local economy. Malaysia now wants to connect that processing expertise with its own deposits and attract factories that turn refined minerals into more valuable products.
Estimates of the country's rare earth deposits also exceed US$200 billion, alongside the US$175 billion valuation in the industrial master plan. These figures describe the estimated value of resources in the ground. Malaysia's industrial challenge is to develop the technology, investment and operating conditions needed to turn those resources into products that buyers can use.
That challenge reaches beyond economics. Many deposits lie in forest reserves, mining powers are divided between federal and state authorities, and much of the technology Malaysia needs is concentrated in China. The country is pursuing partnerships while trying to maintain equal treatment of China, the United States and other buyers.
Why These Minerals Matter
Rare earth elements are a group of 17 metallic elements: the 15 lanthanides, scandium and yttrium. Despite their name, most are relatively abundant in the Earth's crust. The difficulty is finding concentrations that can be mined economically, then extracting and separating the individual elements.
Separation matters because a mixture of minerals is not the same as a material ready for a factory. Manufacturers need particular elements for particular jobs. Dysprosium and terbium, for example, are important ingredients in magnets that must deliver strong performance in electric vehicles and renewable energy equipment.
Rare earths support a wide range of technologies:
- Permanent magnets in electric motors and wind turbines.
- Smartphones, computers and other advanced electronics.
- Medical imaging devices and lasers.
- Defense equipment, including radar and missile guidance systems.
China produces about 60 percent of global rare earth raw materials, processes 85 percent of output and manufactures nearly 90 percent of the world's rare earth magnets. Its share grows as the materials move from extraction toward finished industrial products. The gap between its share of raw material production and processing is 25 percentage points.
China built this position through decades of strategic investment, state subsidies and a willingness to absorb environmental costs that discouraged competitors. For Malaysia, the figures explain why simply opening mines would capture only part of the opportunity. Refining, separation and manufacturing are central to its plan.
Keeping More Production Inside Malaysia
Prime Minister Anwar Ibrahim has outlined a plan covering five years to accelerate rare earth development, with attention to mining technology, refining and separation. The goal is to move Malaysia from supplying raw materials toward producing magnets and advanced materials.
Malaysia imposed a moratorium on exports of unprocessed rare earth elements in 2024. Under the policy, processed rare earths and products with added value can be exported, while exceptions for pilot projects operate under strict guidelines. The intended result is to encourage companies to invest in processing and manufacturing inside the country.
Investment, Trade and Industry Minister Tengku Zafrul Abdul Aziz described the government's approach in an interview. He said Malaysia wanted investment in the stages that follow extraction, often called downstream activities:
Malaysia is positioning itself as a processing hub rather than a raw material supplier. We are inviting all companies to invest in downstream activities of rare earths in the country, allowing the export of value-added products. This approach is intended to maximize economic benefits and strengthen the case for keeping processing domestic.
Malaysia's proposed integrated industry would connect three stages. Upstream activity covers mining. Midstream activity includes processing and separating minerals. Downstream activity turns those materials into magnets, components and other manufactured goods. Connecting these stages is the practical meaning of the country's mine to magnet vision.
Projections suggest that production of super magnets alone could generate up to US$3 billion in revenue by 2030. Malaysia's current contribution is put at about 13 percent of global critical mineral demand, with that share expected to rise as new projects begin operating.
Partnerships Connect Local Deposits to Factories
Malaysia is seeking investment from Australia, Japan, South Korea and China. Each partnership could help address a different part of the chain, from supplying minerals to providing processing expertise or building factories.
Lynas has signed a memorandum of understanding with Kelantan's state investment arm concerning local supply. Such an arrangement would connect the company's established processing presence with Malaysia's ambition to develop domestic resources.
A partnership with South Korea's JS Link aims to produce up to 3,000 tonnes of super magnets annually in Kuantan. Magnet manufacturing would take Malaysia further along the production chain, beyond separating rare earths and exporting the resulting materials.
The projects serve different purposes. Lynas's existing figure of around 1,500 tonnes annually concerns heavy rare earth processing, while the JS Link partnership's figure of up to 3,000 tonnes concerns planned magnet production. Malaysia needs both processing capability and manufacturing investment to build the complete industry it seeks.
Foreign partnerships also carry a longer objective: bringing technical knowledge into Malaysia. Investment that supports local processing, employment and technology transfer can help the country build its own industrial skills alongside new facilities.
The Technology Gap Behind the Ambition
Malaysia lacks advanced domestic technology for rare earth separation and refining, particularly for heavy rare earths. Lynas has brought expertise and investment, but much of the technology used in the most valuable processing stages remains concentrated in China.
China banned exports of rare earth processing technology in December 2023. That restriction makes access to technical knowledge a central issue for Malaysia. A country can have deposits and investors yet still need the methods and expertise required to separate commercially useful materials.
In April 2025, Beijing proposed sharing rare earth separation technology with Malaysia. Kuala Lumpur welcomed the proposal as an opportunity to develop its industrial capacity. Malaysia's strategy combines that opening with efforts to secure investment and knowledge from other partners.
Japan offers a model through the Japan Organization for Metals and Energy Security, known as JOGMEC. After China halted rare earth exports to Japan during a territorial dispute in 2010, Japan invested heavily in overseas mines and processing facilities, including Lynas in Malaysia.
Those investments and technology partnerships helped reduce Japan's dependence on Chinese rare earths from 90 percent to 58 percent within a decade, a decline of 32 percentage points. Malaysia hopes to attract similar investment with a lasting strategic purpose, rather than relying only on the sale of its mineral deposits.
The Dates That Shaped the Strategy
Malaysia's current ambitions sit within a sequence of industrial investments and Chinese export restrictions. The main dates show how processing capacity, access to technology and trade policy have become closely connected.
- 2010: China halted rare earth exports to Japan during a territorial dispute, prompting Japan to invest in alternative supplies overseas.
- 2012: The Lynas Advanced Materials Plant began operating in Gebeng, Pahang.
- 2021-2030: Malaysia's National Mineral Industry Transformation Plan sets a framework for developing the mineral industry and embedding sustainability standards.
- December 2023: China banned exports of rare earth processing technology.
- 2024: Malaysia imposed a moratorium on exports of unprocessed rare earth elements.
- April 2025: Beijing proposed sharing rare earth separation technology with Malaysia, while China also restricted exports of certain rare earths and associated magnets.
- 2030: Malaysia's industrial plans point toward investment, employment and magnet production goals.
The export restrictions have affected different parts of the industry. Controls on processing technology concern access to the knowledge needed to build capacity. Restrictions on minerals and magnets affect access to materials and products that existing factories need.
Who Controls Mining Decisions?
Malaysia's Federal Constitution places land and mining rights under state governments. States can issue mining permits and remove forest reserve status from land for mining without federal approval. National industrial ambitions therefore depend on decisions made across several levels of government.
The Ministry of Natural Resources and Environmental Sustainability has ruled out creating a centralized regulator for the rare earth industry, citing constitutional provisions and state objections. Acting Minister Johari Abdul Ghani has stressed the need for close consultation with states to protect their rights.
This division of powers complicates the implementation of national policy and creates gaps that can allow illegal mining. Aligning regulations requires agreement with state governments, making the process slow and delicate.
Malaysia has proposed strict guidelines and standard operating procedures for rare earth development, but implementation remains inconsistent across states. Investors need workable rules, while communities need confidence that environmental requirements will be applied wherever projects operate.
Earlier ventures show why public confidence matters. MAREC and ARE were shut down following public protests over radioactive waste and environmental concerns. Those experiences remain part of the country's rare earth history as Malaysia considers a larger industry.
Forests, Water and Waste at the Center of Development
Most of Malaysia's rare earth deposits are in Terengganu, Kelantan and Pahang, regions with high biodiversity and substantial carbon stocks. Up to 80 percent of deposits are estimated to lie in forest reserves. Developing them could place mineral extraction in direct competition with the protection of forests and the wildlife they support.
Rare earth mining and processing carry risks including radioactive waste, deforestation and water pollution. The Lynas plant has continued to face public scrutiny over waste management despite compliance with safety standards.
Malaysia is exploring extraction methods such as in-situ leaching to reduce land clearing. This method extracts minerals from their location in the ground rather than relying on extensive excavation. It brings its own risk of water contamination, so reducing disturbance above ground still leaves water protection as a central concern.
Former Environment Minister Nik Nazmi Nik Ahmad warned that the pursuit of immediate economic returns needed lasting safeguards:
Proper policies and environmental safeguards are needed. We must avoid short-term gains that come at the expense of long-term sustainability.
The National Mineral Industry Transformation Plan 2021-2030 aims to embed sustainability and ESG standards throughout the production chain. ESG means environmental, social and governance standards: how a project affects nature and people, and how responsibly it is managed. Progress has been uneven.
For communities near deposits and processing facilities, the industrial strategy has concrete consequences. Decisions about mining permits, forest status and waste management will determine how development affects land and water, alongside the employment and investment it may bring.
Balancing China and the United States
Malaysia is developing its rare earth industry during intensifying rivalry between China and the United States. Both countries want secure supplies of critical minerals for industrial and defense uses, and both regard Malaysia as a strategic partner.
China has used its dominant position to offer technology transfers and investment to friendly countries while imposing export restrictions on rivals. Its April 2025 restrictions on certain rare earths and associated magnets disrupted supply chains in Japan, Europe and the United States, even as Beijing proposed sharing separation technology with Malaysia.
The United States is investing in domestic rare earth production and processing. MP Materials and Noveon Magnetics are building new facilities, and Washington has launched the Minerals Security Partnership with partners including Australia, Japan and India. Progress faces high costs, environmental regulations and a shortage of technical expertise.
Tengku Zafrul said Malaysia would apply consistent rules to buyers rather than favor either major power:
Malaysia cannot have two different standards when dealing with the US and China. If we allow export to China, we must also allow export to other parts of the world. Consistency and neutrality are important.
Malaysia's policy combines openness to international investors and buyers with an effort to keep more valuable production at home. Equal export rules are part of maintaining credibility with partners on both sides of the rivalry.
Investment Potential Meets a Volatile Market
Malaysia's projected RM100 billion in investment and 4,000 jobs depend on building an industry that can operate commercially. Moving from mining into magnets would allow the country to retain more of the earnings and technical knowledge generated along the production chain.
Rare earth prices are volatile and can be affected by geopolitical shocks and Chinese state intervention. China's subsidies and willingness to absorb industry losses make price competition difficult for new entrants. Building a processing facility or factory therefore involves exposure to changing markets as well as the cost of acquiring technology.
Malaysia is inviting strategic investment with incentives for companies that commit to local processing, job creation and technology transfer. Japan's experience shows how sustained overseas investment and partnerships can reduce dependence on a dominant supplier.
Environmental and social concerns also affect whether projects proceed. Public opposition could derail developments if waste, water and forest impacts are not managed transparently and sustainably. Regulatory coordination, market conditions and community acceptance all bear on the economic goals.
The 2030 plans provide a target year for industrial development and projected magnet revenue. No start date is given for the JS Link magnet project, and no implementation date is specified for China's proposed technology sharing with Malaysia.
Malaysia's Place in a Wider Supply Network
The United States, Australia, Canada and Saudi Arabia are also investing in new mining and processing hubs. International collaboration is necessary because no single country can outpace China's rare earth industry alone.
Malaysia enters that effort with several advantages: an existing processing facility operated by Lynas, significant untapped deposits, a strategic location, established infrastructure and government support for industries that add value to minerals.
Its weaknesses are equally concrete. The country depends on foreign partners for important technology, operates under divided regulatory powers, faces environmental and social risks, and is exposed to volatile global prices.
Malaysia's ability to build a complete production chain depends on securing technology sharing arrangements with trusted partners, aligning federal and state rules, and applying sustainability standards throughout mining, processing and manufacturing. Managing the competing interests of China, the United States and other partners is part of that work.
The opportunity is substantial, but its benefits will come through operating facilities, skilled employment and manufactured products. Malaysia's deposits provide a starting point. Its policies and partnerships must connect those deposits to an industry that communities can accept and customers can rely on.
The Bottom Line
- Malaysia's New Industrial Master Plan 2030 values rare earth resources at RM747.2 billion and identifies potential for RM100 billion in investment and 4,000 jobs.
- Lynas's Gebeng plant processes around 1,500 tonnes of heavy rare earths annually and provides Malaysia with established processing capacity.
- The 2024 moratorium on unprocessed rare earth exports aims to keep more processing and manufacturing inside Malaysia.
- A JS Link partnership targets up to 3,000 tonnes of super magnets annually in Kuantan, while projected magnet revenue could reach US$3 billion by 2030.
- Technology gaps, divided regulatory powers, forest protection, waste management and volatile prices complicate development.
- Malaysia is pursuing partnerships with China and other countries while committing to consistent export rules for global buyers.