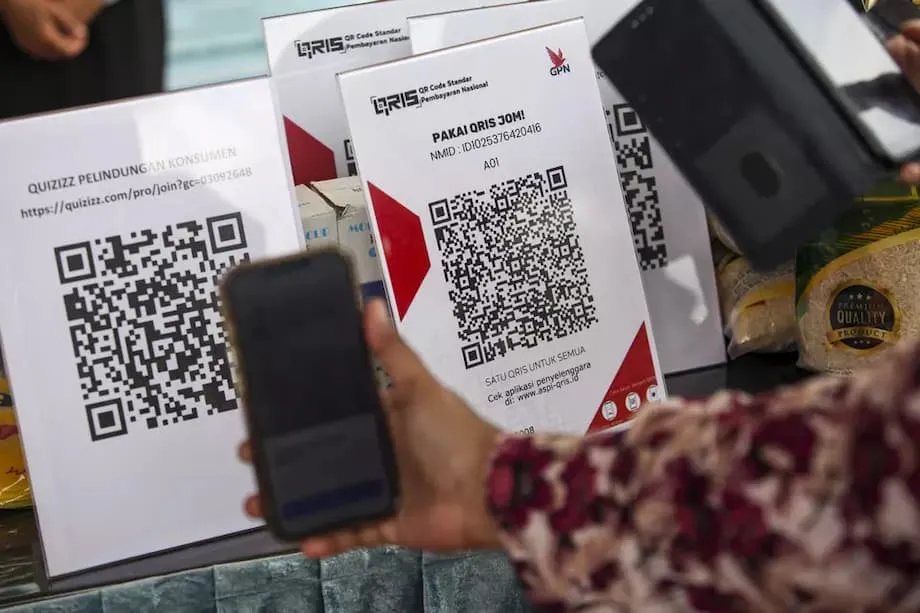
Indonesian payment apps reach Japanese shops
Indonesians can now use their domestic mobile banking apps and digital wallets to pay at an initial 35 merchants in Japan through QRIS, Indonesia's national QR payment standard. The service launched on August 17, 2025, coinciding with Indonesia's 80th Independence Day and extending a payment network already operating in Malaysia, Thailand and Singapore.
Contents
- Indonesian payment apps reach Japanese shops
- How QRIS brings different apps together
- What the launch changes for travelers and merchants
- The work behind the Indonesia and Japan connection
- Why Bank Indonesia is taking QRIS abroad
- What Southeast Asia's payment figures show
- Japan's place in the regional payment network
- Security, rules and acceptance remain central
- China, India, South Korea and Saudi Arabia are next targets
- Key Points
The launch connects Indonesia's Quick Response Indonesian Standard, known as QRIS, with Japan's JPQR Global network. Customers use a participating Indonesian payment app to scan a Japanese merchant's JPQR Global code, bringing a familiar way of paying into an overseas shopping trip.
Bank Indonesia, the Indonesian Payment System Association (ASPI), Japan's Ministry of Economy, Trade, and Industry (METI), the Payment Japan Association (PJA) and JPQR Global operator Netstars worked together on the connection. More Japanese merchants are expected to join the network, expanding acceptance beyond the first 35 locations.
The arrangement also prepares for payments in the opposite direction: Japanese tourists using their domestic payment apps to scan QRIS codes at Indonesian businesses. As of August 19, 2025, that reciprocal service remained in preparation, and no starting date was given.
For travelers and businesspeople, the immediate change is practical. At participating Japanese merchants, they can pay through an app they already use in Indonesia instead of navigating an unfamiliar payment service. For the two countries, the connection is part of a wider effort to support tourism, trade and economic cooperation through simpler payments.
Japan's addition also extends the reach of a system that has attracted more than 57 million users in six years. Its growth at home, particularly among small businesses, provides the foundation for Indonesia's effort to connect QRIS with payment networks abroad.
How QRIS brings different apps together
Bank Indonesia launched QRIS in 2019 to simplify a fragmented domestic payment market. Before a common standard, different payment services could require different arrangements. QRIS allows merchants and customers to transact through a single standardized QR code across a range of mobile banking apps and digital wallets.
A QR code is a pattern that a phone can scan to read payment information. The important feature of QRIS is interoperability, meaning that different payment services can work together through a common standard. A merchant can use one standardized code instead of depending on a separate code for every supported service.
That simplicity has made QRIS especially popular among micro, small and medium enterprises, often called MSMEs. These businesses can accept digital payments from customers using different platforms, while shoppers can continue using their preferred payment app.
The Japanese connection applies the same principle across a national border. Indonesian users scan a JPQR Global code with their domestic app, and the connected payment systems handle the transaction between the two countries.
Indonesia's ambition is to make that experience straightforward even though the work behind it is complex. A common scanning experience requires the participating institutions to coordinate how payment information moves, how transactions are processed and which rules apply.
What the launch changes for travelers and merchants
Indonesian tourists, students and business travelers stand to benefit from using familiar payment apps abroad. QRIS aims to reduce the inconvenience and costs associated with exchanging currency and using foreign payment systems, while reducing the need to carry large amounts of cash.
The initial network of 35 Japanese merchants gives travelers a starting point for those payments. Its usefulness will grow as more businesses accept the service. Wider merchant participation is therefore central to turning the launch into a payment option that customers can use regularly during a visit.
Japanese merchants gain another way to serve Indonesian tourists, whose numbers have been steadily increasing. Accepting payments through a system widely used in Indonesia can make purchases easier for those visitors and help participating businesses attract their spending.
Indonesian businesses, especially MSMEs, would gain a similar opportunity through the planned reciprocal service. Japanese visitors using their own payment apps could pay at Indonesian merchants displaying QRIS codes, giving local businesses access to more customers seeking cashless transactions.
The benefits extend beyond an individual purchase. Easier payments can support tourism and business travel by removing a recurring inconvenience: finding an accepted way to pay in another country. The expansion also opens opportunities for Indonesian businesses to reach new customer groups as international acceptance develops.
The work behind the Indonesia and Japan connection
Bank Indonesia and its partners had to bring together technical standards, regulatory requirements and operating procedures before launching payments in Japan. Connecting two QR networks involves more than making their codes readable by the same phone.
The institutions must agree on how payments are processed and how the participating systems communicate. They also need arrangements that meet each country's rules on payments, data protection and consumer rights.
The QRIS and JPQR collaboration is guided by Bank Indonesia's Payment System 2025 Visions and aligns with the G20 Roadmap for Enhancing Cross-Border Payments. Both place the Japanese launch within a broader effort to improve how money moves between countries.
Preparations included extensive technical trials and sandbox testing with Japanese payment authorities. A sandbox is a controlled testing environment where participants can check how a service works before wider use. The trials were intended to support security, efficiency and interoperability.
Bank Indonesia and its partners have also pursued regulatory dialogue and international standards such as ISO20022. Such standards provide a shared structure for payment information, helping different systems communicate. Their adoption is progressing across ASEAN, although it is not yet universal.
Why Bank Indonesia is taking QRIS abroad
Bank Indonesia Governor Perry Warjiyo described the Japanese expansion as a "significant milestone in cross-border payment system innovation." His comments connect the international rollout with the role QRIS has already played in Indonesia's digital economy.
Warjiyo also described how the system had changed domestic payments and supported Indonesia's control over its economic development:
"QRIS has become a game changer for the digital payment ecosystem and strengthened Indonesia's economic sovereignty," Warjiyo said.
Bank Indonesia's strategy is to internationalize Indonesia's digital payment infrastructure. Connecting QRIS with other countries allows Indonesian consumers to keep using familiar services while traveling and creates the basis for foreign visitors to pay more easily in Indonesia.
The policy also links domestic business participation with international economic cooperation. QRIS already serves small enterprises at home; connections abroad can extend the value of that network by making it accessible to more travelers and customers.
Bank Indonesia's continuing development of QRIS features, alongside its work on regulatory compliance and consumer protection, supports Indonesia's ambition to lead in regional digital payments and help shape international payment standards.
What Southeast Asia's payment figures show
Japan follows QRIS connections with Thailand, Malaysia and Singapore. By June 2025, those three links had handled millions of transactions, providing a record of how the system was being used across borders before the Japanese launch.
The figures also show that the connections have developed at different scales and over different periods:
- Thailand: 994,890 transactions worth Rp 437.54 billion, about $27 million, since August 2022.
- Malaysia: 4.31 million transactions worth Rp 1.15 trillion, about $71 million, since May 2023.
- Singapore: 238,216 transactions worth Rp 77.06 billion, about $4.8 million, since November 2023.
Malaysia's 4.31 million transactions were more than four times Thailand's 994,890, even though the Malaysian connection began later. Its transaction value of Rp 1.15 trillion was also more than twice Thailand's Rp 437.54 billion. The figures describe activity accumulated since each connection began, rather than identical periods of operation.
Across all three countries, the recorded activity reflects growing demand for payments across borders as travel, trade and electronic commerce expand. Indonesia's approach is being considered as a model for other countries seeking to connect their payment systems and strengthen regional economic integration.
The sequence of developments shows how the network has widened:
- 2019: Bank Indonesia launched QRIS as a unified domestic QR payment standard.
- August 2022: The Thailand connection began.
- May 2023: The Malaysia connection began.
- November 2023: The Singapore connection began.
- June 2025: The three regional connections had recorded the transaction totals listed above.
- August 17, 2025: QRIS payments launched in Japan, initially at 35 merchants, on Indonesia's 80th Independence Day.
Japan's place in the regional payment network
Japan is ASEAN's fourth largest trading partner, making payment connections with Southeast Asia relevant to an already substantial economic relationship. Linking QRIS and JPQR is expected to deepen those ties by making transactions easier for visitors and businesses.
Japan's adoption of digital payments has lagged behind South Korea and China, although use is growing rapidly. Providers such as PayPay and Rakuten Pay are part of that growth. Interoperability problems and high merchant fees remain challenges in Japan's payment market.
Tourism and electronic commerce are expected to benefit particularly from more connected payment systems. As travel between ASEAN countries and Japan increases, services that work across borders can help customers transact without having to learn an unfamiliar payment platform.
Small businesses may benefit from reduced transaction costs and greater access to international customers. The practical value depends on participation: travelers need merchants that accept the service, and merchants need a payment option their visitors can use.
The ASEAN Digital Economic Framework Agreement (DEFA) provides a broader regional context. It aims to align policies and standards for digital trade, electronic commerce, payments, digital identity, cybersecurity and data flows. QRIS connections with Malaysia, Thailand, Singapore and Japan offer an example of payment systems being brought together across national boundaries.
Security, rules and acceptance remain central
Bank Indonesia and its partners face several continuing tasks as the network expands. Technical interoperability requires coordination and investment because countries use different standards for QR codes and payment processing.
Regulatory alignment is another requirement. Each country has its own rules governing payments, personal data and consumer rights. Participating institutions need compatible arrangements so that customers can make payments securely and receive appropriate protection.
Merchant adoption is equally practical. A payment network needs enough participating businesses to make it useful. Expanding acceptance can require outreach, education and, in some cases, incentives for merchants to upgrade their payment infrastructure.
Consumer trust depends on addressing fraud, scams and data privacy. Security measures and consumer protection policies are therefore part of the work needed to support wider use, alongside the technical connection itself.
An analysis published by Fulcrum.sg described the cooperation required between ASEAN and Japan, including agreement on commercial arrangements, governance and technical standards:
Collaboration between ASEAN and Japan is essential to agree on commercial, governance, and technical aspects. Adoption of international standards like ISO20022 is progressing, though not yet universal in ASEAN. Trust is crucial for adoption, as concerns about scams and fraud persist. Strengthened oversight, consumer protection, digital literacy, and cybersecurity are vital.
Digital literacy, meaning people's ability to understand and safely use digital services, sits alongside oversight and cybersecurity in that assessment. Connecting the networks is one task; helping customers use them confidently and protecting their transactions are continuing responsibilities.
China, India, South Korea and Saudi Arabia are next targets
Bank Indonesia is pursuing further QRIS collaborations with China, India, South Korea and Saudi Arabia. The Japanese launch is therefore one stage of a wider international expansion, rather than the endpoint of the program.
Work with China includes cooperation with the People's Bank of China and UnionPay International. Trials with UnionPay International are already underway, with system development and sandbox testing involving four Indonesian switching service providers.
Switching service providers help route payment information between participating services. Their involvement in the Chinese trials is part of the technical work required to connect payment systems before broader operation.
Agreements have also been signed with India and South Korea, with technical trials set to begin soon. Saudi Arabia is another country with which Bank Indonesia is pursuing collaboration as it seeks to extend QRIS acceptance.
Indonesia's broader objective is to strengthen its role in digital financial innovation, contribute to international standards and support economic cooperation across Asia and beyond. The effort reflects a wider shift toward digital payments as countries seek to expand financial inclusion, reduce transaction costs and encourage innovation.
For customers and businesses, the measure of that effort is concrete: more places where a familiar app can complete a purchase, and more visitors who can pay at a local merchant. Japan's initial 35 participating merchants mark the latest expansion, while the existing Southeast Asian transaction figures show the scale that connected networks have already reached.
Key Points
- QRIS payments launched in Japan on August 17, 2025, Indonesia's 80th Independence Day, starting with 35 merchants.
- Indonesian customers can scan JPQR Global codes using participating domestic mobile banking apps and digital wallets.
- Japanese visitors using their own payment apps at Indonesian QRIS merchants is a planned reciprocal service.
- QRIS launched in 2019 and has attracted more than 57 million users in six years.
- By June 2025, the Malaysia connection had handled 4.31 million transactions, Thailand 994,890 and Singapore 238,216.
- Bank Indonesia is pursuing further connections with China, India, South Korea and Saudi Arabia.
- Expansion requires compatible technology and regulations, wider merchant acceptance, cybersecurity and consumer protection.