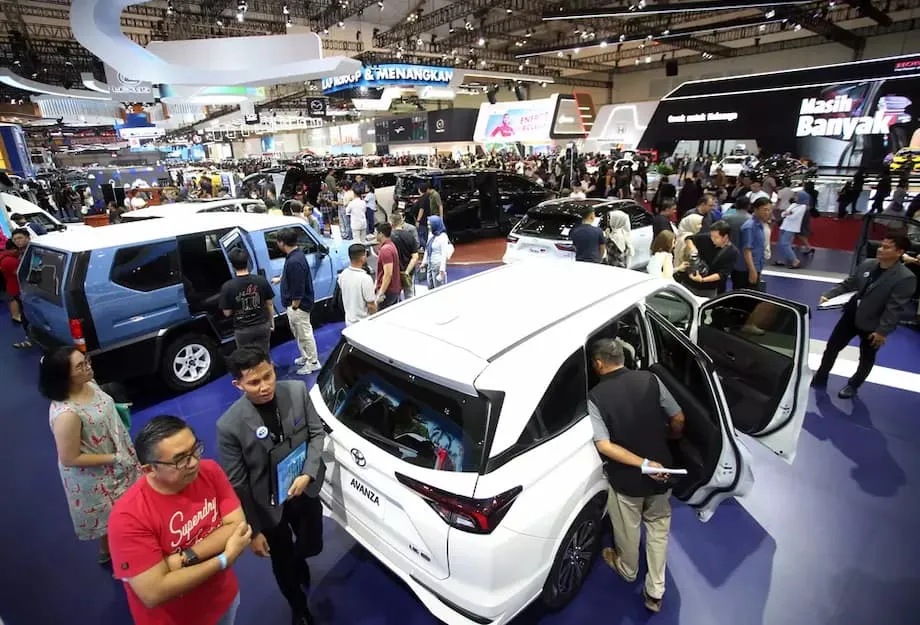
A Gap of 48,976 Vehicles Puts Indonesia Under Pressure
Indonesia sold 865,723 new vehicles in 2024, while Malaysia reached a record 816,747, leaving just 48,976 vehicles between Southeast Asia's largest automotive market and its fast advancing rival. Figures from the Indonesian Automotive Industry Association, known as Gaikindo, show how close the contest has become.
Contents
- A Gap of 48,976 Vehicles Puts Indonesia Under Pressure
- Why Malaysia's National Brands Keep Winning Buyers
- Indonesia's Buyers Face Pressure on Income and Credit
- Chinese Manufacturers Gain Ground Through Electric Cars
- Malaysia's Electric Market Brings New Rivals and a Local Response
- Japanese and German Brands Defend Their Positions
- Thailand and Vietnam Show Different Regional Pressures
- Government Support Shapes Both Sales and Factories
- Forecasts Point to a Difficult 2025
- Key Points
Malaysia's annual total was about 94% of Indonesia's. For a country that has spent decades behind Indonesia, the narrowing gap marks a major change in the regional car business. Indonesia's large population and established manufacturing sector have long attracted global carmakers, but those advantages are meeting weaker demand at home.
By August 18, 2025, the pressure was visible in Indonesia's latest sales figures. Sales during the first seven months of the year fell 10% from the same period in 2024 to 435,390 vehicles. July alone recorded an 18% decline compared with July a year earlier.
Malaysia, meanwhile, has benefited from strong national brands, government incentives and resilient consumer demand. Some measures already put it ahead of Indonesia, although the full year totals for 2024 still placed Indonesia first. The article's claim of a Malaysian lead on other measures came without a specified sales category or comparison period.
The competition is also changing in character. Chinese manufacturers are gaining customers with electric vehicles, Japanese brands are defending their established positions, and governments are trying to support local factories while making new cars affordable. For buyers, the immediate issues are simpler: the price of a vehicle, access to a loan and the range of models available.
Why Malaysia's National Brands Keep Winning Buyers
Perodua and Proton are central to Malaysia's sales strength. Their affordable vehicles, designed around local preferences and fuel economy, have helped sustain demand even as competition has increased. Perodua alone sold more than 358,000 vehicles in 2024, its best annual result.
That total represents roughly 44% of Malaysia's 816,747 new vehicle sales. Perodua's scale shows why the country's market cannot be explained by the arrival of electric cars alone. A large share of purchases still depends on established local manufacturers offering vehicles that households can afford.
Government measures have also supported purchases. Temporary tax cuts and duty exemptions, particularly for electric vehicles, encouraged demand, while a backlog of orders carried over into 2024. Those delayed deliveries helped keep sales strong after the immediate disruption of the pandemic had passed.
Malaysia also has one of ASEAN's highest rates of vehicle ownership per person. A strong preference for owning cars has helped support purchases as the market has returned toward more normal conditions after the pandemic.
These forces work together. National brands provide familiar choices at accessible prices, incentives reduce some purchase costs, and existing demand gives manufacturers a substantial customer base. Malaysia's record therefore reflects both the strength of its established car business and interest in newer technology.
Indonesia's Buyers Face Pressure on Income and Credit
Indonesia's slowdown has several causes. Its middle class has shrunk since 2018, weakening the pool of households able to make a large purchase such as a car. Higher interest rates have also made vehicle loans harder to afford.
A car loan spreads the purchase price across future payments, but interest adds to the amount a buyer must repay. When rates are high, a household may have to accept larger payments, choose a cheaper vehicle or postpone buying altogether.
Banks have become more cautious about approving loans because of concerns about nonperforming loans, meaning borrowing that customers are struggling to repay. Tighter approval standards can limit sales even when someone wants a vehicle and is willing to take out financing.
Political transitions, including the presidential election, have also weighed on consumer confidence. Economic uncertainty can encourage households to delay expensive purchases until their income and financial commitments feel more secure.
Gaikindo Secretary General Kukuh Kumara has warned that Indonesia's weakening sales threaten its regional lead. He has called for the government and industry to respond to Malaysia's progress:
The gap with Malaysia is narrowing and without strategic action, it is not impossible that Indonesia could be overtaken.
Gaikindo wants the government to restore support similar to measures used during the pandemic, including tax cuts and credit assistance. The aim is to help buyers return to the market while giving manufacturers support through the downturn.
Chinese Manufacturers Gain Ground Through Electric Cars
BYD, Chery, Wuling and Neta are among the Chinese manufacturers reshaping competition in Southeast Asia. Their arrival has brought more electric vehicles with extensive features and competitive prices, challenging established Japanese and South Korean brands.
In Indonesia, Chinese brands increased their market share from 3.4% in 2021 to 6.4% in 2024, nearly doubling their position. BYD captured a 36% share of Indonesia's electric vehicle market within seven months of launching, while Wuling and Chery also made gains.
The two figures describe different markets. The 6.4% figure covers Chinese brands across Indonesia's automotive market, while BYD's 36% refers specifically to electric vehicles. A manufacturer can lead a rapidly developing category while still competing for a smaller part of total vehicle demand.
Chinese manufacturers have attracted customers through prices often below those of Japanese and European rivals, alongside smart software, advanced features and battery technology. Their improving quality has also strengthened their appeal against established brands.
Government support has helped their expansion. Indonesia and Malaysia have offered tax exemptions and import duty waivers for electric vehicles, reducing some of the costs associated with bringing models to market and buying them.
Chinese companies are also investing in factories and supply chains across Southeast Asia. Local production can reduce costs and build confidence in a brand's commitment to a market. For governments, those investments connect the push for electric cars with the effort to attract manufacturing.
Malaysia's Electric Market Brings New Rivals and a Local Response
Malaysia is experiencing its own increase in Chinese electric vehicles. Chery overtook Mazda to become the country's fifth largest brand by market share in 2024, showing that competition is changing beyond Indonesia.
The number of Chinese brands entering Malaysia was expected to reach 13 or 14 by the end of 2025. A larger field gives buyers more models to compare, while placing pressure on manufacturers to compete on price, equipment and technology.
Proton has responded with an electric vehicle of its own. Its first EV, the e.MAS 7, launched in December 2024 and quickly attracted thousands of bookings. More models were planned as the company expanded its response to the shift toward electric driving.
Malaysia's national manufacturers therefore face two tasks at once: protecting their strength in affordable vehicles and responding to demand for electric models. Perodua's record sales illustrate the continuing importance of the existing market, while Proton's launch shows how a local brand is entering a new one.
Several dates help explain how the competitive picture developed:
- 2018: The starting point for the reported contraction in Indonesia's middle class.
- 2021: Chinese brands held 3.4% of Indonesia's automotive market.
- 2024: Their share reached 6.4%, while Malaysia recorded 816,747 new vehicle sales and Indonesia recorded 865,723.
- December 2024: Proton launched the e.MAS 7.
- January to July 2025: Indonesia's vehicle sales fell 10% to 435,390.
- Late 2025: Malaysia's temporary electric vehicle incentives were scheduled to expire.
Japanese and German Brands Defend Their Positions
Japanese manufacturers still account for most vehicle sales in Indonesia, but their share has fallen from 95% to 89% in just a few years. Their dominance remains substantial, even as a growing range of competing brands wins customers.
Toyota, Honda and Mitsubishi are investing in hybrid technology, software development and local partnerships. A hybrid combines an engine with an electric motor, giving manufacturers another way to offer more efficient vehicles as demand changes.
Malaysia has also become more difficult for established Japanese brands. Toyota and Mazda both recorded sales declines of more than 10% in 2024, and their combined market share fell to 14%.
The shift extends across Southeast Asia, including Singapore, Thailand and Vietnam, where Chinese competitors have put pressure on Japanese and German manufacturers. Competitive prices and quality comparable to established alternatives have helped Chinese brands attract buyers.
BMW and Mercedes-Benz have also lost market share, although both remain strong in the luxury segment. The largest contest is taking place in the mass market, where price matters to a wider group of customers and Chinese brands have been gaining ground.
Manufacturers are consequently competing on more than the choice between petrol and electricity. Software, equipment, financing costs and local partnerships all affect how attractive a vehicle appears to a household deciding where to spend its money.
Thailand and Vietnam Show Different Regional Pressures
Thailand, long known as the "Detroit of the East," faces challenges because its automotive industry is closely tied to Japanese manufacturers and has been slow to move toward electric vehicles. Its government is seeking Chinese investment in local production to protect the country's role as a regional manufacturing hub.
The scale of Chinese competition reaches beyond Thailand. Chinese brands account for about 40% of new car sales across Asia and Oceania and 70% of electric vehicle sales in Southeast Asia. Those figures describe two different geographical areas and vehicle categories, showing the breadth of the competition and its particular strength in electric cars.
Vietnam has moved in a different direction from markets experiencing weaker demand. Its automotive market grew 24% in the first quarter of 2025, supported by rising sales of hybrids and electric vehicles.
Domestic manufacturer VinFast sold more than 87,000 fully electric vehicles in 2024. Government support for greener transport has helped the company develop as a local competitor.
Thailand's manufacturing concerns and Vietnam's sales growth show why a single regional trend cannot explain every national market. Established production networks, local brands and the pace of electric vehicle adoption are producing different results across Southeast Asia.
Government Support Shapes Both Sales and Factories
Malaysia's incentives have encouraged demand, but temporary tax cuts and electric vehicle duty exemptions were scheduled to expire in late 2025. Expectations of more normal demand after the incentive period have contributed to forecasts of lower total industry volume, the number of vehicles sold across the market.
Perodua was still expected to retain its strong position because of affordability and customer loyalty. That gives Malaysia a source of support even as the conditions behind its record sales begin to change.
Indonesia's industry was still waiting for the renewed incentives it had requested. The central bank had cut interest rates to encourage consumer spending, but borrowing costs and tight credit conditions continued to weigh on buyers.
Indonesia is also seeking to build a domestic electric vehicle industry around its large nickel resources for battery production. Incentives and tax breaks have helped attract foreign investment and encourage consumer interest, linking industrial policy with the transition to electric transport.
The transition remains at an early stage, with infrastructure gaps still a concern. Supporting factories and attracting investment address one part of the challenge; households also need affordable vehicles and the practical conditions to use them.
Both governments face a balancing act between supporting local manufacturers, attracting foreign companies and managing competition from new technology. Their decisions affect which vehicles buyers can afford and where future production takes place.
Forecasts Point to a Difficult 2025
Forecasts pointed to a 9% decline in Malaysia's total industry volume in 2025 as demand returned toward more normal levels and competition intensified. Indonesia faced a projected 14% fall in light vehicle sales, with weak purchasing conditions and tighter credit continuing to restrict demand.
Those forecasts concern slightly different sales measures: Malaysia's total industry volume and Indonesia's light vehicle market. Both nevertheless point toward a difficult year for manufacturers trying to maintain sales while investing in new models and technology.
An earlier projection had put ASEAN automotive market growth at 6% for 2024, led by the Philippines and Vietnam. By August 2025, the immediate national picture was uneven, with Vietnam expanding while Indonesia's sales continued to fall.
Electric vehicles remained a focus of longer term investment. Indonesia aims to produce 600,000 EVs by 2030, while Thailand targets zero emission vehicles accounting for 30% of vehicle production by the same year.
Chinese, Japanese and South Korean manufacturers are investing in local production, partnerships and business models including subscription services and electric vehicle ridesharing. These approaches broaden the ways companies can reach customers beyond a conventional vehicle purchase.
Price competition was expected to intensify, giving consumers more choices and potentially more affordable options. For Indonesia, the immediate challenge was to restore demand before its narrow lead disappeared. Malaysia's task was to sustain the strength of its national brands as incentives expired and more competitors entered the market.
Key Points
- Indonesia sold 865,723 new vehicles in 2024, ahead of Malaysia's record 816,747 by 48,976.
- Indonesia's sales fell 10% to 435,390 in the first seven months of 2025, with July down 18% from a year earlier.
- Perodua sold more than 358,000 vehicles in 2024, while Proton launched its first EV, the e.MAS 7, that December.
- Chinese brands increased their Indonesian market share from 3.4% in 2021 to 6.4% in 2024.
- Gaikindo sought renewed tax and credit support as weaker purchasing power and tighter financing weighed on Indonesian buyers.
- Malaysia's temporary electric vehicle incentives were scheduled to expire in late 2025.
- Forecasts pointed to a 9% decline in Malaysia's total industry volume and a 14% fall in Indonesia's light vehicle sales in 2025.
- Indonesia targets production of 600,000 EVs by 2030, while Thailand aims for zero emission vehicles to reach 30% of production that year.