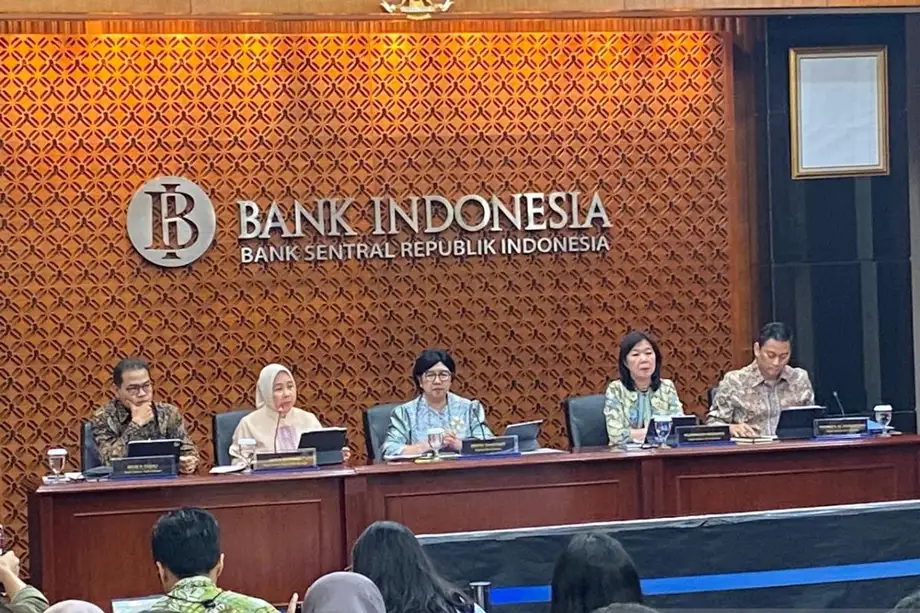
A third rate increase puts currency stability first
Bank Indonesia raised its benchmark interest rate by 25 basis points to 6% on November 18, 2026, taking its cumulative increase this year to 125 basis points as it sought to defend the rupiah and contain inflation. Indonesian stocks fell after the announcement, with the Jakarta Composite Index closing down 1.07% at 5,247.87, according to RTI Business data.
Contents
- A third rate increase puts currency stability first
- What changed, and how quickly?
- Why the rupiah and US rates matter
- Stocks retreat, with pressure beyond banks
- Banks face a widening gap between loan and deposit growth
- What bank executives expect for customers and profits
- Companies face more expensive fundraising
- BI pairs tighter rates with lending incentives
- Growth provides a cushion, but US policy remains a risk
- Key Points
The decision, reached at the central bank's November 17–18 Board of Governors meeting, brought the benchmark rate up from 5.75%. Governor Destry Damayanti said the move responded to global uncertainty and the possibility of further interest rate increases in the United States.
BI also raised its overnight deposit facility rate to 5.25% and its lending facility rate to 6.75%. A deposit facility rate of 5.00% was also reported, while the governor's announcement specified 5.25%. These facilities set the rates banks receive for placing money with BI or pay when borrowing overnight from it.
The central bank wants inflation to stay within 2.5%, plus or minus one percentage point, during 2026 and 2027. In simpler terms, its target range is 1.5% to 3.5%.
The decision creates a balancing act for Indonesia. Higher interest rates can make rupiah investments more attractive and help steady the currency. They can also increase the cost of borrowing for banks, businesses and households. BI is pairing the increase with liquidity incentives intended to keep credit flowing, including a financing measure scheduled to take effect on December 1.
What changed, and how quickly?
A basis point is one hundredth of a percentage point. November's increase of 25 basis points therefore means a rise of 0.25 percentage points, from 5.75% to 6%.
BI had already raised the benchmark by a combined 100 basis points in May and June, from 4.75% to 5.75%. The latest decision makes this the third increase of 2026 and puts the rate 1.25 percentage points above its level before those earlier moves.
The main dates show how the tightening has developed and when the next supporting measure begins:
- May and June 2026: BI raised the benchmark by a combined 100 basis points to 5.75%.
- November 17–18: The Board of Governors met to assess monetary policy.
- November 18: BI announced a further increase of 25 basis points to 6%.
- December 1: A financing channel under BI's liquidity incentive policy is scheduled to take effect.
Expectations before the announcement were divided. A poll of 13 institutions found seven expecting an increase and six expecting no change. In a broader poll of 27 economists, only 10 forecast an increase. The decision therefore surprised a majority in the larger survey, even though the smaller group leaned toward a rise.
Why the rupiah and US rates matter
Destry linked the decision to the appeal of Indonesian financial assets and the risk of further US monetary tightening. When US interest rates rise, investments in dollars can become more attractive, increasing competition for money that might otherwise go into Indonesian bonds or other assets.
A weaker rupiah also makes imports priced in foreign currencies more expensive in local money. That can feed into business costs and consumer prices, helping explain why BI is treating currency stability and inflation as connected goals.
Destry, BI's governor, described the decision as an early response to those risks:
"This is indeed a pre-emptive move, intended to anchor future inflation while also addressing global economic developments, specifically the possibility that the Fed may raise interest rates in December and potentially again in 2027," Destry said.
Senior Deputy Governor Aida S. Budiman gave a somewhat narrower central expectation: one more Federal Reserve increase before the end of 2026, followed by a pause in 2027. She said decisions would depend on incoming economic data.
BI is also using incentives to reduce hedging costs. Hedging allows an investor or business to limit losses from exchange rate movements, usually through a financial contract. Making that protection cheaper can lower one of the costs of investing in rupiah assets.
Currency trading remained volatile. The dollar traded around Rp18,260 during European hours, while the Australian dollar was quoted near Rp12,276 after a reported 3.13% rise against the rupiah. A rise in the Australian dollar against the rupiah means more rupiah are needed to buy one Australian dollar.
Stocks retreat, with pressure beyond banks
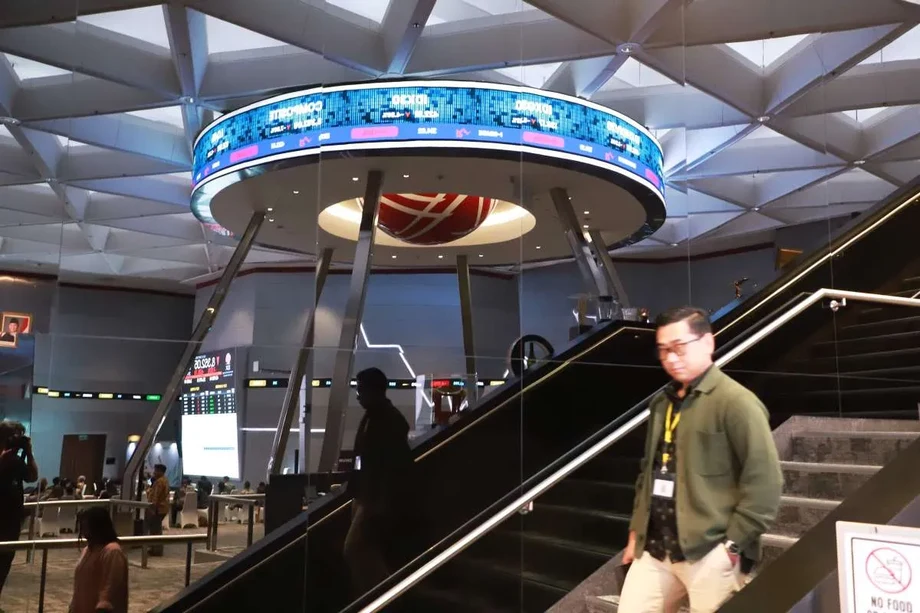
The Jakarta Composite Index, known locally as the IHSG, reversed an early gain on November 18. It opened around 5,323.49 and reached an intraday high near 5,374.36 before falling toward the close. RTI Business put the closing level at 5,247.87.
Market breadth showed a broad decline: 296 stocks fell, 91 rose and 70 were unchanged. The LQ45 index, which tracks a group of large and actively traded shares, dropped 0.77%.
Major state banks were among the declining stocks. Bank Rakyat Indonesia fell 1.94% to Rp3,040, Bank Negara Indonesia lost 1.92% to Rp3,570, and Bank Mandiri slipped 0.51% to Rp3,920.
Refinitiv sector data showed an even sharper retreat in basic materials, down 3.55%, followed by energy at 2.64%, real estate at 2.22% and industrials at 1.40%. BRI, Astra International, Amman Mineral Internasional, Bumi Resources and Bank Mandiri were among the stocks weighing on the index. Bank Central Asia and several consumer and technology shares helped limit the decline.
Trading activity figures varied between market tallies. RTI Business recorded 27.63 billion shares changing hands for Rp14.21 trillion across 1,597,332 transactions; another closing tally recorded 250.81 million lots and Rp10.64 trillion. The quoted turnover totals were therefore materially different, even though both closing accounts put the index's loss at 1.07%.
Banks face a widening gap between loan and deposit growth
Indonesia's banking system entered the decision with lending growing faster than deposits. September figures cited by Aviliani, head of research and economic and banking studies at the national banking association PERBANAS, showed loans rising 13.26% from a year earlier to Rp9,245 trillion.
Customer deposits grew 8.22% to Rp10,492 trillion. The difference between the two growth rates was 5.04 percentage points. That gap matters because banks need funding to support lending, and deposits are a major source of that money.
Aviliani described the rate increase as a measured response to external pressure and the need to stabilize the rupiah. She also warned that banks would need careful liquidity and funding management as lending outpaced deposit growth.
Higher benchmark rates can encourage banks to offer savers more interest to attract or retain deposits. Those payments raise banks' funding costs. Banks may then review lending rates, but Aviliani said the adjustment would vary according to each institution's funding structure, available cash and risk profile.
September banking indicators showed substantial financial buffers. The gross ratio of problem loans was 2.07%, while the net ratio was 0.82%. The capital adequacy ratio stood at 24.30%. This measure compares a bank's capital cushion with assets adjusted for their risks.
Liquidity ratios were also above the cited thresholds. Liquid assets equaled 105.7% of noncore deposits, against a 50% threshold, and 24.1% of total customer deposits, against a 10% threshold. Liquid assets are holdings that can be turned into cash relatively easily when needed.
What bank executives expect for customers and profits
CIMB Niaga President Director Lani Darmawan expected funding costs and competition for deposits to remain high after the move to 6%. She said her bank's liquidity remained healthy, with a loan to deposit ratio of about 88% to 89%.
That ratio compares lending with customer deposits. At 88% to 89%, the bank has roughly Rp88 to Rp89 in loans for every Rp100 in deposits. It offers a simple indication of how much deposit funding is already committed to lending.
Henky Suryaputra, finance and business planning director at Bank Sahabat Sampoerna, also described his bank's liquidity as relatively safe. He said the bank would review customer lending rates and that adjustments could affect its net interest margin.
Net interest margin measures the income a bank earns from interest after subtracting interest costs, relative to its earning assets. If deposit costs increase before loan income catches up, that margin can come under pressure.
Hendri Gunawan, senior vice president at BRI Danareksa Sekuritas, said banks would be among the first businesses affected because they use BI's benchmark as a reference when setting customer rates. He also saw a potential benefit: higher Indonesian rates could help keep foreign capital invested in the country.
Companies face more expensive fundraising
Guntur S. Putra, chief executive of Pinnacle Investment, said the increase would make borrowing more expensive for listed companies and complicate efforts to raise money. Companies that issue bonds may need to offer investors higher returns, increasing the cost of financing operations or replacing debt that is coming due.
A bond is a loan made by investors to a company or government. When market interest rates rise, new bonds generally need to compete with those higher rates. Existing bonds paying lower fixed interest can become less attractive, putting pressure on their market prices.
Guntur said businesses might need to adapt to a prolonged period of higher interest rates. For investors, he said suitable choices still depended on their goals and willingness to accept losses or price swings.
Mutual funds also have different mandates. Some invest mainly in government bonds, others hold corporate debt or shares, and their managers face different limits and objectives. A higher BI rate therefore affects funds through different routes rather than producing the same result across all products.
BI pairs tighter rates with lending incentives
BI is keeping its broader banking policy supportive of lending even as it raises the price of money. Its macroprudential approach, meaning measures directed at the health and lending capacity of the financial system, remains loose.
From December 1, the financing channel under the Macroprudential Liquidity Incentive Policy, known as KLM, will provide incentives of up to 3% of customer deposits. BI said the measure would support lending to sectors that create jobs and strengthen financing for micro, small and medium enterprises.
A money market development component provides incentives of up to 2% of deposits. Its purpose is to improve the redistribution of liquidity and help banks channel funding into lending.
Aida pointed to Rp2,526 trillion in undisbursed loans, credit that banks have approved but borrowers have not yet drawn. She cited that stock of approved credit, alongside continuing loan growth, when explaining why a rate increase would not automatically pull economic growth lower.
BI also plans to expand digital payments and strengthen risk management and payment infrastructure. Those measures sit alongside its interest rate and banking policies, with the aim of keeping financial transactions reliable while the economy adjusts.
Growth provides a cushion, but US policy remains a risk
Indonesia's economy grew 5.47% from a year earlier in the third quarter of 2026, up from 5.29% in the previous quarter. That was an acceleration of 0.18 percentage points, supported mainly by domestic consumption and investment.
The manufacturing Purchasing Managers' Index rose from 52.40 in September to 53.98 in October. A reading above 50 generally signals expansion in manufacturing activity. BI cited the improvement as part of the support for investment and maintained its 2026 growth forecast at 4.9% to 5.7%.
US developments remain central to the currency outlook. October US retail sales increased 0.2% from the previous month, while sales excluding cars and the retail control group each rose 0.6%. Resilient spending can complicate expectations for lower US interest rates when inflation remains a concern.
OCBC strategists expected the dollar's cycle to turn lower mainly in the second half of 2027 as support from inflation, relative US economic resilience and investment in artificial intelligence faded. BI's immediate task is more concrete: maintain the appeal of rupiah assets while its December lending incentives begin operating.
Key Points
- BI raised its benchmark rate to 6% on November 18, taking the year's cumulative increase to 125 basis points.
- The central bank aims to stabilize the rupiah and keep inflation within 1.5% to 3.5% in 2026 and 2027.
- The Jakarta Composite Index closed down 1.07%, with banks and several other major sectors under pressure.
- September loan growth of 13.26% exceeded deposit growth of 8.22%, increasing the importance of funding management.
- BI will introduce a financing liquidity incentive from December 1 while retaining supportive banking measures.
- BI maintained its 2026 economic growth forecast at 4.9% to 5.7%.