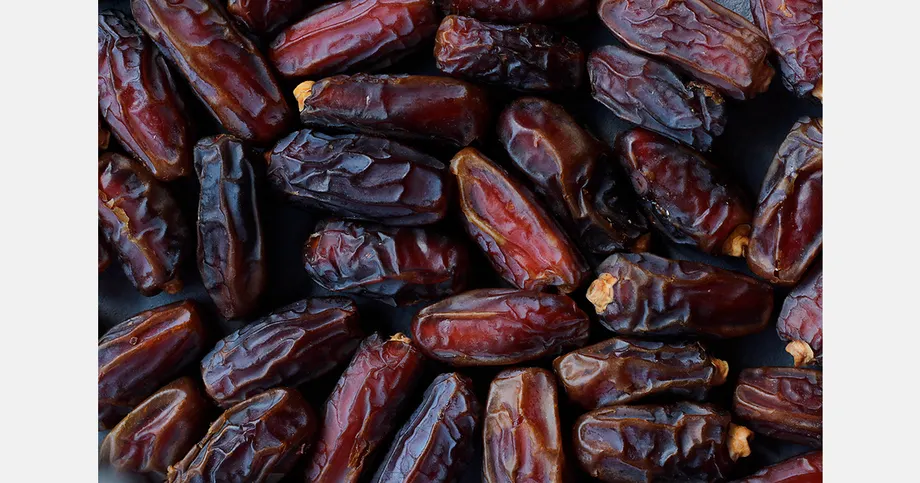
Dates duty falls to 5%, while apple and orange taxes nearly halve
Bangladesh's cabinet has approved a reduction in customs duty on imported dates from 25% to 5% until March 10, 2027, alongside a temporary cut in the total import tax burden on specified apples and oranges from 121.78% to 61%. The decisions aim to keep fruit supplies steady and prices within reach during the coming Ramadan.
Contents
- Dates duty falls to 5%, while apple and orange taxes nearly halve
- What the cut means for imported dates
- Apples and oranges have a shorter concession window
- How much could the tax reduction lower costs?
- Earlier Ramadan relief targeted several fruit taxes
- Why monthly VAT returns are returning
- From an October ordinance to a parliamentary law
- Key Points
Prime Minister Tarique Rahman chaired the cabinet's 27th meeting on Sunday morning, November 15, 2026, at the Secretariat. The Internal Resources Division submitted the fruit tax proposal, and the Cabinet Division announced the decisions after the meeting.
Apples and oranges will receive the lower tax rate from January 24 to February 23, 2027. Their concession therefore follows a different timetable from the relief for dates, which runs until March 10.
The cabinet also gave approval in principle and final approval to the draft Value Added Tax and Supplementary Duty (Amendment) Act, 2026. That measure seeks to turn an October ordinance restoring monthly VAT returns into an act of Parliament, reversing a move to quarterly filing in the budget for the 2026–27 financial year.
Households and businesses face different practical changes from the two decisions. Fruit importers will face lower taxes during the specified periods, with the government expecting better supplies and more affordable prices. Businesses covered by the VAT filing rule will again have to submit their returns every month, within 15 days after each monthly tax period ends.
What the cut means for imported dates
Dates receive a reduction of 20 percentage points in customs duty, from 25% to 5%. Measured against the previous duty rate, that is an 80% reduction in this particular tax.
For a simple illustration, if customs duty were calculated on an import value of Tk 100, the duty at 25% would be Tk 25. At 5%, it would be Tk 5, a saving of Tk 20 on that customs duty calculation. Other charges and the costs of bringing the fruit to shops would still enter the final selling price.
The Cabinet Division set March 10, 2027, as the end of the concession for dates. The government linked the decision to maintaining supplies and keeping prices affordable during Ramadan, when demand for the fruit rises.
Dates are commonly eaten when breaking the daily fast. Lowering the duty reduces one expense for importers buying supplies for that period. The eventual benefit for a family buying dates will depend on the price charged through the rest of the supply chain, including transport, storage and retail sales.
Apples and oranges have a shorter concession window
Apples and oranges will receive relief on their total import tax burden, which falls by 60.78 percentage points, from 121.78% to 61%. The new rate is approximately half the previous rate.
The decision covers oranges, known locally as malta, under HS code 08051090, and apples under HS code 08081090. An HS code is a product classification used by customs authorities to identify goods and apply the relevant trade rules and taxes. Naming the codes tells importers which classifications receive the concession.
January 24 to February 23, 2027, is the specified period for these lower rates. Importers planning purchases of the covered apples and oranges therefore have a defined window for the relief, rather than the later March deadline applying to dates.
The distinction between the two tax measures matters for understanding the size of the savings. For dates, the announced change concerns customs duty. For apples and oranges, the announced change concerns the combined import tax burden, which can contain several taxes charged at the border.
How much could the tax reduction lower costs?
The apple and orange figures allow a simple comparison of the tax component before and during the concession. On an unchanged customs assessment base of Tk 100, a total tax burden of 121.78% means Tk 121.78 in taxes. At 61%, that amount becomes Tk 61, a reduction of Tk 60.78.
Adding the same Tk 100 base to those illustrative tax amounts gives Tk 221.78 before the concession and Tk 161 during it. On that limited calculation, the base value plus import taxes falls by about 27.4%. The tax rate itself falls by about 49.9% relative to its previous level.
A shop price includes more than the customs assessment base and border taxes. The foreign purchase price, exchange rate, transport, storage and margins charged by businesses also affect what consumers pay. The government's expectation is that lower import costs will encourage supply and help make fruit more affordable.
The cabinet announcement set tax rates and concession periods rather than a retail price for any of the three fruits. Consumers will experience the policy through the prices and availability they encounter in markets, while importers receive the immediate reduction in the specified tax charges.
Earlier Ramadan relief targeted several fruit taxes
Earlier Ramadan measures attributed to the National Board of Revenue also reduced taxes on fresh fruit through several separate changes. A March 10 announcement lowered advance income tax on fruit imports from 10% to 5%.
Two notifications issued on March 16 reduced supplementary duty on fresh fruit from 30% to 25% and exempted the 5% advance tax. Those measures shared the aim of keeping commodity prices within reach during Ramadan.
Customs duty, supplementary duty, advance tax and advance income tax are different parts of the tax system. Customs duty is charged on imported goods, while supplementary duty is an additional levy. Advance taxes collect certain tax payments earlier, including at import. Changing several of these charges can reduce the amount an importer must pay when goods enter the country.
The November cabinet decision gives precise rates and dates for the three named fruits. Its treatment of apples and oranges states a combined burden of 61%, while its treatment of dates specifies the customs duty rate. Reading those details separately gives businesses a clearer picture of the relief approved for each product.
Why monthly VAT returns are returning
The VAT decision addresses a filing schedule changed in the 2026–27 budget. Before that change, businesses submitted VAT returns each month. The budget introduced a requirement to file after every three tax periods, or three months, with a further 15 days allowed for submission.
The Cabinet Division said quarterly filing created obstacles to revenue collection at the field level. The government therefore moved to amend section 64 of the Value Added Tax and Supplementary Duty Act, 2012, restoring the monthly schedule.
VAT, short for value added tax, is a tax associated with sales of goods and services. A VAT return is the statement a business submits to the revenue authority setting out the transactions and tax information required for the relevant period.
Under the revised ordinance issued in October, a return is due within 15 days after each monthly tax period. The change gives tax offices information more frequently and requires businesses to prepare submissions more often.
For a business following the stated filing intervals throughout a full year, monthly returns mean 12 scheduled submissions instead of four under quarterly filing. The 15 day submission window remains, but it follows each month rather than each three month period.
From an October ordinance to a parliamentary law
The president issued the VAT ordinance with cabinet approval while Parliament was not in session. An ordinance allows a legal measure to be introduced through that process between parliamentary sessions. The government is now seeking to convert the measure into legislation during the current session.
The cabinet approved the draft Value Added Tax and Supplementary Duty (Amendment) Act, 2026, for that purpose. The Legislative and Parliamentary Affairs Division is responsible for the legal vetting associated with the draft's approval. A date for parliamentary passage was not announced.
The sequence brings together the budget change, the October reversal and the cabinet's November decision, followed by the scheduled fruit concessions in 2027:
- 2026–27 budget: VAT filing changed from monthly to once every three months.
- October 2026: An amended ordinance restored monthly returns, due within 15 days after each tax period.
- November 15, 2026: The cabinet approved the draft VAT amendment legislation and the fruit import tax concessions.
- January 24, 2027: The lower total import tax burden for the specified apples and oranges begins.
- February 23, 2027: The apple and orange concession period ends.
- March 10, 2027: The 5% customs duty concession for dates ends.
Importers must plan around the separate concession periods, while businesses subject to the VAT rule must organise their records for monthly submissions. For households, the intended benefit is more readily available fruit at affordable prices during Ramadan.
Key Points
- Customs duty on imported dates falls from 25% to 5% until March 10, 2027.
- The total import tax burden on specified apples and oranges falls from 121.78% to 61% from January 24 to February 23, 2027.
- The covered customs codes are 08051090 for oranges and 08081090 for apples.
- The government aims to maintain fruit supplies and keep prices affordable during Ramadan.
- The cabinet approved draft legislation to convert the October VAT ordinance into law.
- The revised VAT rule requires monthly returns within 15 days after each tax period, replacing quarterly filing.