India draws $5.5 billion as investment shifts toward digital infrastructure
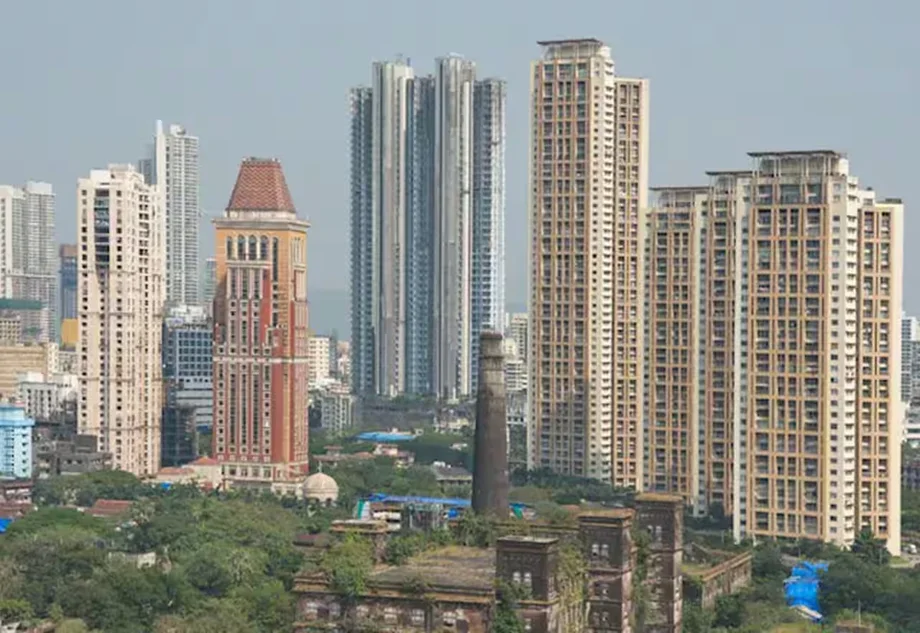
India attracted $5.5 billion in foreign real estate investment during the first nine months of 2026, ahead of the $3.7 billion invested in mainland China. The $1.8 billion gap puts India about 49% higher, making it an increasingly important destination for international property capital as investment activity recovers across Asia and the Pacific.
Contents
- India draws $5.5 billion as investment shifts toward digital infrastructure
- Two investment measures tell different parts of the story
- Foreign investors drove the third quarter
- Why data centres are attracting so much money
- Office income remains a strong draw
- A regional recovery with uneven growth
- A small group of buyers controls a larger share
- Urban growth and borrowing costs shape India's outlook
- Key Points
Data centres are a major part of that shift. Investment in these facilities reached $3.9 billion in India during 2026, nearly twice the amount recorded for offices. Development land nevertheless remained the country's largest individual investment category, showing that investors are pursuing both existing properties and sites for future construction.
India's appeal also rests on income from commercial buildings. Premium offices offered yields of about 7.75% to 8%, while office rents were rising by roughly 7% to 8% annually. Those figures give investors two potential sources of income growth: rent collected today and higher rents as leases change.
Two investment measures tell different parts of the story
Cushman & Wakefield's India Capital MarketBeat, published on October 15, 2026, recorded $2.1 billion in institutional real estate investment during the third quarter. Its total for the first nine months reached $5.5 billion, an increase of 11% from the same period in 2025.
The matching $5.5 billion totals refer to different measures. The India and China comparison tracks capital crossing national borders, while Cushman & Wakefield's figure tracks institutional investment, including participation by domestic and foreign investors. Institutional investors are organisations such as investment funds and insurers that pool large amounts of money to buy assets.
A broader transaction tally, including land deals, put India's real estate activity at $14.3 billion over the previous four quarters, up 13% in dollar terms. Each measure answers a different question: where foreign money is going, how institutions are investing, and how much property is changing hands.
Foreign investors drove the third quarter
Foreign investors accounted for 68% of capital deployed in India during the third quarter, according to Cushman & Wakefield. Applied to its $2.1 billion quarterly total, that share represents approximately $1.43 billion. Domestic investors supplied the remaining 32%, or roughly $672 million.
Projects spanning several cities attracted most investment. Mumbai and Delhi NCR, the National Capital Region around New Delhi, remained important destinations. The prominence of projects across several locations shows that capital was flowing into portfolios and broader development programmes as well as individual buildings.
The investment timeline also shows how financing conditions and transaction activity developed through the year:
- April to June 2026: The Reserve Bank of India raised its policy interest rate by 25 basis points, equivalent to 0.25 percentage points.
- July to September 2026: Institutional property investment reached $2.1 billion, with foreign investors contributing 68%.
- January to September 2026: Institutional investment totalled $5.5 billion, up 11% from a year earlier.
- October 15, 2026: Cushman & Wakefield published its assessment of the third quarter.
Why data centres are attracting so much money
Data centres received 52% of investment inflows in Cushman & Wakefield's third quarter assessment, ahead of offices and hospitality. A data centre houses computers and networking equipment that store information and run digital services. Its property requirements include dependable electricity, cooling systems and strong communications connections.
India's larger $3.9 billion data centre investment figure was associated with major development commitments involving AirTrunk and EQT, alongside infrastructure expansion by hyperscalers. Hyperscalers are technology companies operating computing networks on a very large scale, often to supply cloud services.
The investment figures cover different transaction categories and periods: the $3.9 billion describes data centre capital during 2026, while the 52% share comes from the quarterly institutional assessment. A common transaction breakdown reconciling those figures has not been published in the cited findings.
Across Asia and the Pacific, data centre transactions rose 79% during the first nine months of 2026 compared with the same period a year earlier. That was the fastest growth among the property sectors tracked, placing India's surge within a wider regional movement toward digital infrastructure.
Office income remains a strong draw
Grade A offices, generally modern buildings with good facilities and desirable locations, offered Indian investors yields of around 7.75% to 8%. A property yield expresses annual rental income as a percentage of the building's value. At an 8% yield, a property valued at $100 million would generate roughly $8 million in annual property income under that calculation.
India's government bond maturing in 10 years yielded about 7.2%, providing investors with a benchmark for comparing returns. The quoted office yields sit roughly 0.55 to 0.8 percentage points above that figure, broadly matching the reported premium of 60 to 80 basis points. A basis point is one hundredth of a percentage point.
Property investors also face costs and risks that affect their eventual return, including borrowing expenses, repairs, empty space and changes in building values. Rising rents can help income grow, while vacancies or higher financing costs can reduce what owners retain.
Office rents increasing by around 7% to 8% annually help explain continued interest in commercial acquisitions. Cushman & Wakefield also identified strong leasing activity, fundraising by funds focused on offices, and expanding portfolios held by real estate investment trusts. These trusts, known as REITs, allow investors to own shares in a portfolio of income producing properties.
A regional recovery with uneven growth
Property transaction volumes across Asia and the Pacific reached nearly $200 billion in the first nine months of 2026, up 27% from a year earlier. India was attracting foreign capital during a broader recovery, with several markets and property types recording sharp increases.
Retail transactions rose 36%, while offices, industrial properties and hotels each recorded growth of around 22%. Apartment transactions fell 12%, making them the only major segment in the assessment to contract.
Singapore recorded a 220% increase in investment volume, meaning activity reached approximately 3.2 times its earlier level. Taiwan's transaction volume doubled. Large deals and acquisitions of property businesses or portfolios helped drive those gains, so changes in a few major transactions could have a substantial effect on national totals.
A small group of buyers controls a larger share
The 25 largest buyers accounted for 47% of regional real estate transaction volume in the first half of 2026, compared with 34% two years earlier. Their share increased by 13 percentage points, reaching the highest level recorded since at least 2016. The 10 largest investors alone accounted for nearly a third of activity.
Transactions exceeding $500 million were particularly active in Singapore, Australia, South Korea and Japan. Properties in the middle of the market faced a smaller pool of potential buyers, even as total regional investment increased.
For owners seeking to sell, the identity and spending capacity of major institutions therefore matter alongside headline market growth. A recovery driven by a relatively small group of buyers can produce very different selling conditions for a large portfolio and a smaller standalone property.
Urban growth and borrowing costs shape India's outlook
About 36% of India's population lives in urban areas, compared with 66% in China, a difference of 30 percentage points. India is adding approximately 12 million urban residents annually, more than China's yearly increase, creating demand for workplaces, services and other urban property.
Investors still need projects in locations where people and businesses can use them. Population growth supports the demand story, while the success of individual developments depends on access, infrastructure, tenants and the price paid for land and construction.
Financing conditions provide another part of the picture. Cushman & Wakefield said borrowing costs remained substantially below their 2024 levels despite the Reserve Bank of India's rate increase during April to June 2026. Lower borrowing costs than in that earlier period continued to support investment, although the rate increase raised the cost of new borrowing at the margin.
India's investment momentum therefore combines several forces: foreign purchases, large digital infrastructure commitments, growing office rents and expanding cities. The practical outcome will depend on how that capital becomes completed facilities, occupied buildings and rental income, while investors continue comparing Indian prices with opportunities elsewhere in Asia.
Key Points
- India attracted $5.5 billion in foreign real estate investment in the first nine months of 2026, compared with China's $3.7 billion.
- Cushman & Wakefield separately recorded $5.5 billion in institutional investment over the same period, up 11%.
- Foreign investors supplied 68% of India's $2.1 billion institutional investment total in the third quarter.
- Data centres attracted $3.9 billion during 2026 and accounted for 52% of inflows in the quarterly institutional assessment.
- Indian Grade A office yields were around 7.75% to 8%, with rents rising roughly 7% to 8% annually.
- Regional transactions approached $200 billion, while the 25 largest buyers accounted for 47% of activity in the first half of 2026.