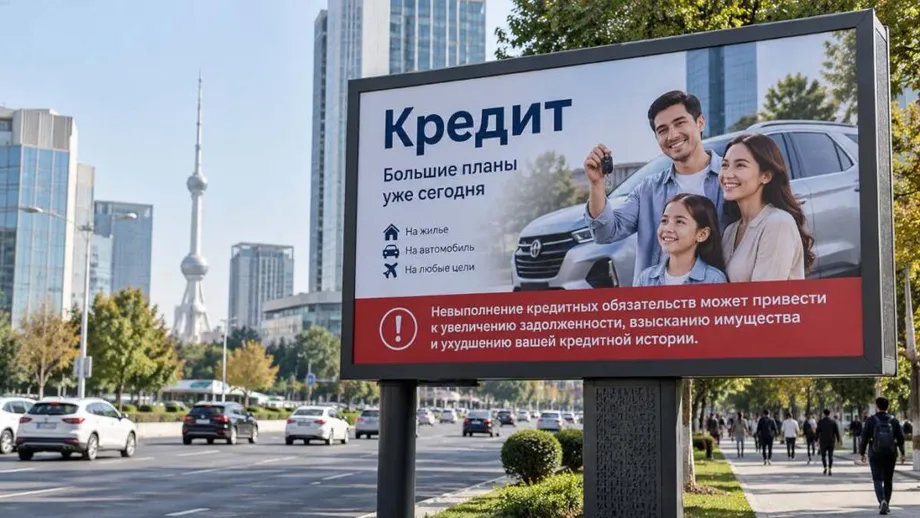
Loan warnings must take up at least 10% of advertisements
Uzbekistan has written a minimum size for debt warnings into its advertising law: advertisements for loans, including microloans, must devote at least 10% of their main display area or running time to explaining that failure to repay can create financial risks.
Contents
- Loan warnings must take up at least 10% of advertisements
- How the warning works across different formats
- Why regulators challenged quick credit promotions
- How the measures reached the law books
- Bank agreements need a larger warning
- What missed repayments can mean
- Price disclosure tackles a different part of the decision
- Borrower controls and disputed card charges
- Key Points
President Shavkat Mirziyoyev signed Law No. O'RQ-1187 on November 10, 2026, according to the Ministry of Justice. The amendments to Article 43 of the Law on Advertising follow earlier Central Bank requirements that also put warnings on the first page of bank credit agreements, before the main contract text.
For borrowers, the changes mean the promise of quick access to money must appear alongside a warning about the obligations that follow. For banks and advertisers, the rules establish a measurable requirement governing the space or time given to that warning.
A separate presidential resolution, adopted on July 15, 2026, requires advertisements for credit and installment purchases offered to individuals to disclose both the amount paid above the basic price and the final cost. Together, the measures address two different decisions: whether a customer can afford the purchase and what may happen if repayments fall behind.
The Competition Committee had argued that advertising often drew attention to how easily and quickly people could borrow while giving too little information about future financial difficulties. Its concerns extended beyond the wording of advertisements to growing debt burdens and disputed credit card charges.
The November law follows parliamentary consideration in March and Senate approval in August. The commencement date for that law was not specified in the announcement described by the ministry; the earlier Central Bank resolution has its own rule for taking effect.
How the warning works across different formats
Printed and graphical advertisements must reserve at least 10% of their main advertising area for the warning. Audio and video advertisements must give it at least 10% of their total duration. The requirement covers credit products, including microloans.
A 30 second video, for example, would need at least three seconds of warning time. A 60 second audio advertisement would need at least six seconds. These are calculations from the 10% requirement, giving advertisers a straightforward way to understand the minimum.
The message must explain that failure to meet debt obligations can lead to financial risks. A microloan may be marketed as a convenient way to cover an immediate expense, but it still creates a repayment obligation. The warning brings that obligation into the same advertisement as the offer.
The Central Bank had already adopted similar requirements for banks in Resolution No. 24/18, approved on September 15, 2026. The Ministry of Justice registered it as No. 3948 on September 30. Signed by Central Bank Chairman Timur Ishmetov, it takes effect one month after official publication.
The November amendments place the warning requirement in the Law on Advertising itself, while the Central Bank rules also govern how commercial banks present risks when customers reach the agreement stage.
Why regulators challenged quick credit promotions
The Competition Committee proposed changing Article 43 because it saw aggressive marketing accompanying increased activity in microloans and consumer credit. In October 2025, it said promotions frequently concentrated on fast, easy borrowing and left consumers without enough information about the financial risks ahead.
The committee linked those practices to a sharp rise in debt burdens. A debt burden is the pressure repayments place on a household budget: money committed to a loan is money that cannot be used for food, rent, transport or other expenses.
Bahodir Mirzayev, head of the Central Bank service responsible for protecting banking consumers, had outlined plans for mandatory advertising warnings in September 2025. The proposal sought to make future costs and possible financial difficulties part of the information presented before a customer borrowed.
On March 17, 2026, the Legislative Chamber considered the same concern when approving the bill in its second reading. Lawmakers said microloan advertisements and marketing materials stressed quick access while giving less attention to the substantial financial obligations that could follow.
Existing advertising requirements already prohibit exploiting a consumer's trust or lack of experience and knowledge. They also require disclosure of essential contract terms and exclude information unrelated to the advertised financial service. The new rule adds a specific warning with a defined minimum size or duration.
How the measures reached the law books
Uzbekistan's advertising changes developed through several separate decisions. The presidential resolution addressed cost disclosure, the Central Bank set requirements for banks, and Parliament considered amendments to the advertising law.
- September 2025: Central Bank consumer protection official Bahodir Mirzayev outlined proposals for mandatory credit risk warnings.
- October 2025: The Competition Committee raised concerns about promotions focused on easy borrowing and proposed changing Article 43.
- March 17, 2026: The Legislative Chamber approved the bill in its second reading, following consideration in March.
- July 15, 2026: Presidential Resolution No. PP-265 required disclosure of overpayments and final costs in credit and installment advertisements for individuals.
- August 2026: The Senate approved the advertising legislation.
- September 15 and 30, 2026: The Central Bank adopted Resolution No. 24/18, and the Ministry of Justice subsequently registered it as No. 3948.
- November 10, 2026: President Mirziyoyev signed Law No. O'RQ-1187, adding the warning requirement to the Law on Advertising.
The sequence matters to customers and lenders because the requirements operate at different points. Advertisements must address both price and repayment risks, while bank agreements must give a fuller warning before the contractual text begins.
During Senate consideration, lawmakers also proposed treating information that improves financial literacy as social information. That proposal accompanied the effort to make financial obligations easier for citizens and businesses to understand.
Bank agreements need a larger warning
The Central Bank rules require a warning on the first page of a credit agreement, before the main text. It must occupy at least 30% of the page's main area, giving it a more prominent place than the minimum required in advertisements.
The 30% threshold is three times the 10% advertising threshold, although each applies to a different surface. An advertisement introduces a product; an agreement is the document a borrower signs to accept its terms.
Banks can present the approved warning through graphics, an infographic or another visual format, provided they retain its full content. The rule allows the presentation to change while keeping the explanation of possible consequences intact.
The standard warning explains that late repayment can increase the total debt and lead to enforcement measures. It also describes consequences for property, bank account funds, guarantors, travel and credit history. A guarantor is someone who agrees to repay if the borrower fails to do so.
Warning text is also to be included in microloan agreements. For customers, placing this information before the main terms makes it part of the decision to sign, rather than something encountered only after repayment problems arise.
What missed repayments can mean
A borrower who falls behind may face a growing balance and a demand for repayment through court. The warning explains that property can be recovered to repay the debt. If selling that property does not raise enough money, the borrower can still owe the remaining amount.
Other people can also face financial consequences. Recovery may extend to property pledged by a third party, and a guarantor may be required to repay. A person who pays as a guarantor or loses pledged property may then seek recovery from the borrower.
Funds in bank accounts may be seized. The warning also lists a possible temporary restriction on leaving Uzbekistan, imposed through a decision by a court or state enforcement officer. These are possible consequences connected to enforcement, rather than a single outcome for every missed payment.
A damaged credit history can affect later borrowing too. Credit history is a record of borrowing and repayment that lenders use when assessing applications. Late payments may make a new loan harder to obtain or lead to less favorable terms, potentially including higher interest rates.
The warning therefore reaches beyond the amount due on the next payment date. It describes how repayment problems can affect assets, people who supported the loan and access to credit later.
Price disclosure tackles a different part of the decision
Presidential Resolution No. PP-265 requires advertisements for credit and installment purchases offered to individuals to state the overpayment compared with the basic price of goods or services, as well as the final cost. The overpayment is the extra amount a customer pays because the purchase is financed rather than paid for at its basic price.
A customer looking at a small monthly installment needs that final figure to understand the full commitment. The price disclosure and risk warning answer different questions: how much the arrangement will cost, and what may happen if the customer cannot meet its terms.
A separate plan to offer loans for domestically produced household appliances at 18% annual interest shows why several types of information matter. An annual rate describes interest over a year; the final amount payable also depends on the amount borrowed, the repayment period and applicable charges. The appliance lending proposal was described as a plan.
Financial services advertising also faces a restriction on promises about future performance or profitability. Such results cannot be guaranteed when they cannot be determined at the time the service agreement is signed.
The Central Bank amended its enforcement framework as well. A bank credit product deemed misleading to consumers can provide grounds for enforcement measures under the rules governing banks, credit organizations outside the banking sector and credit bureaus.
Borrower controls and disputed card charges
More than 438,000 people had voluntarily restricted their ability to take out loans, with the largest age group being 26 to 35. That figure shows substantial use of a tool through which individuals can limit access to new borrowing.
The credit bureau has also introduced mobile application features to help people assess guarantor risks, track obligations and manage credit histories. Those tools address commitments that may be less visible than a person's own monthly loan payment, including responsibility for someone else's debt.
The Competition Committee has urged borrowers to assess their financial capacity and examine loan conditions, interest rates and payment obligations carefully. Its concerns also extend to how banks classify transactions after customers obtain credit cards.
The committee asked the Central Bank to review practices in which certain utility, education, medical, insurance and tax payments were treated like cash withdrawals and attracted interest or fees. It sought reconsideration of the charges and refunds of fees collected without justification.
Further restrictions on automatic deductions for loan repayments are planned from 2027. Alongside the advertising and agreement requirements, those plans address another stage of borrowing: how payments are collected after a loan has been issued.
Key Points
- Law No. O'RQ-1187, signed on November 10, 2026, requires financial risk warnings in advertisements for loans, including microloans.
- Warnings must occupy at least 10% of the main advertising area or at least 10% of an audio or video advertisement's duration.
- Central Bank rules require warnings before the main text on the first page of bank credit agreements, occupying at least 30% of the page's main area.
- The agreement warning covers growing debt, property recovery, guarantor liability, seizure of account funds, possible travel restrictions and damage to credit history.
- A July 2026 presidential resolution requires credit and installment advertisements for individuals to show overpayments and final costs.
- Regulators are also addressing misleading bank products, disputed credit card charges and automatic loan payment deductions.