A pause after two increases, with another rise in view
South Korea's central bank heads into its October 22, 2026, interest rate meeting with its benchmark at 3%, September inflation at 2.9% and household borrowing rising again. A survey of 100 bond market participants found that 93% expected the Bank of Korea to leave rates unchanged after increases in July and August.
Contents
- A pause after two increases, with another rise in view
- How the benchmark reached 3%
- Why surveys point to a hold now and a hike later
- Inflation is easing, but remains above target
- The export boom gives the bank room to stay restrictive
- House prices and borrowing add another source of pressure
- Borrowers need time to adjust
- A stronger won and lower bond yields complicate the picture
- What investors will watch after the decision
- Key Points
The expected pause comes as the economy sends policymakers competing signals. Semiconductor exports reached $27.5 billion in the first 20 days of October, while household loans at five major banks increased by 2.7643 trillion won between the end of September and October 15. Strong business activity supports growth, but rising prices and debt give the bank reasons to keep borrowing expensive.
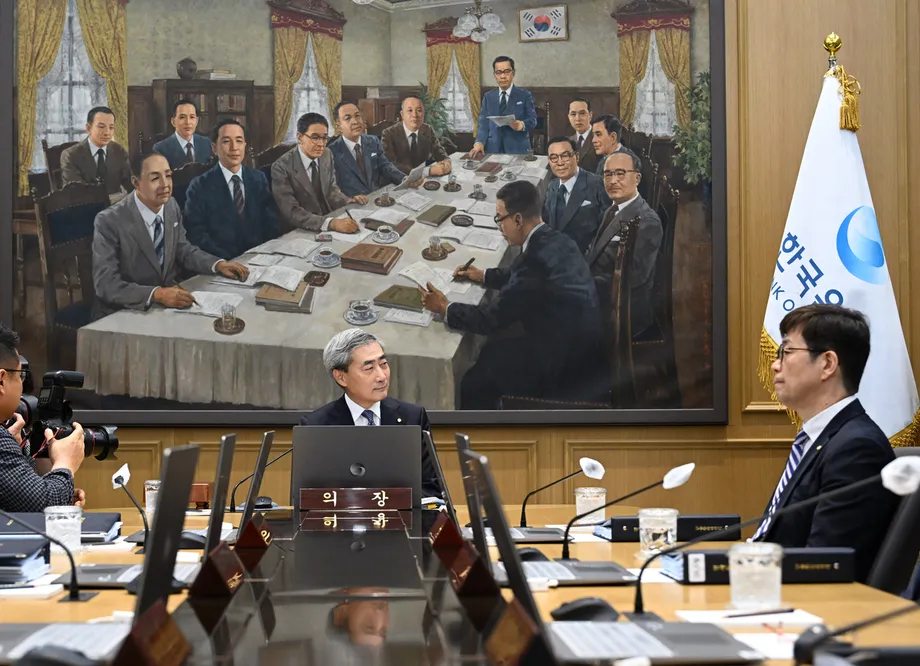
The Monetary Policy Board's decision was still pending ahead of the meeting. Governor Shin Hyun-song was scheduled to explain the outcome and the bank's outlook at a press conference beginning at about 11:10 a.m. on October 22.
A hold would give households, businesses and financial markets more time to absorb the previous increases. Many economists nevertheless expect the bank to raise rates again at its final policy meeting of the year in November. Their central concern is that inflation will stay above the bank's 2% target even as the immediate effects of higher energy prices ease.
How the benchmark reached 3%
The Bank of Korea's official rate history records an increase to 2.75% on July 16 and another to 3% on August 27. Each move added 0.25 percentage points, taking the benchmark half a percentage point above its previous level of 2.5%.
The benchmark helps guide the cost of money across the economy. Higher rates generally make borrowing more expensive and saving more attractive, slowing spending and reducing pressure on prices. Those effects take time to pass through existing loans, business plans and household budgets.
The recent policy sequence, and the next scheduled developments, are:
- May 29, 2025: The benchmark fell to 2.5%.
- July 16, 2026: The bank raised it to 2.75%.
- August 27: A second increase brought it to 3%.
- October 22: The board meets to decide whether to pause or raise rates again.
- Late October: Third quarter GDP figures are due.
- November: The board holds its final rate meeting of 2026.
The October decision therefore turns partly on timing. Policymakers must judge how much restraint the two increases are already creating while deciding whether persistent inflation requires more action.
Why surveys point to a hold now and a hike later
Expectations of an October pause extend beyond the bond market survey. All six economists in another poll expected a hold, while a larger survey of 20 professors and financial specialists found that 19, or 95%, expected the benchmark to stay at 3%.
In that larger survey, 18 respondents, or 90%, expected the next increase in November. One each chose January and February. The most common forecast for the eventual peak in rates was 3.5% in the first half of 2027, selected by 13 respondents. Two projected 3.75%, while one expected 4% in the second half.
Jung Yong-taek, chief economist at IBK Investment & Securities, explained why a pause could fit alongside concern about inflation:
Prices are high across the board, but the central bank has already raised rates twice preemptively, so it needs time to verify the policy effects.
Economists describe the likely outcome as a hawkish hold. In plain language, that means leaving the rate unchanged while warning that further increases may follow. The board's vote and Shin's explanation will help investors judge how strongly the bank is considering another rise.
Inflation is easing, but remains above target
Consumer price inflation slowed to 2.9% in September from 3.1% in August, after reaching 3.2% in June. September's reading was still 0.9 percentage points above the bank's 2% target. Core inflation, which removes volatile food and energy prices to show the broader price trend, stood at 2.8%.
Oil is one immediate source of pressure. Brent crude approached $112 a barrel during trading on October 20, its highest level in five months, as the prolonged Middle East war kept energy costs elevated. More expensive fuel can spread through delivery charges, manufacturing costs and household bills.
Domestic demand is another concern. Higher earnings and investment linked to the semiconductor boom can give companies and households more money to spend. At its October 2 inflation review, the Bank of Korea expected consumer prices to continue rising strongly, particularly core prices, as cost increases passed through the economy and demand pressures grew.
September producer prices, which measure prices received by domestic producers, rose 0.2% from August and 7.7% from a year earlier. These costs matter to businesses deciding whether to absorb smaller profits or charge customers more.
A survey conducted from October 13 to 16 found that all 12 respondents to the monetary policy question identified elevated inflation as a key variable. Six highlighted oil prices and risks from the Iran war, while four cited demand pressures connected to the semiconductor boom.
Forecasts also point to a slow return toward the target. Most respondents expected consumer inflation of 2.2% to 2.5% next year, with core inflation generally between 2.4% and 2.6%. Heo Munjong, head of the Woori Finance Research Institute, gave this assessment:
Reflecting elevated inflation expectations, rising prices for personal services and improved income conditions amid the semiconductor boom, core inflation will remain sticky at around 2.5%.
The export boom gives the bank room to stay restrictive
Customs figures released on October 21 showed exports of $61.6 billion in the first 20 days of October. Shipments rose 105.4% from a year earlier before adjusting for working days. Imports increased 42.8%, leaving a trade surplus of $14.5 billion.
The timing of the Chuseok holidays affected that comparison: the holiday fell in September in 2026 and October in 2025. Adjusting for working days gives a more useful measure of the pace of trade. On that basis, exports rose 65.9%, compared with an 89.8% increase during the corresponding period in September.
Semiconductor exports increased 222.5% to $27.5 billion, accounting for about 45% of the $61.6 billion export total. Petroleum product shipments rose 68.3%, and automobile exports increased almost 41%. By destination, exports to China and the United States each grew about 155%; shipments to Malaysia rose 363.2% and those to Singapore increased 121.1%.
The current account surplus reached $279.2 billion from January through August, compared with $69.67 billion a year earlier, about four times as much. The current account is broader than the goods trade balance because it also includes services and income flows.
Deputy Prime Minister and Minister of Economy and Finance Lee Hyeong-il said on October 16 that real GDP growth could reach 3.6% this year. That is 0.3 percentage points above the Bank of Korea's August forecast of 3.3%. In the October 13 to 16 economist survey, eight of 11 respondents to the growth question expected at least 3.5%.
Real GDP measures output after adjusting for price changes. Nominal GDP, which includes those changes, rose 26.4% from a year earlier in the second quarter, the fastest increase since the third quarter of 1979. For rate decisions, the bank must consider both how much the economy produces and how quickly prices are rising.
House prices and borrowing add another source of pressure
Seoul apartment prices rose for 88 consecutive weeks through the second week of October, according to the Korea Real Estate Board. Prices were weakening in the three Gangnam districts, while increases were gathering pace in some outer parts of Seoul and southern Gyeonggi Province.
Household lending also reversed its September decline. Outstanding household loans at KB Kookmin, Shinhan, Hana, Woori and NH NongHyup totalled 783.5983 trillion won on October 15, up 2.7643 trillion won from the end of September.
Those banks had recorded a decline of 1.2852 trillion won during September, their first monthly decrease since March. The increase in the first half of October was already more than twice the size of that September fall.
Housing and borrowing matter because rising property prices can encourage people to take on larger loans. Higher interest rates can cool that process, but they also raise costs for existing borrowers, particularly those whose loan rates change with market conditions.
Borrowers need time to adjust
Shin addressed that burden during a parliamentary audit on October 12. The governor said the bank considers how quickly households and businesses can adjust when setting policy:
When we conduct monetary policy, we always assess how much time economic agents need to adapt and evaluate their ability to do so.
Concern about vulnerable borrowers had already appeared inside the board. Hwang Kun-il dissented in August in favour of holding rates, citing worries that included the growing interest burden on vulnerable groups.
The strength of semiconductor exports also reaches different parts of the economy unevenly. Ahn Yeha, a researcher at Kiwoom Securities, expected growth led by chips to continue next year while warning that the gap between stronger and weaker sectors could widen. A household facing higher debt payments may therefore feel little benefit from record export sales.
Shin's public language has reflected the pressure to act early against inflation. An analysis of about 33,000 Korean characters from his answers at three policy press conferences counted 114 references related to prices and 97 related to growth. References to preemptive or early action rose from two each in May and July to 28 in August, when the bank delivered its second increase.
A stronger won and lower bond yields complicate the picture
The won strengthened to 1,322.8 per dollar during trading on October 21, its strongest intraday level since October 2, 2024. Exporters selling dollars helped the move. A stronger won reduces the local currency cost of imports, offering some relief from expensive oil and other foreign purchases.
Government bond markets have also become less tense than earlier in October. The yield on bonds maturing in three years fell from 3.983% on October 8 to 3.854% on October 16. The yield on bonds maturing in 10 years declined from 4.395% to 4.182% over the same period.
Yields briefly rose on October 19, with the three year benchmark closing at 3.877% and the 10 year benchmark at 4.205%. By the morning of October 21, the three year yield was down to 3.832%, leaving a gap of 0.832 percentage points above the policy rate.
A bond yield is the return available at its market price. Yields generally fall when bond prices rise. Lower market yields can ease financing costs even while the central bank keeps its own rate steady, making the board's message about future policy especially relevant.
What investors will watch after the decision
The government has cut planned October Treasury issuance by 5 trillion won, using excess tax revenue instead of raising that money through bond sales. A smaller supply of bonds can support prices and restrain yields. In the survey of 20 specialists, nine said further reductions of 5 trillion to 10 trillion won in November and December could help stabilize the market.
Bond sentiment has improved. The Korea Financial Investment Association's bond market survey index rose to 99.1 for November from 89.7 for October. The reading remained just below 100, the threshold separating expectations of improving conditions from expectations of deterioration.
Economists differ on how the October vote will look. Kong Dong-rak of Daishin Securities expected a unanimous hold while leaving open the possibility of a vote for an increase. Ahn Jae-kyun of Korea Investment & Securities expected one member to favour a rise and saw the benchmark potentially reaching 3.5% in the first quarter of 2027.
The next major test will be whether inflation and growth support those expectations. Third quarter GDP figures are due near the end of October, before the November rate meeting. Shin's October 22 press conference will give borrowers and investors the bank's latest assessment of how much more restraint the economy needs.
Key Points
- The Bank of Korea enters its October 22 meeting with the benchmark at 3%, following increases in July and August.
- Some 93% of surveyed bond market participants expected an October hold; 18 of 20 specialists in another survey expected a November increase.
- September consumer inflation was 2.9% and core inflation was 2.8%, both above the bank's 2% target.
- Semiconductor exports reached $27.5 billion in the first 20 days of October, about 45% of total exports.
- Household loans at five major banks rose by 2.7643 trillion won between September 30 and October 15.
- The governor's press conference and late October GDP figures will provide the next guidance before November's meeting.