A lease ending in 2066 will now end in April 2027
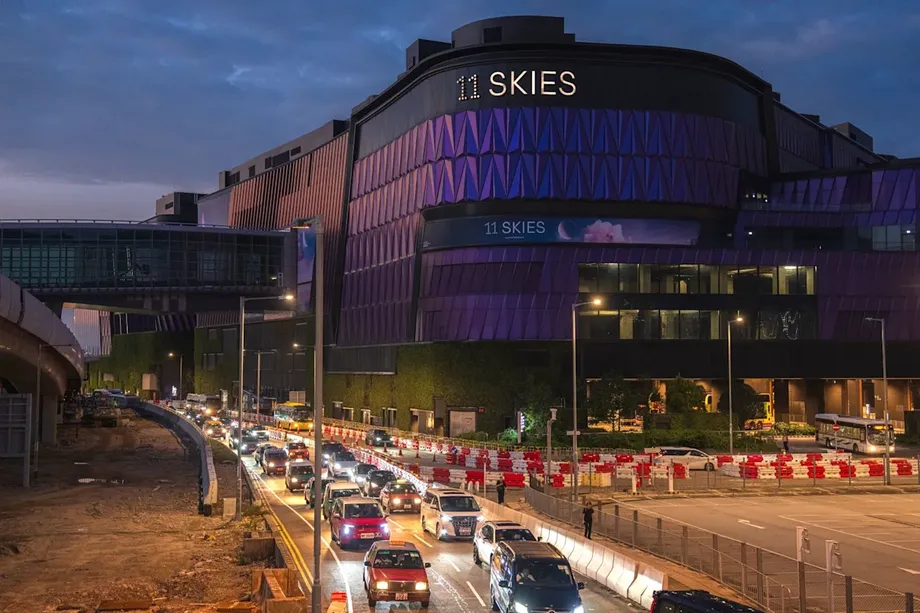
Hong Kong's Airport Authority has agreed to take over the three office towers and entertainment complex at 11 SKIES without paying for the assets, allowing New World Development to leave a project carrying guaranteed annual rent of at least HK$1.8 billion. The agreement, announced on September 30, 2026, brings forward the end of a lease originally scheduled to expire in September 2066.
Contents
- A lease ending in 2066 will now end in April 2027
- From rent concessions to a complete exit
- What New World must give up and pay
- A large accounting loss, but a different cash picture
- The share option preserves the Cheng family's role
- Debt pressure extends beyond the airport project
- Asset sales and new investment remain central
- The authority plans entertainment rather than a conventional mall
- Support buys time, without settling the company's future
- Key Points
The authority's September 30 announcement says New World will also provide more than HK$3 billion in cash and cash equivalents. The lease will terminate on April 1, 2027, when the developer is scheduled to hand over the project beside Hong Kong International Airport.
The arrangement offers relief from a large future commitment, but comes with an immediate financial cost. New World recorded a loss of approximately HK$18.3 billion from the termination, contributing to a loss attributable to shareholders of HK$28.15 billion for the financial year ended June 2026. Its total debt stood at about HK$143.3 billion.
A separate share option gives the Airport Authority a possible route into New World itself. Reports describe a right to buy 750 million shares from Chow Tai Fook Enterprises, the Cheng family's investment company, for HK$2.25 billion within three years. That right is subject to conditions preserving the family's position as the leading shareholder.
The deal therefore connects two challenges: finding a viable operating model for a vast airport commercial development and giving one of Hong Kong's largest property groups more time to repair its finances. It removes a major rent obligation, but does not erase New World's borrowing or guarantee a new equity investment.
From rent concessions to a complete exit
Earlier negotiations focused on a less sweeping arrangement. New World sought to waive at least part of the guaranteed rent while continuing to share some annual revenue from the mall and office towers with the Airport Authority. A possible stake in the project for the authority was discussed as compensation for rent concessions.
The September agreement instead ends New World's role under the existing contracts. Its wholly owned subsidiary, Roxy Limited, will surrender the lease, and the authority will take full responsibility for business development and management. This is a transfer of the operating platform, rather than a temporary reduction in rent.
The original rental structure required New World to pay at least HK$1.8 billion annually or between 20% and 30% of gross project revenue, whichever was higher. A guaranteed minimum means the payment does not automatically fall when revenue disappoints. Leaving that arrangement removes a substantial fixed obligation.
The main dates show how far the project has moved from its original structure:
- 2018: New World won the development tender and began its partnership with the Airport Authority.
- September 30, 2026: The authority announced the termination agreement and takeover plan.
- April 1, 2027: The lease ends and the asset handover is scheduled.
- 2028/29 onward: The authority expects facilities to begin operating in phases alongside other SKYTOPIA projects.
- Late 2029: The reported three year share option reaches the end of its exercise window.
What New World must give up and pay
The official announcement identifies three office buildings and the entertainment hub as assets to be transferred at no cost to the Airport Authority. It also states that New World will pay more than HK$3 billion in cash and cash equivalents. The properties, the authority says, are already suitable for leasing.
Reports describe the payment package differently. One gives HK$2.3 billion in cash termination fees plus works and services worth up to approximately HK$1.05 billion. Another puts the free works and services at up to HK$1.1 billion. These descriptions are not identical to the authority's statement that more than HK$3 billion consists of cash and cash equivalents; they should not be treated as interchangeable or simply added together.
Reports also differ on the project's cost, citing HK$18 billion and HK$20 billion. The takeover announcement does not settle that difference. A detailed project description gives a total floor area of 3.8 million square feet, including 2.66 million square feet for retail and dining and 570,000 square feet for entertainment. Retail and dining therefore account for about 70% of the stated total.
New World is surrendering a substantial development, originally intended to operate under its K11 brand, to escape a lengthy financial commitment. The authority receives completed property and a payment package, but takes responsibility for securing operators, tenants and customers.
A large accounting loss, but a different cash picture
New World's reported termination loss was HK$18.32 billion, rounded to HK$18.3 billion in other accounts. The listed components include HK$14.7 billion in impairment losses and HK$2.3 billion in early termination costs. Those two components total HK$17 billion, less than the stated termination loss, so they are not a complete reconciliation.
An impairment reduces the value assigned to an asset in the accounts when the company no longer expects to recover its previous carrying value. It is not necessarily a cash payment made at the time the loss is recorded. Termination payments and obligations to supply works or services are separate matters and can affect cash or resources.
Another account describes approximately HK$18.3 billion as provisions associated with the exit. That broader wording differs from the breakdown identifying HK$14.7 billion specifically as impairment. The distinction matters when assessing how much of the headline loss reflects an accounting adjustment and how much represents an actual settlement cost.
The annual loss attributable to shareholders of HK$28.15 billion was about 73% larger than the previous year's HK$16.3 billion loss. Yet New World also reported HK$2.2 billion in core profit after excluding noncash losses, its first such profit in three years. Core profit and the statutory loss measure different things, and the positive figure does not cancel the company's debt obligations.
Chief executive Echo Huang said the 11 SKIES charges resolved a major issue and expected cash flow to improve substantially in the first half of fiscal 2026/27. That is a management expectation, not a completed reduction in debt.
The share option preserves the Cheng family's role
The reported equity arrangement comes from Chow Tai Fook Enterprises, rather than a direct issue of new shares by New World. The family investment company sold the Airport Authority a three year option for HK$1. Exercising it would require the authority to pay HK$2.25 billion for 750 million existing shares, equivalent to HK$3 per share.
The HK$1 price is the price of the option, not the price of the shares. The authority can choose whether to exercise its right. Because the shares would be purchased from Chow Tai Fook Enterprises, the exercise payment would go to that seller rather than directly into New World's cash reserves.
Reports put the stake at about 30% and describe the exercise price as roughly 43% below a recent market price. Another account compares it with a share price near HK$6, implying a discount of about 50%. Those percentages use different market reference prices; the stated HK$3 exercise price is consistent.
The shareholder conditions also require care. One account says Chow Tai Fook Enterprises must remain New World's largest shareholder after exercise. Another specifies that its holding must not fall below 30%. The official airport announcement does not set out the option terms, so these reported conditions should not be presented as identical.
The conditions could make changes to New World's capital structure necessary before exercise. UBS analysts, including Mark Leung, interpreted the exit as a possible signal of an equity transaction within three years. Cheng Wai Mo, research director at Mingze Capital International and a senior property analyst, suggested a rights issue could help preserve the family's required holding, while warning of dilution. Neither assessment amounts to an announced capital raising.
Debt pressure extends beyond the airport project
At the end of June 2026, New World had approximately HK$143.3 billion in total debt, HK$126.3 billion in net debt and a net gearing ratio of 68.3%. Net debt deducts cash from borrowings; gearing compares net debt with equity. Removing future airport rent payments helps liquidity, but does not directly repay those borrowings.
A reported maturity breakdown puts debt due for repayment or renewal within one year at HK$23.2 billion, with more than HK$40 billion due in each of the second and third years. Another account describes nearly US$11 billion falling due as early as the following year, without giving the same annual breakdown. That broader figure should not be confused with the specifically stated first year amount.
New World expanded its Deutsche Bank loan facility from HK$3.95 billion committed in June to HK$4.9 billion, an increase of HK$950 million. It also announced an exchange offer for approximately US$991 million in bonds due in 2027 and 2028. A bond exchange can change repayment terms or dates, but its effect depends on the terms and investor participation.
Reported resources included approximately HK$17 billion in cash and HK$16 billion in available bank facilities. Cash alone was below the HK$23.2 billion first year maturity figure. Adding available facilities gives a larger headline amount, but borrowing capacity is not the same as cash already held, and using it does not itself reduce debt.
Asset sales and new investment remain central
New World has pursued property sales and disposals alongside debt negotiations. In September it announced office property sales in Ningbo and Hangzhou worth more than 1.7 billion yuan. It also proposed placing Shanghai K11 Art Mall and Shanghai K11 ATELIER New World Tower into a real estate investment trust for listing in Shanghai.
Accounts describe the Shanghai transaction at different stages. One estimates proceeds of 3.2 billion yuan; a later account refers to a 3.24 billion yuan asset spin off preceding the bond exchange announcement. An estimated fundraising amount and a reported transaction figure should not automatically be counted as separate cash receipts.
The company's stated debt reduction measures include faster property sales, asset disposals, realizing value from agricultural land, improving rental income, controlling spending, suspending dividends, deferring distributions on perpetual securities and managing treasury operations prudently. Selling income producing property can raise cash, but also reduces the assets generating future rent.
Potential outside investment remains unresolved. The Cheng family reportedly discussed an investment with Bain Capital. Earlier talks with Blackstone over a US$4 billion arrangement ended after the family declined to give up control. No completed investment from either firm is established.
Brock Silvers, managing director at Kaiyuan Capital, distinguished the family's efforts to repair the company from committing further personal funds:
The Cheng family has been working assiduously to repair New World's finances but has yet to put any of its additional private capital at risk," said Silvers. "That may soon change.
The authority plans entertainment rather than a conventional mall
The Airport Authority intends to reposition 11 SKIES as the central entertainment hub of SKYTOPIA, its wider airport city development. Chairman Fred Lam said the project would not be another traditional shopping centre. He pointed to its scale as suitable for large entertainment and experience facilities that typical indoor venues in Hong Kong cannot accommodate.
Chief executive Vivian Cheung said the authority would establish a dedicated subsidiary and professional team, seeking entertainment operators and commercial partners internationally. The authority says the buildings are suitable for leasing, but the intended mix of attractions, dining, retail and operators has yet to be finalized.
The wider SKYTOPIA plan includes a 20,000 seat performance venue at AsiaWorld Expo, a marina with approximately 500 berths, water recreation, art exhibition and storage facilities, a waterfront promenade and an automated transport system linking the area with the Hong Kong Port of the Hong Kong–Zhuhai–Macao Bridge and Tung Chung MTR station.
The authority expects the entertainment project to open in phases from 2028/29. A government response also refers to the Terminal 2 Concourse and other major SKYTOPIA projects opening progressively from 2028. Neither timetable establishes a single opening date for every part of 11 SKIES.
The commercial objective is to turn airport and bridge passenger traffic into spending on entertainment and other services. Lam also described the project as a potential platform for mainland companies reaching international customers and international businesses seeking mainland customers. These are stated ambitions, not evidence of secured demand.
Support buys time, without settling the company's future
The government's response said the agreement gives the project a clear direction and allows the authority to reconsider its positioning, themes, industry mix and operating model. It expects the April handover to be followed by replanning and operation coordinated with the wider airport development.
For New World, the support carries broader economic significance. The group reportedly holds about 2.5 million square feet of development land and 12.4 million square feet of agricultural land, much of the latter in the Northern Metropolis. That agricultural land is estimated to have potential for nearly 7,000 homes, but development and cash recovery take time.
Gary Ng, senior economist at Natixis, connected the agreement with New World's place in Hong Kong's economy and the government's northern development plans. He also warned about the consequences of renewed financial stress:
Further financial pressure on New World could increase restructuring or default risks.
The agreement is therefore better understood as relief from one major obligation than a complete rescue of the balance sheet. The authority receives assets and payments rather than simply transferring cash to the developer. The share option is discretionary, and buying existing family shares would not itself inject capital into New World.
The next firm milestone is April 1, 2027. Beyond that, the unresolved matters include the entertainment hub's final operating plan, its tenants and operators, any new equity transaction, and whether the Airport Authority exercises its option. New World still needs to manage its debt maturities while protecting enough recurring income to service its borrowings.
Key Points
- The Airport Authority announced the 11 SKIES takeover agreement on September 30, 2026.
- Three office towers and the entertainment complex will transfer without an asset purchase payment.
- The lease ends on April 1, 2027, removing guaranteed annual rent of at least HK$1.8 billion.
- The authority says New World will provide more than HK$3 billion in cash and cash equivalents; reports describe the settlement package differently.
- New World recorded a termination loss of about HK$18.3 billion and an annual shareholder loss of HK$28.15 billion.
- A reported three year option allows the authority to buy 750 million family owned shares for HK$2.25 billion, subject to shareholder conditions.
- New World's total debt remained approximately HK$143.3 billion at June 2026.
- The authority plans phased entertainment operations from 2028/29 as part of SKYTOPIA.