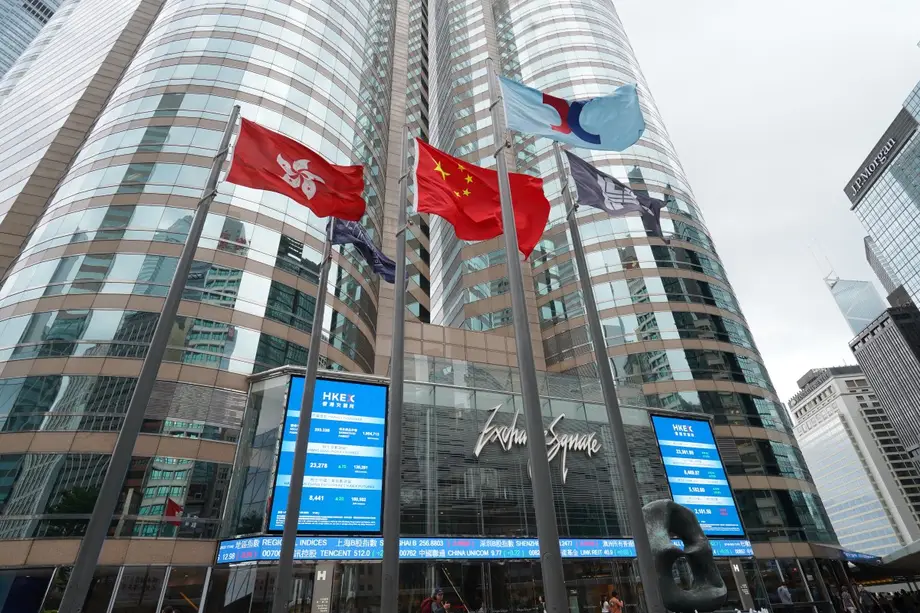
A wider gauge of Hong Kong technology shares
Hong Kong's Hang Seng Tech Index will grow from 30 stocks to 50 for the first time since it was launched, adding companies including battery maker CATL, electronics supplier Luxshare Precision and optical equipment maker Zhongji Innolight. The changes were announced on Nov. 20 and are due to take effect on Dec. 7, after the market closes on Dec. 4.
Contents
- A wider gauge of Hong Kong technology shares
- What changes in the index rules?
- More changes across Hong Kong benchmarks
- Market declines put the reshuffle in a tense setting
- Investors move money as uncertainty rises
- Buybacks and investment plans continue in China
- AI investment is shifting toward business results
- What to Know
The additions bring more manufacturers and hardware businesses into a benchmark long associated with major internet and consumer technology companies. The move comes as artificial intelligence investment is drawing attention to chips, data centers, optical components and robotics, alongside online platforms.
There will be 20 additions and no removals from the technology index. Other named entrants include Hesai, which makes lidar sensors, robotics company Ubtech, chip designer Shanghai Biren Technology, ASMPT, AAC Technologies, Kingboard Holdings, Innoscience, Kingsoft Cloud, Yangtze Optical Fibre and Cable, and GDS Holdings. The published lists also name FIT Hon Teng, while the full set of additions includes companies in advanced hardware and other technology fields.
CATL, one of the world's largest electric vehicle battery makers, is set to carry a 2.17% weight in the revised index. The 20 additions together will have a 4.15% weighting, meaning the existing members will continue to account for most of the benchmark when the changes take effect.
What changes in the index rules?
The index selection method has also shifted. Under the revised approach, 40 companies are selected by market value and 10 by sales growth. Earlier rules placed more limits on industry representation. Those restrictions have been removed, and the index's themes now include artificial intelligence, advanced hardware, robotics and other emerging technologies.
The rebalancing will reduce the share of consumer discretionary companies, a category that includes many businesses selling goods and services to consumers, from 49.70% to 45.56%. Tencent, Alibaba, Xiaomi, NetEase and Meituan will each be capped at 8% of the index. A cap limits how much one company can influence the benchmark, even if its market value would otherwise give it a larger share.
That design creates a wider snapshot of the technology sector without allowing the biggest companies to dominate the index. The additions also give investors using index funds or other products tied to the benchmark exposure to more manufacturers and hardware suppliers. The actual effect on any one fund will depend on how it tracks the index and when it adjusts its holdings.
More changes across Hong Kong benchmarks
The Hang Seng China Enterprises Index will add AI model developers MiniMax and Zhipu, while removing Postal Savings Bank of China and apparel maker Shenzhou International. The index will remain at 50 members. MiniMax is expected to have a 0.23% weighting and Zhipu 0.32% when the changes take effect.
The Hang Seng Index, Hong Kong's main blue chip benchmark, will remain unchanged at 95 constituents. HSBC, Alibaba and Tencent will each be capped at 8% in the index. The review therefore leaves the main benchmark's membership intact while making a larger change to the technology index.
The broader Hang Seng Composite Index will expand from 580 companies to 585. New members include Luxshare Precision, Zhongji Innolight, Joyson Technology, Momenta and Nazhen Technology. The composite index is also used as a key measure for whether Hong Kong listed shares can qualify for mainland China's Stock Connect trading link.
A separate change to the Hang Seng Biotech Index is scheduled to take effect on Dec. 14. Its constituent list was not changed in the review described here.
- Sept. 30: The review's reference date for assessing index constituents.
- Nov. 20: Hang Seng Indexes Company announces the quarterly review results.
- Dec. 4, after market close: Most constituent changes are due to be implemented.
- Dec. 7: Changes to the Hang Seng, China Enterprises, Tech and Composite indexes take effect.
- Dec. 14: The biotech index adjustment takes effect.
Market declines put the reshuffle in a tense setting
The announcement arrived during a broad market pullback. On the day, the Hang Seng Index fell 1.89%, while the Hang Seng Tech Index dropped 3.78%, extending its decline to an eighth consecutive trading session. NetEase fell more than 17% and Kuaishou lost more than 11%. Alibaba rose 3.48% after its earnings report.
In mainland China, shares also weakened, though large index funds saw heavy late buying. Six broad market exchange traded funds each recorded closing turnover above 10 billion yuan. The ChinaAMC SSE 50 ETF traded more than 24.3 billion yuan, a record, while the SSE 50 Index gained 0.45%. Banks, oil, power and coal companies were among the stronger large companies, and several bank shares reached record highs.
Technology shares were among the weaker areas in mainland markets. Semiconductor, computing power and optical communications stocks fell. Zhongji Innolight lost more than 3% on turnover of 14.941 billion yuan, while optical component maker Tianfu Communication fell more than 6%. That day's weakness contrasts with the longer term index decision to increase the representation of hardware and AI related companies.
Across Asia, South Korea's Kospi fell 5.21% and Japan's Nikkei 225 dropped 5.06%. The three major US stock indexes had also fallen overnight, with the S&P 500 recording a sixth straight decline. Before the US market opened, the VIX volatility index briefly reached 30.04, its highest level in nearly eight months. US futures were broadly lower, and several technology and chip related shares fell.
Investors move money as uncertainty rises
Despite the Hong Kong share declines, mainland investors bought Hong Kong shares through the Southbound Stock Connect channel. Net purchases exceeded HK$11.8 billion, the first time since Nov. 3 that the daily total had topped HK$10 billion. Stock Connect allows eligible mainland investors to trade selected Hong Kong shares through mainland exchanges.
Gold also came under pressure as the US dollar strengthened. International gold prices fell sharply and were down more than 8% for the week. Industrial and financial institutions issued warnings about precious metals and market risks, including Industrial and Commercial Bank of China, China Merchants Bank, China Construction Bank, Bank of Ningbo and the Shanghai Futures Exchange.
Uncertainty in the Middle East was another part of the market backdrop. A Saudi led coalition said it had intercepted missiles and drones launched toward Saudi Arabia by Yemen's Houthi movement. Saudi Arabia said an attack damaged a building belonging to its Public Investment Fund in Riyadh. A US Defense Department official said the United States had spent US$48.3 billion on the conflict with Iran as of Nov. 13, excluding damage from attacks on US military bases in the Middle East.
Buybacks and investment plans continue in China
Several mainland listed companies announced plans to buy back shares or increase holdings as prices weakened. The controlling shareholder of Rongsheng Petrochemical plans to buy between 1 billion and 2 billion yuan of shares. Tongwei plans a buyback of 1 billion to 2 billion yuan, and Huaqin Technology plans one worth 600 million to 1 billion yuan.
The controlling shareholder of Goke Microelectronics proposed a buyback of 250 million to 500 million yuan, with the shares to be cancelled. More than 40 other companies disclosed related plans. A buyback removes shares from the market, while an increase in holdings means an existing shareholder purchases more shares.
Luxshare Precision's controlling shareholder proposed that the company return at least 1.5 billion yuan to shareholders each year from 2026 through 2028. The annual amount would also be no less than 30% of net profit attributable to shareholders, with the higher of those two measures applying.
Some companies described expansion plans linked to technology demand. Tengjing Technology said orders were rising for optical components used in high speed data center links, optical switching equipment and tunable lasers, as well as optical products for semiconductor equipment. Mulinsen plans to build a semiconductor chip testing and packaging project in Ji'an, Jiangxi, with a total investment of 2.25 billion yuan and a target completion date at the end of 2028.
Silan Microelectronics plans to redirect 1.6 billion yuan of raised funds toward buying a 20.344% stake in Silan Jike and injecting another 500 million yuan into the business. The money is intended to support expanded production of IGBT power devices and analog circuit chips. IGBT chips are power control components used in equipment such as electric vehicles and industrial systems.
AI investment is shifting toward business results
Market views included caution about rising uncertainty near year end and possible repricing of assets in China and overseas. One investment strategy focused on dividend paying shares, consumer companies and Chinese AI businesses. Another argued that attention in AI investing may move from building infrastructure toward whether applications and products can generate commercial returns.
That view also points to physical AI, such as robots that interact with the real world, and on device AI, where computing happens on a phone or other local device. The Hang Seng Tech changes reflect a similar widening of what counts as technology exposure, from online platforms toward batteries, optical networks, chips and robotics. The revised index will take effect in December, while the commercial performance of the newly included companies will continue to depend on their orders, sales and earnings.
What to Know
- The Hang Seng Tech Index will expand from 30 stocks to 50 for the first time, with 20 additions and no removals.
- CATL, Luxshare Precision, Zhongji Innolight, Hesai and Ubtech are among the named additions.
- The new method selects 40 members by market value and 10 by sales growth; major platform companies are capped at 8% each.
- The Hang Seng Index stays at 95 members, while the Hang Seng China Enterprises Index adds MiniMax and Zhipu and remains at 50.
- Most changes take effect Dec. 7, following implementation after the Dec. 4 close. The biotech index adjustment takes effect Dec. 14.
- The review was announced during a broad Asian and US market decline, even as Southbound investors made more than HK$11.8 billion in net purchases.