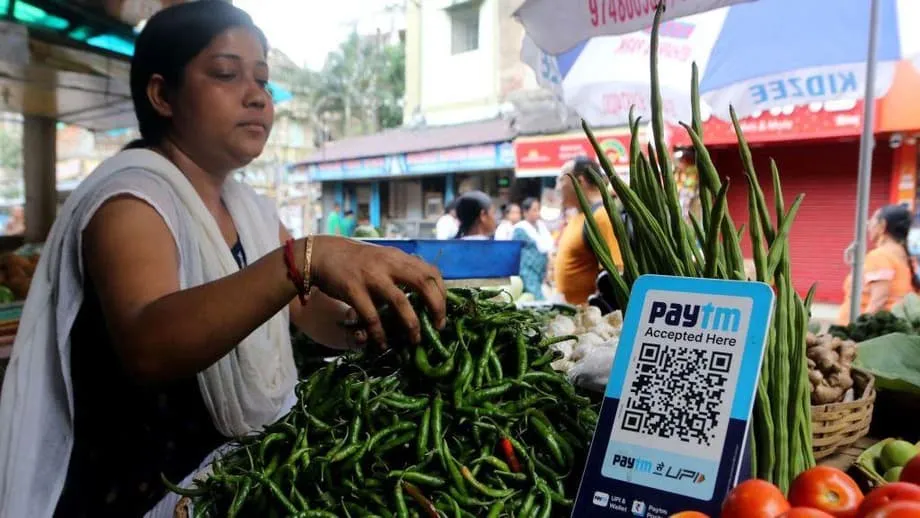
A 0.4% charge puts larger UPI purchases in focus
India will introduce a Merchant Discount Rate of 0.4% on specified Unified Payments Interface merchant payments above 2,000 rupees from 15 October 2026. The charge, capped at 300 rupees per transaction, will be paid by businesses using a network that hundreds of millions of people have come to know as free and instant.
Contents
- A 0.4% charge puts larger UPI purchases in focus
- How the fee and its cap will work
- Which payments will stay free?
- Why the network is seeking a new source of income
- Retailers fear the festive season will favour cash
- Fuel dealers ask for a full exemption
- Investment transfers can create costs without a trade
- The government defends merchant funding
- Political criticism focuses on prices
- Record payment volumes raise the stakes
- October will bring the first practical test
- The Bottom Line
The government says roughly 96% of payments from customers to merchants will remain unaffected. Transfers between individuals will stay free regardless of their size, while smaller purchases and merchants protected by existing zero fee arrangements will also be exempt. Customers will not be charged directly, and businesses will not be permitted to add the fee to their bills.
The change nevertheless reaches purchases that matter to retailers, fuel dealers and investment platforms. It is scheduled to start shortly before Diwali, when spending on clothing, electronics, jewellery and household goods often takes individual purchases above the 2,000 rupee threshold.
Payment companies argue that the network needs a dependable source of income to maintain its infrastructure and security. Retailers fear that even a modest charge could squeeze profits and encourage cash payments. Investment businesses face another concern: money entering a customer account may generate a processing bill before it produces any business income.
As of 17 September 2026, the debate centres on how to fund India's digital payments network while keeping it affordable. The government describes the fee as payment for processing services, rather than a tax. Businesses are questioning whether the proposed rates fit the way they earn money.
How the fee and its cap will work
The Merchant Discount Rate, usually shortened to MDR, is the fee a business pays for processing a customer's digital payment. Under the new arrangement, the money will be shared among banks, payment service providers, merchant acquiring companies and the National Payments Corporation of India, which operates UPI. Merchant acquiring companies help businesses accept and process payments.
The standard rate is 40 basis points, set by the UPI Steering Committee. A basis point is one hundredth of a percentage point, so 40 basis points means 0.4%, or four rupees for every 1,000 rupees paid.
A payment of 10,000 rupees subject to that rate would cost the merchant 40 rupees. Applying the same calculation to 2,000 rupees gives about eight rupees, although merchant payments of exactly 2,000 rupees remain within the free threshold. The standard charge applies to specified payments above that amount.
The 300 rupee cap is reached at a transaction value of 75,000 rupees. Larger payments subject to the standard rate would still carry a maximum fee of 300 rupees. The cap limits the expense of an individual large payment, while a business processing many qualifying payments would face the charge repeatedly.
Which payments will stay free?
Person to person transfers will remain free at any amount. Merchant payments of up to 2,000 rupees will also stay free, along with payments covered by the zero MDR framework for small merchants. The government's estimate that 96% of customer payments to merchants will be unaffected includes both purchases below the threshold and transactions involving protected merchants.
QR code payments to small merchants in rural and semi urban areas will not attract the charge. NPCI's definition of small merchants under the new framework is reported to cover businesses receiving up to 1 lakh rupees a month through UPI QR codes. One lakh is 100,000 rupees.
Fuel, railway, telecom, insurance and agricultural input payments above 2,000 rupees will face a flat charge of five rupees instead of the standard percentage. A flat fee stays the same as the payment grows, unlike a percentage charge that rises until it reaches its cap.
Capital market transactions are reported to carry a much lower rate of 0.02%, reflecting the high value of many payments in that category. That rate is one twentieth of the standard 0.4% charge. The different treatment of these sectors is central to the debate because the amount transferred and the income earned from it can be very different.
Why the network is seeking a new source of income
UPI launched in 2016 and became a routine way to pay at street stalls, in taxis, at supermarkets and hospitals, and through online businesses. Customers scan a QR code or select a contact in a mobile app, and money moves almost instantly between bank accounts.
Digital payments also give businesses records that are easier to track and reconcile than cash sales. Reconciling means checking that incoming payments match the sales recorded by the business. That has helped bring more transactions into the formal economy, where commercial activity is recorded.
Banks, technology companies and the government have carried much of the cost of maintaining and expanding UPI. Public funds have supported incentives encouraging banks and payment companies to keep small UPI payments free. A free payment for the customer still requires computer systems, processing and security behind it.
Officials say MDR will help make the network financially sustainable. The Finance Ministry says the revenue is expected to support payment infrastructure, reliability, innovation and cyber security. Industry estimates put the potential annual income for participants in the payments network at as much as 16,000 crore rupees, although the amount will depend on transaction volumes and exemptions. One crore is 10 million rupees, making that estimate 160 billion rupees.
Retailers fear the festive season will favour cash
Retail groups say a fee calculated on the full purchase price can be difficult for businesses with narrow profit margins. A high value sale may produce only a small profit, but the processing charge is based on the amount the customer pays.
Kumar Rajagopalan, chief executive of the Retailers Association of India, said attaching a fee to larger digital purchases could weaken years of progress in payment adoption. He pointed to the volume of purchases above the threshold during the festive season.
During the festive season, a large share of transactions crosses the 2,000 rupees mark, and the moment a fee attaches itself to digital payment, cash becomes the path of least resistance.
Retailers are concerned that the 15 October start will come shortly before Diwali, one of India's busiest shopping periods. Clothing, electronics, jewellery and household purchases frequently exceed 2,000 rupees, leaving merchants facing charges across a large number of sales.
Some traders say they may ask customers to use cash for larger purchases. Others could restrict UPI acceptance or adjust prices indirectly, despite the prohibition on adding MDR as a separate charge. Smaller businesses with limited access to credit and little room to absorb expenses are especially exposed.
Cash avoids digital payment processing fees but brings costs and risks of its own. Businesses must handle and safeguard it, face the possibility of theft, and work with weaker transaction records. Merchants weighing the new charge will therefore be choosing between different sets of expenses, rather than between a costly system and one with no costs.
Fuel dealers ask for a full exemption
The All India Petroleum Dealers Association has asked the Union Finance Minister to remove MDR from all UPI payments at fuel outlets, regardless of transaction size. Fuel dealers have made one of the strongest sectoral objections even though qualifying fuel payments are due to attract the lower, flat five rupee charge.
Dealers say their earnings are based on fixed margins per litre rather than a percentage of the total sale. They argue that a larger payment increases the transaction value without providing a proportionate increase in profit available to absorb a processing charge.
The association says dealer commissions have not been revised since October 2017, while electricity, wages and compliance costs have risen. Even five rupees per qualifying transaction could become a substantial recurring expense at outlets processing thousands of digital payments each day. A charge of 0.4% would be more costly still.
Dealers have requested either a complete exemption or a specific exemption for fuel payments above 2,000 rupees. Their argument is that customers receive the same fuel whether they pay in cash, by card or through UPI, so the chosen payment method should not reduce the dealer's fixed margin.
Investment transfers can create costs without a trade
Online brokers, mutual fund platforms and investment advisers face a different problem. A customer transferring money into an investment account may not immediately buy anything or create an activity from which the business earns a fee.
An investor could send 1 lakh rupees to a brokerage account and leave it unused. At the reported capital market rate of 0.02%, that transfer would generate a charge of 20 rupees. If that rate or another applicable MDR must be paid, the brokerage incurs a cost without receiving a commission from a trade.
Nithin Kamath, founder of Zerodha, has argued that transfers into a customer's own brokerage account resemble person to person payments more than ordinary merchant purchases. The customer is moving money into an account for possible investment, rather than paying the broker for goods or services at that moment.
Kamath has also pointed to regulatory rules requiring brokers to return unused client funds at regular intervals. A customer may then send the returned money back through UPI, creating repeated processing costs without generating new business.
Deepak Shenoy, founder of CapitalMind, has warned that percentage fees could be particularly difficult for low cost mutual funds. A fund's annual expense ratio is the share of an investment charged each year to cover its costs. When that ratio is very small and the investment is held briefly, the payment charge could exceed the income the fund earns from it.
Industry representatives have suggested a smaller percentage with a low cap, or a fixed charge of two rupees or less for investment transactions. They say those approaches would give payment providers some income while protecting products that earn little from each investment.
The government defends merchant funding
The Finance Ministry says UPI will remain free for consumers and that MDR will cover only a limited portion of merchant transactions. Businesses will not be allowed to pass the charge directly to customers. The ministry has also rejected claims that foreign pressure drove the decision, saying India's policy is being set independently to build a sustainable, inclusive and affordable digital payments network.
Supporters argue that the current arrangement leaves taxpayers funding payment incentives for a service used by large companies as well as small shops. They favour a pricing model that places more of the expense on businesses benefiting from digital transactions.
Bipin Preet Singh, chief executive of MobiKwik, said moving from public subsidies to charges linked to business use would reduce the burden on taxpayers.
When government funds the subsidies paid for UPI, that amount comes from taxpayers' pocket. Moving to a market linked pricing mechanism removes this tax burden and directly links the cost to large businesses which benefit from UPI.
Political criticism focuses on prices
Congress leader Rahul Gandhi has argued that merchants may eventually recover the expense through higher prices, even when customers pay no separate UPI fee. His criticism focuses on the difference between who receives the processing bill and who may ultimately bear the cost of a purchase.
Gandhi has also pointed to the difference between the number and value of transactions. Larger payments account for a small share of all transactions but a much greater share of the money moving through UPI. His argument is that charges on a limited group of payments could still affect prices in important sectors.
The government disputes that interpretation and says the fee applies to merchants, not ordinary users. It has also said the policy was considered years ago and will not be withdrawn. The disagreement extends to whether digital payment infrastructure should be funded as a public service, a commercial network or a combination of the two.
Record payment volumes raise the stakes
UPI processed a record 24.51 billion transactions worth 29.82 trillion rupees in August, according to NPCI data. That scale explains why a small percentage charge has drawn attention across retailing, fuel sales and investment services.
Most payments are small and will remain free. Larger merchant payments carry considerable financial value, however, and percentage charges can become expensive for businesses that previously negotiated flat fees under traditional payment arrangements.
Businesses and customers may change how they move money. Customers could split purchases into smaller payments to stay below the threshold. Merchants could encourage bank transfers or cash, while investment platforms could direct users towards net banking or recurring payment mandates, which authorise repeated payments.
Payment providers say reliable networks, fraud monitoring and cyber security require continuing spending. Retailers counter that wider adoption has already benefited banks, platforms and the government, while smaller businesses are being asked to fund the next stage of expansion.
October will bring the first practical test
The fee's effect on prices, payment choices and business costs is not yet known. The first practical test will arrive during the festive shopping period, when affected businesses must decide whether to absorb the expense, change payment practices or continue seeking exemptions.
The key dates connect UPI's expansion with the concerns now being raised:
- 2016: UPI launched and began its growth into a routine payment method.
- October 2017: The last revision to fuel dealer commissions, according to the petroleum dealers' association.
- August 2026: NPCI recorded 24.51 billion UPI transactions worth 29.82 trillion rupees.
- 17 September 2026: Retailers, fuel dealers and investment businesses are challenging aspects of the planned charges.
- 15 October 2026: MDR is scheduled to begin on specified merchant payments above 2,000 rupees, shortly before Diwali.
Industry groups are expected to press for rules reflecting business margins and the purpose of each payment. A flat charge may suit fuel and insurance, while investment platforms may seek a lower cap. Keeping customers free from direct charges will depend on enforcement, while broader price changes will depend on business decisions.
UPI is unlikely to lose its central role because most everyday transactions will remain free. The new fee could still change how larger purchases are paid for and how the network is funded. The test is whether it raises enough revenue to support reliable services without encouraging a return to cash.
The Bottom Line
- A 0.4% MDR is scheduled to apply from 15 October 2026 to specified UPI merchant payments above 2,000 rupees.
- The standard fee is capped at 300 rupees per transaction, reached at 75,000 rupees.
- Businesses will pay the fee and cannot add it directly to customer bills.
- Person to person transfers, merchant payments up to 2,000 rupees and protected small merchant payments will remain free.
- The government says roughly 96% of customer payments to merchants will be unaffected.
- Qualifying fuel, railway, telecom, insurance and agricultural input payments will attract a flat five rupee charge.
- Capital market payments are reported to carry a 0.02% rate, with investment businesses seeking lower or fixed charges.
- Retailers fear pressure on margins and a shift to cash; fuel dealers are seeking exemptions.
- The government says the revenue will support infrastructure, reliability, innovation and cyber security.