New mineral access, familiar transport risks
South Korea and Mongolia signed a Comprehensive Economic Partnership Agreement on July 11, removing tariffs of between 2 and 5 percent on Mongolian copper, molybdenum and rare earth imports. The deal gives Seoul a route toward new supplies of materials needed for electric vehicles, semiconductors, drones, robotics and military equipment. Getting those materials to buyers, however, will depend heavily on Mongolia's two powerful neighbors.
Contents
- New mineral access, familiar transport risks
- Why small quantities of rare earths matter
- Mongolia's mineral wealth needs closer measurement
- Processing at home could change the trade
- Border access can decide whether projects work
- Seoul's plans connect with American manufacturing
- Mongolia seeks partners without choosing sides
- Uranium shows the challenges beyond finding deposits
- What must happen before supply becomes reliable?
- The Bottom Line
Mongolia has no coastline, and up to 90 percent of its exports, including minerals, must travel through Chinese or Russian rail networks and ports to reach global markets. South Korea is seeking to reduce its dependence on Chinese mineral supplies, yet its prospective Mongolian suppliers rely on transport routes through China and Russia.
A joint research center operating since December is studying Mongolia's deposits and possible export routes. Its work addresses two practical questions: which resources can support commercial production, and how the resulting materials can reach South Korea reliably.
Seoul currently chairs a coalition of 17 nations launched by Washington to diversify access to critical minerals. Its agreement with Mongolia has a commercial purpose, while also connecting mineral trade to the security relationship between South Korea and the United States.
Mongolia is trying to attract investment and technology without upsetting its relations with China and Russia. Its third neighbor policy seeks closer ties with countries beyond those two neighbors, including South Korea, the United States, Japan and European countries. Mineral cooperation could widen Mongolia's economic choices while exposing it to pressure over where its exports ultimately go.
Why small quantities of rare earths matter
Rare earth elements are a group of 17 metals. Their name can be misleading: the main difficulty is finding deposits with enough of the elements concentrated together, then separating them from the surrounding rock. Processing requires complex technology, large amounts of energy and strict controls on waste.
Small quantities are essential ingredients in powerful permanent magnets. Those magnets help electric vehicle motors operate efficiently and are used in wind turbines, computer equipment, precision machinery, aircraft, missiles, fighter jets and drones. Other critical minerals have different jobs: copper, tungsten and molybdenum are used in power systems, aerospace equipment, tools and defense production.
China accounts for about 59 percent of global rare earth mining and roughly 90 percent of refining and processing capacity. It also produces most of the permanent magnets containing neodymium and dysprosium, two rare earth elements used in motors and other advanced equipment that demand strong performance.
The gap between China's mining share and its processing share explains why finding a new deposit is only part of the task. Ore must pass through several industrial steps before its valuable elements can become materials suitable for manufacturing. A country can obtain ore elsewhere and still depend on Chinese processing capacity.
The United States imported about 70 percent of its rare earth compounds and metals from China between 2020 and 2023, according to U.S. Geological Survey data. That reliance has made mineral supply a security concern as well as a trade issue, particularly when the same materials serve civilian factories and defense production.
Mongolia's mineral wealth needs closer measurement
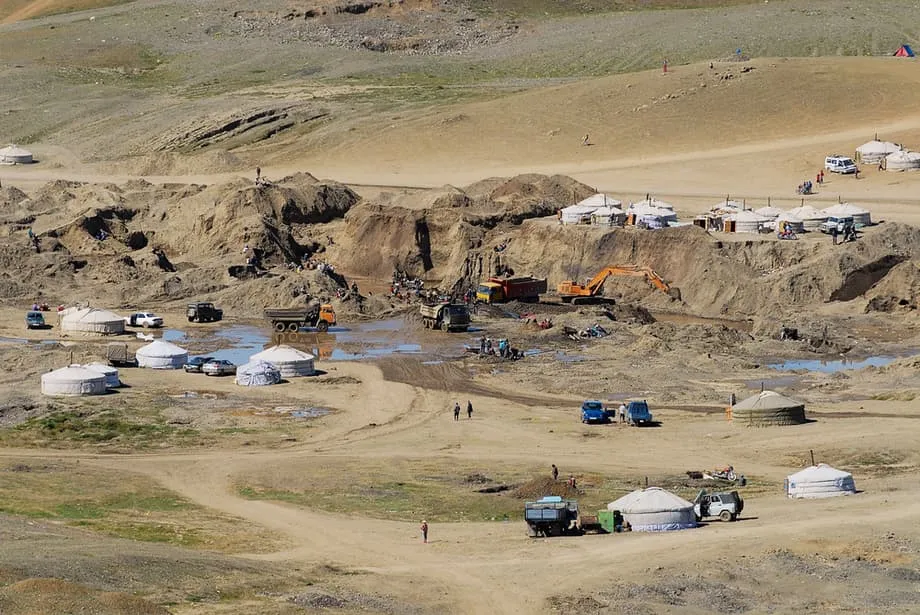
Mongolia has more than 80 identified types of minerals, including copper, gold, uranium and rare earth elements. Existing survey estimates place it among the world's top ten countries for mineral resources. Its six registered rare earth deposits and 26 known occurrence sites give South Korea several places to investigate.
One estimate puts Mongolia's rare earth reserves at about 31 million tons, around 16 percent of the world total. The country also has estimated copper reserves of 55 million tons and coal reserves of 175 billion tons. Oyu Tolgoi, in the southern Gobi region, is among the world's largest copper and gold operations.
Mongolia is roughly 16 times larger than South Korea, but about 55 percent of its territory has not been explored in detail. Better geological surveys may change the reserve estimates. Commercial decisions will also depend on whether deposits contain materials that can be extracted and processed at a workable cost.
Mining already supplies a large share of Mongolia's economic activity. In 2024, it accounted for about 27 percent of gross domestic product, 70.9 percent of industrial output and 87.2 percent of exports. Those figures show how much the country depends on mining, especially for sales abroad.
The Mongolian government wants new projects to attract investment and reduce dependence on coal and sales of raw materials. The aim is to earn more from its resources by carrying out more industrial work at home, rather than relying mainly on extracting minerals and sending them elsewhere.
Processing at home could change the trade
Mongolian Ambassador Sukhee Sukhbold has called for South Korean technology and investment to be combined with Mongolia's mineral resources. His goal is joint production of materials with greater value, rather than simply increasing shipments of unprocessed ore. He explained Mongolia's current position and the change it wants:
We are exporting raw minerals to China and just selling them as they are. But the world needs more processed products. Why are we exporting raw materials only? We need to process them and produce the products the world needs.
Processing tungsten, molybdenum and rare earth materials in Mongolia could produce concentrates or intermediate products before export. Concentrates contain a greater proportion of the useful mineral than the original ore. Shipping them means moving less surrounding material, making transport more efficient while creating jobs and industrial skills in Mongolia.
South Korean specialists are studying whether processing plants can be built near Mongolian mines. Smaller volumes of finished materials could then travel by air. Air freight would be costly and would suit refined products better than large quantities of ore, making the level of processing central to the transport plan.
Professor Song Byeong Gu of Dankook University said a first shipment of Mongolian tungsten concentrate was flown to South Korea on June 27. That shipment provides a practical example of the air route under consideration.
Processing plants would still need reliable electricity, water, roads, skilled workers and environmental safeguards. Mongolia's severe winters, large distances and limited infrastructure can increase construction and operating costs. Equipment, fuel and some transport links would continue to depend on neighboring countries even with more processing inside Mongolia.
Border access can decide whether projects work
China and Russia control the rail networks and ports through which most Mongolian exports reach overseas markets. For South Korean businesses, access to a new mineral source therefore comes with dependence on transit arrangements beyond the control of either Seoul or Ulaanbaatar.
Professor Jang Jae Hyuk of Hankuk University of Foreign Studies described the border as a serious logistical bottleneck. He warned that Chinese authorities could use customs charges or delays to put pressure on shipments:
If China wanted to counter the United States, it could sharply raise customs costs or simply slow things down at the border.
South Korean experts warn that China or Russia could delay shipments, raise customs costs or impose administrative barriers if they concluded that Mongolian minerals were being redirected to the United States or Japan. A formal embargo would not be necessary to disrupt a business.
Longer waits at crossings, tighter inspections, changes in rail access and higher insurance costs could make a project commercially unviable. Companies relying on just one or two routes are especially exposed because they have few alternatives when a shipment is delayed or becomes more expensive.
Russia remains an essential transit partner for Mongolia, but routes through Russian territory bring their own political and commercial risks. Moscow's closer relationship with Beijing has also increased the importance of cooperation among Russia, China and Mongolia.
China has urged Russia and Mongolia to strengthen energy, financial and infrastructure ties and resist what Chinese President Xi Jinping described as external interference. Mongolia's effort to build mineral partnerships with more distant countries takes place alongside those demands for closer cooperation with its immediate neighbors.
Seoul's plans connect with American manufacturing
Some analysts see the South Korea Mongolia agreement as part of a wider arrangement involving Washington. In that possible supply chain, South Korea would import Mongolian minerals, process some of them at home and supply materials to American manufacturers under the expanding alliance between Seoul and Washington.
China could apply pressure through trade or transit channels if it believed Mongolian resources were being used to weaken its position or support American defense production. Russia could also object if it viewed the arrangement as part of a wider Western effort to reduce Russian influence in the region.
South Korea is already supporting projects intended to build processing capacity outside China. The United States has acquired a 10.59 percent stake in Korea Zinc, the world's largest zinc smelter. Korea Zinc and the American government are backing an estimated $7.4 billion integrated metals and critical minerals facility in Tennessee.
LS Cable and System is discussing a rare earth permanent magnet plant in Virginia. Posco International has partnered with ReElement Technologies on a separation and refining facility in Indiana. Together, these projects connect the search for new mineral supplies with processing and manufacturing facilities in the United States.
Seoul's interest in Mongolia therefore reaches beyond the purchase of ore. Its wider objective is a supply network extending from mines to usable industrial materials and final manufacturing. Transport, processing and access to customers must all work for that network to deliver dependable supplies.
Mongolia seeks partners without choosing sides
Mongolia's third neighbor policy is intended to widen its diplomatic and economic options while maintaining relations with China and Russia. Geography makes close ties with both unavoidable. China is Mongolia's largest trading partner and a major destination for mineral exports, while Russia remains important for fuel, transport and energy links.
South Korea became a strategic partner of Mongolia in 2021. Bilateral trade has grown from about $2.7 million when diplomatic relations began in 1990 to more than $600 million in recent years. Cooperation now includes mining, infrastructure, health care, tourism and education.
Korean development assistance has helped support that relationship. Korean groups have worked on medical facilities, water resources and urban infrastructure. A Korean consortium completed the basic design for Ulaanbaatar's first subway line, with construction expected to begin in 2026.
Ambassador Sukhee Sukhbold has said Mongolia seeks to communicate and trade with all partners rather than rank countries into fixed categories. Cooperation with Seoul offers access to technology and investment without requiring an exclusive political alignment. That approach will face pressure if mineral exports become directly connected to competition between China and the United States.
The main developments span several dates:
- 1990: South Korea and Mongolia established diplomatic relations. Bilateral trade was about $2.7 million.
- 2021: South Korea became a strategic partner of Mongolia.
- December: The joint research center studying Mongolian deposits and export routes began operating.
- June 27: A first shipment of Mongolian tungsten concentrate was flown to South Korea, according to Professor Song Byeong Gu.
- July 11: The two countries' presidents signed the Comprehensive Economic Partnership Agreement.
- 2026: Construction of Ulaanbaatar's first subway line is expected to begin.
- Around 2028: Production is targeted at the proposed Zuuvch Ovoo uranium development.
Uranium shows the challenges beyond finding deposits
Mongolia's effort to diversify mining also includes uranium, copper and other minerals sought by countries looking for new supplies for energy, manufacturing and technology. The experience of uranium projects shows why investment depends on regulations, public confidence and environmental protection as well as geology.
Mongolia has an estimated 190,000 tons of identified uranium resources, with possible total resources as high as 1.5 million tons. The proposed development of the Zuuvch Ovoo deposit with French company Orano is expected to require about $1.6 billion in investment. Production is targeted for around 2028.
Uranium development has moved slowly because of licensing disputes, changing laws and public concerns about water contamination, radioactive exposure and damage to grazing land. Rare earth investors will also need predictable rules, clear environmental standards and stronger public confidence to build a steady supply business.
Kazakhstan offers an example of how consistent policy and technical expertise can turn mineral reserves into sustained production. Mongolian authorities are studying that experience as they seek foreign capital while retaining a larger share of public revenue through a sovereign wealth fund.
What must happen before supply becomes reliable?
South Korea and Mongolia must turn their agreement into commercially workable projects. Geological surveys need to confirm that deposits are large enough and suitable for extraction. Governments and companies must then finance mines, processing plants, roads and power systems, while securing arrangements for crossing borders.
Environmental safeguards will help determine whether projects gain public support. Poorly managed rare earth processing can produce toxic waste, and mining may affect water supplies and grazing areas. Rural communities will expect transparent consultation and a fair share of the economic benefits.
Seoul must decide how much transport and political risk it is prepared to accept. Purchasing minerals from Mongolia can reduce direct dependence on Chinese supplies, while rail and port access remains controlled by China and Russia. Processing more material in Mongolia can reduce shipment volumes, but political exposure will remain part of the business.
Mongolia's central goal is industrial development that brings more value home than raw material exports alone. South Korea needs a promising mineral source connected to reliable processing and secure transport. Washington sees the partnership as one part of its wider effort to reduce China's influence over materials used throughout the modern economy.
The Bottom Line
- The July 11 agreement removes tariffs of between 2 and 5 percent on Mongolian copper, molybdenum and rare earth imports.
- Mongolia has six registered rare earth deposits and 26 known occurrence sites, while about 55 percent of its territory remains without detailed exploration.
- China accounts for about 59 percent of rare earth mining and roughly 90 percent of refining and processing capacity.
- Up to 90 percent of Mongolian exports must pass through Chinese or Russian rail networks and ports.
- South Korean specialists are studying processing plants near Mongolian mines and air shipment of smaller volumes of finished materials.
- Mongolia seeks investment through its third neighbor policy while preserving essential ties with China and Russia.
- Reliable transit, financing, predictable regulations and environmental safeguards will determine whether the partnership delivers lasting industrial production.