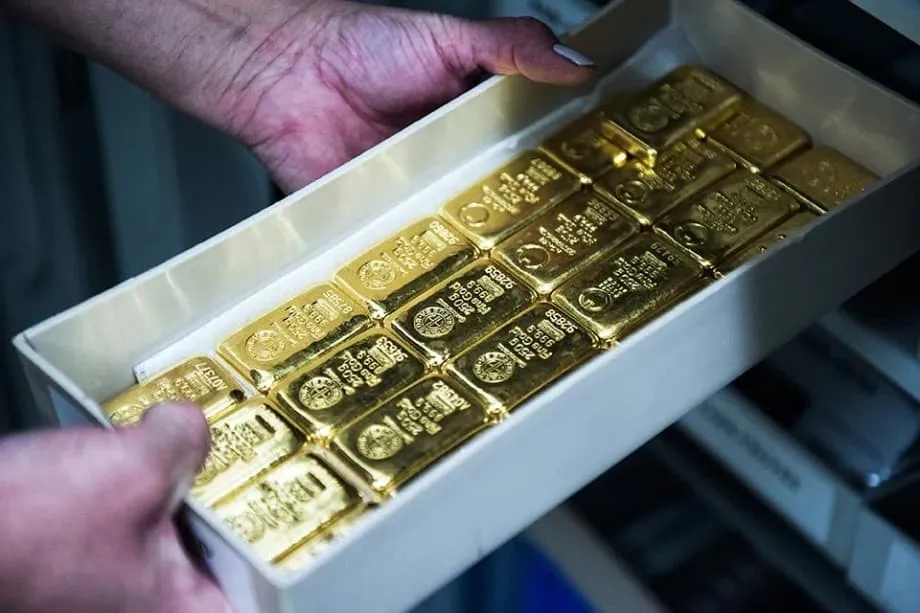
A July Launch Sets the Pace for Asia's Gold Contest
Hong Kong expects to launch a government operated gold clearing system by July 2026, putting a firm target behind its ambition to become Asia's leading bullion trading centre. As of May 28, Singapore is pursuing a similar clearing mechanism but has not publicly announced a launch date or a timetable for trials.
Contents
- A July Launch Sets the Pace for Asia's Gold Contest
- What Hong Kong's Clearing System Would Do
- Hong Kong Adds Vaults, Refining and Trading Staff
- Global Banks and Futures Are Central to Pricing Power
- Singapore's Vaults Draw Wealth Seeking Security
- Singapore Sets Out Four Areas for Development
- Competition Leaves Room for Cooperation
- London's Gold Stocks Remain a Major Advantage
- Private Wealth Adds Another Source of Demand
- Key Points
The competition brings together two different strengths. Hong Kong already channels large quantities of gold toward mainland China, the world's largest consumer of the metal, and has an established network of refiners and manufacturers. Singapore has at least 2,200 tonnes of storage capacity across two major private facilities and is seeking a larger role in safeguarding investors' and governments' bullion.
Both cities want to capture more business from strong global demand for gold and challenge London's longstanding position at the centre of bullion trading. Gold's prolonged rally has lost some momentum following the outbreak of war in the Middle East, although many banks remain positive about its longer term prospects. Investors seek the metal as an alternative store of wealth when geopolitical uncertainty rises.
Adrian Ash, head of research at BullionVault, an online platform for trading and storing precious metals, described the urgency behind Hong Kong's clearing plans.
If Hong Kong and Singapore are in a race to build clearing, it looks like Hong Kong authorities are very eager to win.
The July target is a practical milestone in a contest that extends beyond buying and selling metal. Each city is working to bring together storage, banking, logistics and financial products that could give Asia a greater role in setting gold prices. Their different strengths also leave room for both to grow.
What Hong Kong's Clearing System Would Do
A clearing system sits between buyers and sellers and guarantees settlement, meaning completion of the agreed exchange of money and gold. Its purpose is to reduce the danger that a trading partner fails to pay or deliver after a deal has been struck. That danger is known as counterparty risk.
Hong Kong plans to put this function under a government entity. Centralising settlement can give participants common transaction rules and a more predictable way to handle large bullion trades. For banks and other institutions moving substantial quantities of gold, confidence in settlement is a basic requirement for committing more business.
The expected July opening also coincides with a seasonal slowdown in gold demand. That quieter summer period is expected to give participants room to build stocks and test the infrastructure before busier trading conditions return. Hong Kong's existing flows of metal into mainland China offer a substantial base on which to build.
Liquidity, another central goal, means that buyers and sellers can find trading partners readily. A market with many participants and frequent transactions makes it easier to complete large deals and supports prices that others can use as a reference. Clearing is therefore a foundation for Hong Kong's ambitions, rather than the whole structure.
The main milestones announced or described by May 28 span the opening months of 2026 and the rest of the year:
- January 2026: The Monetary Authority of Singapore and the Singapore Bullion Market Association established a Gold Market Development Working Group.
- March and April 2026: Singapore's official trade data showed record gold imports from the United Arab Emirates as regional conflict prompted some metal to move out of Dubai.
- July 2026: Hong Kong expects to launch its government operated gold clearing system.
- During 2026: SF Holding plans to open a vault near Hong Kong's airport, and Point Gold International plans to begin operating a new production facility.
- During 2026: Singapore's monetary authority plans to share further details of its gold market initiatives.
Hong Kong Adds Vaults, Refining and Trading Staff
SF Holding, China's largest express delivery company, plans to open a vault near Hong Kong's airport this year. The investment would add storage alongside the transport connections needed to move bullion into and out of the city.
Point Gold International, a major Chinese refiner, says it is investing US$150 million to expand its Hong Kong offices and add a production facility scheduled to start operating this year. The city already has refiners including Heraeus and Metalor Precious Metals Hong Kong. Singapore, by comparison, has one refinery producing bullion with London Good Delivery accreditation, the industry standard cited for internationally accepted bullion.
Bernard Sin, regional director for Greater China at trader and refiner MKS PAMP SA, described the range of businesses already present in Hong Kong. MKS PAMP has recently expanded its own operations there.
Hong Kong has refineries, jewellery manufacturers, factories, mining companies. It's a gateway to North Asia: mainland China, Japan, Korea.
Hong Kong's government maintains roughly 150 tonnes of storage capacity at the airport. The total capacity of commercial vaults across the city has not been disclosed. Industry participants nevertheless expect private operators to expand quickly if the volume of transactions passing through the clearing system supports the cost of new facilities.
Precious metals traders are also commanding larger pay packages. Established banks are competing with financial technology firms and securities houses for experienced staff, reflecting confidence that more trading will follow the investment in infrastructure.
Matrixdock is among the digital newcomers looking to hire in the region. Chinese brokerages, including HGNH International Futures, are establishing dedicated precious metals trading teams in Hong Kong. The expansion links physical facilities with the people needed to price trades, manage risk and serve clients.
Global Banks and Futures Are Central to Pricing Power
JPMorgan Chase, UBS Group and Citigroup are supporting gold market development plans in both Hong Kong and Singapore. Local banks are participating in their home markets, while Chinese lenders have expanded their Hong Kong bullion desks or are adding to them as part of a push supported by the state to deepen liquidity.
Major bullion banks matter because a clearing system needs institutions willing to bring transactions into it. More vaults and production capacity can support the movement of metal, while banking participation helps turn those flows into a functioning financial market.
Hong Kong is also seeking the financial products needed to influence regional prices. A futures contract allows participants to agree a price now for a transaction at a later date. Miners, jewellers and institutional investors can use these contracts to protect themselves against price changes, a practice called hedging.
A jeweller in Shenzhen or a mining executive in Perth, for example, can plan around a price fixed six months in advance. That reduces exposure to movements in the spot market, where gold is traded for immediate settlement. Futures also attract speculative capital and help produce continuously updated prices that other participants can follow.
Hong Kong's large, active equity market and recent efforts to strengthen financial flows in both directions with mainland China give it an advantage in developing these products. Building futures alongside clearing is intended to draw institutional money into a market with enough activity to support dependable regional pricing.
Singapore's Vaults Draw Wealth Seeking Security
Singapore's most immediate advantage is the scale of its established private storage facilities. The Reserve can hold approximately 500 tonnes of gold, while Le Freeport has capacity for at least 1,700 tonnes. Together, those two heavily secured facilities provide at least 2,200 tonnes of capacity.
Le Freeport, sometimes described as Asia's Fort Knox, has seen demand for gold storage climb steadily in recent years. Its chief executive officer, Lincoln Ng, described the pressure on the facility's basement space.
The basement vaulting space, typically the preferred location for bullion storage due to enhanced security and higher load bearing capacity, is near full utilisation.
Singapore attracts owners who place a premium on political stability, a strong financial system and the rule of law. Its reputation as a secure place to preserve wealth is particularly appealing to some gold owners concerned about political influence over Hong Kong.
Regional military conflict has brought another flow of bullion. Singapore has taken custody of some gold moved out of Dubai, and official data showed record imports from the United Arab Emirates during March and April. Those movements connect Singapore's storage ambitions to the immediate decisions investors make when security conditions change.
The two cities' published capacity figures describe different parts of their storage markets: Singapore's figure covers two private facilities, while Hong Kong's roughly 150 tonnes refers to government storage at the airport. Hong Kong's wider commercial capacity remains undisclosed, making the scale of its private vault network an unanswered part of the competition.
Singapore Sets Out Four Areas for Development
The Monetary Authority of Singapore, known as MAS, established its Gold Market Development Working Group with the Singapore Bullion Market Association in January 2026. Its programme extends beyond storage to the financial and operational systems needed for a larger bullion market.
The working group has four main areas of work:
- Broaden financial market products related to gold.
- Establish a trusted clearing and settlement system.
- Strengthen standards for vaulting and logistics.
- Explore storage services for foreign central banks and sovereign entities.
MAS must also address the different bar sizes used in major markets. Large bars weighing roughly 12.4 kilograms are the preferred institutional format in London, while bars weighing one kilogram, known as kilobars, dominate Asian retail and wholesale markets. Connecting those markets requires a system that can handle both formats without costly conversion friction.
Chee Hong Tat, deputy chairman of MAS and Singapore's National Development Minister, compared the work to planting trees. He presented the investment as a way to build a durable market rather than a bet on short term gold price movements.
Over time, if you make the right investments in the right areas, you grow the ecosystem, the trees will then grow and bear fruit.
Singapore's strategy draws on its reputation for neutrality and regulatory quality. Safety and security are major considerations for central banks choosing where to keep gold, giving the city a basis for courting official institutions as well as private owners.
Competition Leaves Room for Cooperation
Chee has acknowledged Hong Kong's recent cooperation pact with the Shanghai Gold Exchange while rejecting the idea that only one Asian centre can succeed. The market segments each city serves are not completely identical, leaving space for both to expand.
Singapore's Prime Minister Lawrence Wong expressed a similar view during a recent official visit to Hong Kong. He said cooperation between the two financial centres would support growth and resilience in both places.
Doris Bao, founder of the China based consultancy Gold Harvest Management, expects the cities to develop different commercial roles.
Singapore is likely to focus on storage, whereas Hong Kong will promote trading and refining, supported by logistics.
Hong Kong's network connects refining, jewellery manufacturing, factories, mining company offices and transport services. Its access to mainland China, Japan and Korea gives those businesses nearby markets and trading relationships. Singapore's established vaults, meanwhile, appeal to wealth owners seeking political neutrality and discretion.
The proposed division of work would allow one centre to concentrate more heavily on the movement and transformation of gold, while the other builds on the safekeeping of bullion. Both still need financial services, and both are pursuing clearing, so their roles would overlap even if their strongest businesses differ.
London's Gold Stocks Remain a Major Advantage
London's position as the global gold hub rests on enormous stocks of bullion accumulated over centuries, much of it belonging to central banks around the world. Hong Kong and Singapore remain far behind that concentration of metal, even as both seek more business from official institutions.
Central banks have long kept at least part of their bullion in London for ease of management. Trading and lending activity helps create liquidity around those holdings. Gold lending puts stored metal into financial transactions, connecting custody with the wider bullion banking market.
China has prioritised countries participating in its Belt and Road Initiative when offering sovereign nations the option of storing gold on the mainland. Hong Kong is presented as a more flexible offshore location with relative ease of moving bullion into and out of mainland China.
Cambodia was among the first countries to accept China's offer to hold bullion on the mainland. The South African Reserve Bank has said it would consider keeping reserves in any optimal location. Such decisions point toward greater consideration of where national gold reserves are held and how they can be managed.
Adrian Ash, BullionVault's head of research, said the prospect of China challenging London's dominance has been discussed for well over a decade. He identified clearing as a necessary part of developing the banking services around bullion.
Clearing is a vital step towards building the bullion banking services which the No. 1 mining and consumer nation still lacks.
War, disrupted supply routes and sanctions that complicate settlement through Western banks can encourage market participants to seek alternative centres operating under different legal and political arrangements. Gold serves as an asset of last resort during war and inflation, making physical security and the ability to transact central concerns.
Hong Kong's developing infrastructure could eventually give Asian central banks additional channels for managing reserves and reduce reliance on Western custody services. Its common law framework offers contractual certainty and familiar dispute resolution arrangements to international traders. The Hong Kong dollar's peg to the US dollar also provides a fixed currency relationship for transactions using those currencies.
Private Wealth Adds Another Source of Demand
Hong Kong has recently overtaken Switzerland as the world's leading booking centre for wealth held across borders, managing roughly US$2.95 trillion in offshore assets, according to a 2026 study. A booking centre is the place where financial institutions hold and manage those assets for clients.
Private banking and precious metals investment are connected because wealthy clients may want both financial assets and gold. Hong Kong's position in offshore wealth therefore gives its bullion businesses access to an existing pool of potential customers.
Hong Kong and Singapore are both projected to grow as booking centres for wealth held across borders by roughly 9% annually through 2030. Switzerland's expected average is 6% over the same period, putting the projected annual growth rate for each Asian centre three percentage points higher.
Those projections cover wealth management, a broader business than gold. For bullion firms, proximity to the clients driving that growth could translate into demand for storage, trading and related banking services. Singapore's political neutrality and regulatory independence continue to attract investors concerned about geopolitical turbulence.
Gold also occupies several roles at once: it is an industrial commodity, an investment and a monetary reserve. Influence over its benchmark prices carries strategic value beyond trading profits. As central banks diversify their holdings and seek greater monetary independence, a credible Asian network for bullion could gradually reduce the concentration of activity in London.
Hong Kong's July clearing target gives it an early timetable advantage. Singapore's substantial vault capacity and broader development programme give it a different foundation. The contest will turn on whether these investments attract enough metal, banking activity and sustained trading to make both cities more useful to the people and institutions that own gold.
Key Points
- As of May 28, 2026, Hong Kong expects to launch a government operated gold clearing system by July.
- Singapore has announced plans for clearing but has not publicly set a launch or trial date.
- JPMorgan Chase, UBS Group and Citigroup support development plans in both cities.
- Hong Kong is adding storage, refining facilities and trading staff, including a US$150 million investment by Point Gold International.
- Singapore's The Reserve and Le Freeport together offer at least 2,200 tonnes of gold storage capacity.
- Singapore's working group covers financial products, settlement, storage standards and services for foreign official institutions.
- Hong Kong's trading and refining strengths and Singapore's custody business could support different roles within a larger Asian gold market.
- London remains the dominant bullion centre, supported by large gold stocks and established central bank business.