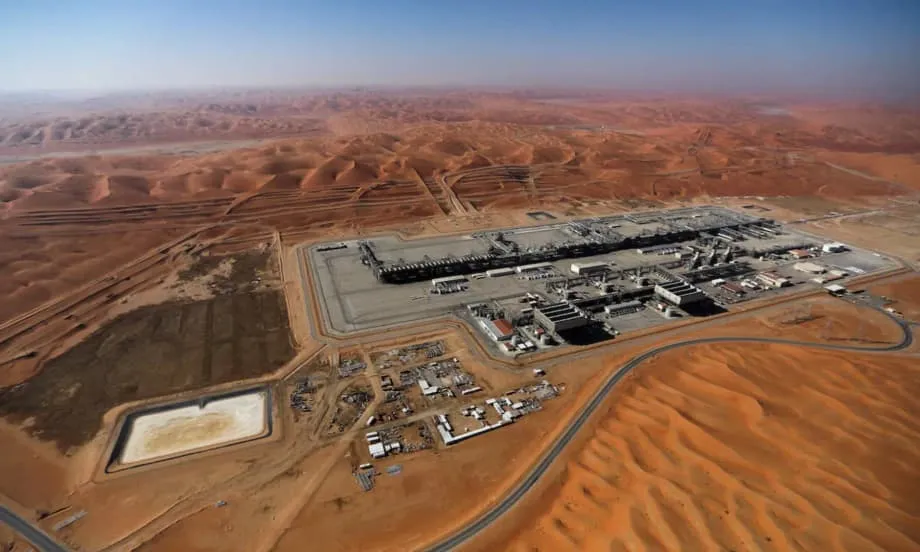
A narrow waterway puts Asian economies under pressure
Asia imported a record 25 million barrels of crude oil a day in 2025, including 14.74 million barrels from the Middle East. By March 11, 2026, that dependence had become an immediate economic threat: missiles and drones were targeting Persian Gulf oil facilities, the Strait of Hormuz was effectively blockaded, and Qatari liquefied natural gas production had halted.
Contents
- A narrow waterway puts Asian economies under pressure
- How much oil depends on the Gulf?
- Why replacement crude is difficult to use
- Japan and South Korea have large buffers, but heavy exposure
- India and Southeast Asia face tighter supply margins
- Qatar's shutdown brings a second energy squeeze
- Higher energy bills put currencies and budgets under strain
- How Asia reached another energy emergency
- Domestic electricity offers a different kind of protection
- Key Points
The conflict between Iran and a US-Israeli coalition had rapidly spread beyond military targets into the energy supply chains serving economies from Tokyo to Jakarta. Brent crude had climbed above $100 a barrel. Asian spot prices for liquefied natural gas, or LNG, had reached approximately $23.80 per million British thermal units, nearly twice their level a few weeks earlier. Analysts warned that oil could approach $150 a barrel if the conflict continued.
Asia buys more than four fifths of the crude produced in the Middle East, and 90 percent of those shipments pass through Hormuz. The narrow passage between Iran and the Arabian Peninsula carries roughly 20 percent of global oil and LNG shipments. More than 80 percent of the oil and LNG moving through it is destined for Asian markets.
Governments have responded with emergency task forces, fuel subsidies, shipping assistance and efforts to find replacement supplies. Their room to act varies sharply. Japan holds emergency oil reserves covering 254 days of consumption, while Vietnam has less than 20 days of petroleum cover. Refineries built around Middle Eastern crude and contracts covering much of their normal supply make a quick change of suppliers difficult.
The disruption is reaching Asia through several channels at once: fewer available cargoes, higher fuel prices, weaker currencies and rising public spending. Its effects can reach markets across the Pacific within days, even though tankers themselves take weeks to complete many of those journeys.
How much oil depends on the Gulf?
Shipping analytics firm Kpler's figures put Middle Eastern crude at nearly 60 percent of Asia's total imports in 2025. Saudi Arabia, the United Arab Emirates and Iraq were the main suppliers. Their cargoes generally take 30 to 40 days to reach North Asian ports, while voyages to India can take less than a week.
Japan gets approximately 95 percent of its crude from the Middle East. South Korea relies on the region for roughly 70 percent of its oil and 20 percent of its LNG. Those concentrations leave both economies heavily exposed when Gulf production or shipping is interrupted.
Singapore, a major oil trading, refining and refuelling hub, became more dependent on Middle Eastern crude in 2025. The region supplied more than 70 percent of its oil, compared with about 50 percent in 2024. The increase followed the completion of an Exxon Mobil refinery expansion that required heavy oil supplies.
China has a broader range of suppliers, including relationships with Russia, Iran and Canada, and produces more than 4 million barrels of oil a day domestically. Even so, about half of its imports arriving by sea come from the Middle East, equivalent to 5.4 million barrels a day. As the world's largest crude importer, China remains deeply connected to Gulf supplies despite that wider purchasing network.
China, India, Japan and South Korea together account for 75 percent of oil flows and 59 percent of LNG flows through Hormuz. Their combined exposure explains why a disruption in one waterway can become a regional economic emergency.
Why replacement crude is difficult to use
Asian refineries have invested in equipment suited to Middle Eastern crude, which often contains relatively high levels of sulfur. Desulphurisation units remove that sulfur during processing. These crude grades usually cost less than grades containing less sulfur, helping refiners earn higher margins when they can process them efficiently.
Middle Eastern crude also contains substantial quantities of fuel oil. Refineries can upgrade this into gasoline and diesel, or supply it as bunker fuel, the fuel used by ships. Singapore and China's Zhoushan are major refuelling ports where those products have an established market.
Changing crude supplies therefore changes more than the name of the seller. A refinery separates crude into different products and blends those products to meet fuel requirements. A different grade can require changes to the points at which those products are separated, gasoline blending and other operating settings.
Energy consultant Adi Imsirovic described the practical work involved in introducing a new crude grade into a refinery:
It's hard work,
Imsirovic linked those operating demands to the limited progress many countries have made in spreading their purchases across different suppliers:
This is why diversification has been so poor in a lot of countries.
Shipping time adds another constraint. Crude from West Africa or the Americas can take 45 to 60 days to reach China, compared with roughly 25 days for supplies travelling through Hormuz. Replacement cargoes may therefore arrive well after a refinery needs them.
Most Asian refiners also secure more than 50 percent of their crude requirements through contracts lasting several years. These agreements support stable supplies and price predictability during normal operations. During a crisis, their existing commitments limit the flexibility to buy different cargoes on the spot market, where supplies are purchased for nearer delivery.
Japan and South Korea have large buffers, but heavy exposure
Japan's emergency oil holdings cover 254 days of consumption and combine government stockpiles with compulsory private sector reserves. The country sources more than 90 percent of its crude from the Middle East, with the import share estimated at approximately 95 percent, and three quarters of those imports pass through Hormuz.
Japan's large reserve system gives it time to respond to interrupted deliveries. Its refining industry still faces the difficulty of changing crude grades. With domestic gasoline demand declining, Japanese refiners have been reluctant to invest in upgrades needed to process alternatives such as Canada's heavy TMX crude.
South Korea has strategic reserves sufficient for 208 days of consumption, managed by the Korea National Oil Corporation. Seoul has also activated a Middle East crisis task force operating around the clock as the won fell to its weakest levels since the 2008 global financial crisis.
The South Korean government is using state funds to subsidise freight costs for tankers taking the longer route around the Cape of Good Hope to avoid conflict zones. Shipping support helps address the cost of longer voyages, while the country's reserves provide a buffer against disrupted arrivals.
India and Southeast Asia face tighter supply margins
India's underground strategic storage caverns hold about nine days of supply. Its total reserves cover 50 to 60 days, leaving a much smaller cushion than those of Japan and South Korea. Middle Eastern producers supply 55 percent of India's oil, making the loss of nearby cargoes particularly difficult.
New Delhi has sought discounted Russian Urals crude, which now accounts for nearly 40 percent of imports. Washington granted India a reprieve lasting one month to purchase Russian oil after President Donald Trump threatened punitive tariffs. The temporary permission gives India another purchasing option as Gulf supplies face disruption.
Thailand has more than 60 days of oil cover and has frozen domestic diesel prices using its Oil Fuel Fund. The Philippines sources 96 percent of its oil from the Persian Gulf and holds roughly 60 days of supply across different fuel types. Philippine emergency measures include fuel subsidies and bus routes charging no fares.
Indonesia has only 21 to 25 days of reserves. Vietnam's petroleum buffer is less than 20 days, among the thinnest in Asia, and its dedicated national reserves cover just seven to nine days of net imports. Net imports measure the amount brought into the country after subtracting exports.
Those figures describe different kinds of holdings. India's nine days refer to strategic caverns, while its 50 to 60 days include a wider stock of supplies. Vietnam likewise has a broader petroleum buffer alongside a smaller dedicated national reserve. For households and businesses, the practical issue is how long usable supplies can cover consumption while governments and importers arrange new deliveries.
Qatar's shutdown brings a second energy squeeze
Qatar was a primary LNG supplier to Asia until Iranian drone strikes forced the shutdown of its Ras Laffan production facility. LNG is natural gas cooled into liquid so it can be carried by ship. At the destination, specialised terminals turn it back into gas for use in power generation and other activities.
Qatar declared force majeure on its contracts following the strikes. This is a contractual provision used when an extraordinary event prevents a supplier from fulfilling its obligations. Buyers have been seeking replacement cargoes as Asian spot prices climb to levels unseen since 2023.
Bangladesh, Pakistan and Taiwan are among the leading destinations for LNG shipped through Hormuz. For Bangladesh, financial constraints make replacement purchases especially difficult, creating an immediate threat to power generation.
The situation recalls 2022, when European buyers outbid Asian countries sensitive to higher prices and widespread blackouts followed. The current squeeze again puts the cost of replacement gas alongside the question of whether cargoes can be obtained at all. Industrial users also face supply rationing as buyers manage the disruption.
LNG is harder to redirect quickly than oil. Its supply chain depends on specialised terminals and contracts covering extended periods, while oil has a comparatively liquid global market, meaning it is more readily traded among buyers and sellers.
The Philippines and Vietnam opened their first LNG terminals in 2023, while Thailand increased LNG imports by 40 percent. Expanding seaborne gas purchases reduced some exposure to pipeline supply risks but increased dependence on maritime routes such as Hormuz. The Qatari shutdown has made that trade more costly.
Higher energy bills put currencies and budgets under strain
Oil and gas purchases are generally priced in US dollars. When those prices rise and an importing country's currency weakens against the dollar, the same shipment costs more in local money for both reasons. That cycle is putting pressure on the Philippine peso, Thai baht, Korean won and Indian rupee, alongside worsening trade balances.
Indonesia allocated 381 trillion rupiah, equivalent to $22.4 billion, for fuel subsidies in its 2026 budget. The budget assumed oil would cost $70 a barrel. With crude above $100, the gap between that assumption and market prices is more than $30 a barrel, increasing the strain on funds intended to shield consumers.
Malaysia continues to subsidise RON95 gasoline to hold its price at RM1.99 a litre. Prime Minister Anwar Ibrahim has warned that the subsidies cannot be sustained indefinitely if the conflict persists. Keeping the retail price fixed transfers more of the rising purchase cost to the government.
The Philippines has introduced temporary working weeks of four days and Pantawid Pasada fuel subsidies for transport and agricultural sectors. Its measures combine help with fuel costs and changes intended to reduce the burden of travel.
Thailand faces a projected reduction of 0.15 percent in GDP from the oil price surge. Estimates suggest that an increase of $10 a barrel could add 0.5 percentage points to inflation. Inflation measures how quickly consumer prices rise, while GDP measures the value of economic activity.
The Bank of Thailand has intervened in foreign exchange markets to stabilise the baht. Singapore's central bank, the Monetary Authority of Singapore, is assessing the effects on an economy where energy accounts for only 3 to 3.5 percent of the consumer price index. That relatively small share offers some protection against a broad jump in measured consumer inflation.
How Asia reached another energy emergency
The March crisis is the second major energy shock in four years, following the upheaval caused by Russia's invasion of Ukraine in 2022. Many Asian countries responded to that earlier disruption by increasing LNG purchases rather than renewable generation, leaving them exposed to another interruption in imported fuel.
The sequence connects earlier purchasing and investment decisions with the pressures now facing governments:
- 2022: Russia's invasion of Ukraine disrupted energy markets, and European competition for LNG contributed to blackouts in Asian countries unable to afford higher prices.
- 2023: The Philippines and Vietnam opened their first LNG terminals, Thailand expanded LNG imports by 40 percent, and South Korea generated just 9 percent of its electricity from renewables.
- 2024: China increased wind and solar generating capacity by 45 percent and 18 percent, respectively. Middle Eastern oil supplied about 50 percent of Singapore's imports.
- 2025: Asia imported a record 25 million barrels of crude a day, including 14.74 million from the Middle East. Singapore's Middle Eastern share rose above 70 percent.
- Early March 2026: Attacks on Persian Gulf energy facilities, the effective blockade of Hormuz and Qatar's production halt triggered a new supply and price shock.
As of March 11, no date had been given for restoring normal Hormuz shipping or restarting Qatari LNG production. Governments were therefore responding with their existing reserves, purchasing arrangements and emergency budgets while the duration of the disruption remained uncertain.
Domestic electricity offers a different kind of protection
Research by Zero Carbon Analytics identifies Japan as facing the greatest direct disruption risk because of its dependence on fossil fuels and its share of oil and gas flows through Hormuz. South Korea, India and China follow. Its analysis also links slower renewable energy transitions with greater exposure over time.
South Korea obtained only 9 percent of its electricity from renewables in 2023, compared with an average of 33 percent among members of the Organisation for Economic Co-operation and Development. Japan relied more heavily on fossil fuels than any other G7 country in the same year.
China offers a contrast. It led global wind and solar growth in 2024, with generating capacity rising 45 percent and 18 percent, respectively. Expanding renewable generation and electrifying transport have given it some protection against volatile fossil fuel prices, even as it remains the largest oil importer.
The Philippines has recently given priority to renewables through centralised green energy auctions and rules allowing greater foreign investment. Solar has become the fastest growing class of energy assets, while more expensive LNG projects have been shelved.
Energy experts identify solar projects built at utility scale as Asia's cheapest source of electricity when assessed by levelised cost. That measure spreads the cost of building and running a generating facility across the electricity it produces over its lifetime. Solar installations can operate for 25 to 30 years and require relatively little maintenance.
Europe saved approximately €12 billion after reducing gas demand through wind and solar additions following the 2022 shock. Across the Association of Southeast Asian Nations, more than 99 percent of wind and solar potential remains untapped. Those figures show why domestically generated electricity is being discussed as an energy security measure as well as a response to climate change.
Asian governments must still handle the immediate shortages with the tools already available: stored fuel, alternative cargoes, shipping support and assistance for consumers. Faster deployment of domestic clean energy offers a way to reduce the imported fuel exposure that has made this crisis so costly.
Key Points
- Asia imported 25 million barrels of crude a day in 2025, with nearly 60 percent coming from the Middle East.
- The effective blockade of Hormuz and Qatar's LNG shutdown have disrupted a supply corridor serving predominantly Asian buyers.
- Brent crude exceeded $100 a barrel, while Asian spot LNG reached approximately $23.80 per million British thermal units.
- Refinery equipment, longer shipping times and existing contracts make rapid changes of suppliers difficult.
- Reserve cover ranges from 254 days in Japan and 208 days in South Korea to less than 20 days in Vietnam.
- Governments are using subsidies, reserves and shipping assistance as higher import costs put currencies and budgets under pressure.
- Renewable electricity and transport electrification offer a way to reduce exposure to future imported fuel disruptions.