A $239 Billion Market Challenges Taiwan's Lead
South Korea's exchange traded fund market has reached $239 billion in the asset figures cited by Bloomberg Intelligence, narrowing Taiwan's lead to $11 billion. Korean ETFs attracted an average of $1.2 billion a week in fresh investment, compared with $330 million for Taiwan, as retail buying, semiconductor gains and changes to financial regulation supported Korea's expansion.
Contents
- A $239 Billion Market Challenges Taiwan's Lead
- New Money Accounts for More of Korea's Growth
- Market Reforms Target the Korea Discount
- AI Demand Gives Korean Chipmakers a Powerful Boost
- Large Gains Have Come With Sharp Swings
- Active ETFs Occupy an Unusually Large Role
- Taiwan's Strength Is Income Investing
- Asia Pacific Growth Extends Beyond the Rivalry
- The Dates Behind the Market Shift
- The Bottom Line
The race carries a date complication. The $239 billion asset snapshot is identified as late February 2025, and the accompanying forecast puts a Korean takeover by May 2025, while the stock market performance figures extend into early 2026. As of February 6, 2026, no updated ETF ranking or confirmation of that forecast is given. The figures describe a narrowing gap, alongside a Korean equity rally that continued into the new year.
An ETF pools investors' money into a portfolio and trades on an exchange like an ordinary share. It can give someone exposure to many stocks, bonds or other assets through a single purchase. Assets under management, often shortened to AUM, measure the value held inside those funds.
South Korea had trailed Taiwan since 2019. Its expansion has already taken it past Australia into fourth place among Asia Pacific ETF markets, behind Japan, China and Taiwan. Moving above Taiwan would place Korea third in that regional ranking, rather than make it the region's largest ETF market.
Rebecca Sin, an analyst at Bloomberg Intelligence, linked her earlier forecast to a narrowing of the valuation gap between Korean companies and their international peers:
South Korea will overtake Taiwan in ETF AUM by May, signalling a further reduction of the Korea discount.
New Money Accounts for More of Korea's Growth
Korea's average weekly ETF inflow of $1.2 billion was about 3.6 times Taiwan's $330 million, or roughly four times as much. That comparison measures money entering funds, which is a different part of market growth from gains in the investments those funds already own.
Bloomberg Intelligence's figures put the increase in Korean ETF assets during the year covered by its snapshot at approximately $95 billion. Sin attributed nearly 57% of that increase to fresh capital. Taiwan's corresponding share was 41%, leaving a larger proportion of its growth dependent on rising asset prices.
An ETF holding shares can become larger because those shares rise in value, because investors contribute more money, or through a combination of both. Korea's 57% share means fresh investment supplied more than half of the reported increase. Taiwan's 41% means price appreciation supplied the larger share there.
The difference is 16 percentage points. It helps explain why Korea's expansion has drawn attention beyond the performance of its biggest listed companies: investors were increasing their allocations to ETFs while the value of existing holdings was also growing.
Retail participation and confidence among international investors form part of the wider significance of ETF asset growth. The flow figures put new investment at the centre of Korea's advance, while the durability of that buying will matter during periods of falling markets.
Market Reforms Target the Korea Discount
South Korea's government has pursued policies intended to revive domestic capital markets and tackle the Korea discount. The term describes the tendency for Korean stocks to trade at lower valuations than comparable companies elsewhere, with concerns about corporate governance, unclear regulation and geopolitical risks contributing to that gap.
The Financial Services Commission has pushed initiatives to strengthen shareholder rights, improve corporate transparency and encourage dividend payments. These measures address longstanding complaints from foreign investors about the complex and opaque structures of chaebol, the large conglomerates that dominate much of the Korean economy.
Shareholder rights concern the protections and influence available to people who own a company's shares. Transparency helps them understand how a business operates and makes decisions. Dividends return part of a company's earnings to shareholders. Together, these issues affect how attractive investors find a stock and the price they are willing to pay for it.
Jason Yu, head of product strategy and development at Samsung Asset Management, connected ETF expansion to retail buying and the prospect of a wider product range:
Strong inflows of retail investors into ETFs are driving rapid market expansion. Products that were previously not permitted are expected to be introduced, helping in further shrinking of the Korea discount.
Yu's comments point to two drivers working together: more individuals putting money into ETFs and regulatory changes allowing additional investment products. The reforms have been associated with improving international confidence and a narrowing valuation gap. Rising share prices can then attract further ETF investment, reinforcing the market's growth.
AI Demand Gives Korean Chipmakers a Powerful Boost
Samsung Electronics and SK Hynix sit at the centre of the immediate market catalyst: demand for memory chips used in artificial intelligence computing. Both companies hold dominant positions in high bandwidth memory, known as HBM, and advanced dynamic random access memory, or DRAM.
Memory chips hold the data computers need while carrying out calculations. AI systems require large amounts of data to move quickly through their computing equipment, making advanced memory an essential part of the buildout of data centres. Shortages in that segment have strengthened investor interest in Korea's semiconductor companies.
Samsung Electronics and SK Hynix sharply outperformed Taiwan Semiconductor Manufacturing Company over the preceding year. TSMC's strength lies in manufacturing logic chips and providing foundry services, meaning it makes chips for other companies. Korea's major producers are concentrated in memory, where shortages have been especially acute.
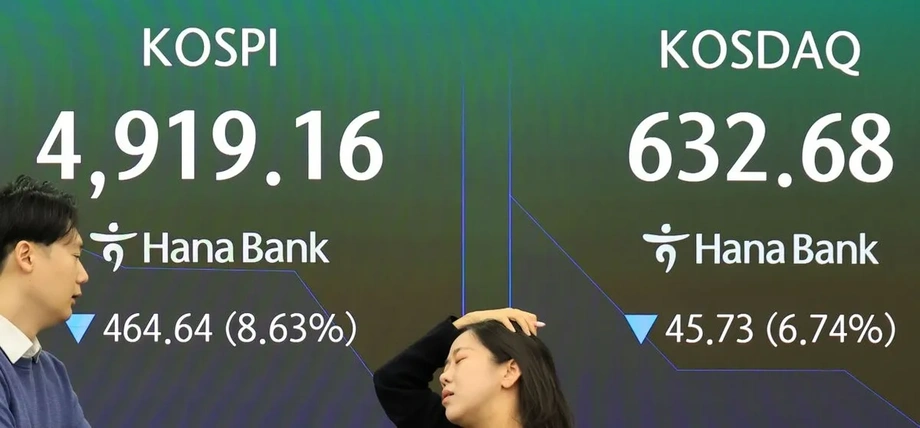
The Kospi, South Korea's benchmark stock index, surged 76% in 2025, described as a world leading performance, and rose another 22% in early 2026. Taiwan's Taiex gained 9.8% during the opening part of 2026. Those early 2026 figures put Korea's rise at more than twice Taiwan's.
South Korea's equity market surpassed Germany in total market capitalisation in January 2026 and entered the world's ten largest stock markets. Taiwan held eighth place globally. Market capitalisation is the combined stock market value of listed companies, a different measure from the assets held in ETFs.
Korean equity ETFs offer investors a route into the memory chip businesses supplying the AI expansion. Taiwan offers exposure to another part of the same industry through TSMC. The contrast helps explain why investors seeking AI hardware exposure can make different choices between two markets that both have large technology sectors.
Large Gains Have Come With Sharp Swings
The Kospi experienced intraday falls of more than 4% on two occasions during February 2026. An intraday decline measures a fall within a trading session, rather than necessarily the change between one day's closing price and the next.
Those swings reflect nervousness about whether spending on AI infrastructure can maintain its pace and whether the memory industry could eventually produce more chips than buyers need. Strong demand and a shortage can lift earnings expectations, while the prospect of oversupply can reverse investor enthusiasm.
Korea's ETF expansion therefore combines policy changes and wider participation with exposure to a volatile technology rally. A fund owning many companies can still move sharply when major holdings respond to the same industry pressures.
The difference between Korea's 57% share of growth from inflows and Taiwan's 41% may matter during a correction. Continued contributions can support fund assets when prices fall, although the strength of retail commitment will be tested by sustained volatility. Corporate governance reforms and broader ETF adoption provide longer lasting drivers alongside the semiconductor cycle.
Active ETFs Occupy an Unusually Large Role
J.P. Morgan Asset Management put active ETFs at approximately 31% of Korean ETF assets, the highest proportion globally. Unlike a passive ETF, which follows an index, an active ETF gives managers room to choose investments according to their strategy.
Active products attracted 33% of Korea's ETF flows in 2024. That was a moderation from the previous year, when active strategies captured more than 80% of inflows. The number of Korean active ETFs has more than doubled since 2022.
Nick Kim, an Asia Pacific ETF specialist at J.P. Morgan, described the direction of product launches:
We are seeing many Korean ETF issuers launching more ETFs focused on foreign assets and actively managed strategies.
Kim also gave an active ETF asset figure of approximately 80.4 trillion won, equivalent to $57.2 billion, representing 34.7% of total Korean ETF assets. That share and the broader 31% figure both describe a substantial active market, although the dates needed to align the two measurements are not given.
Korean retail investors also use leveraged and inverse ETFs tactically at the highest rate globally, with these products representing 9% of total ETF assets. Leveraged funds seek to magnify the moves of their target market, while inverse funds seek to move in the opposite direction. Their popularity reflects an appetite for taking positions on market movements.
AI, defence technologies and gold are among the themes attracting investors. Foreign markets have also become a growing focus, giving Korea's ETF industry routes to expansion beyond domestic shares.
Kim identified the themes supporting that growth:
Thematic and foreign market-focused ETFs contribute to such growth. AI and big tech have emerged as popular investment themes, while dividend theme remains an evergreen trend.
ETFs increased their share of Korea's mutual fund market from 9.5% to 15.5% over two years, a gain of six percentage points. Lower fees and integration into digital trading platforms favoured by younger investors have helped ETFs gain ground against traditional investment trusts.
Taiwan's Strength Is Income Investing
Taiwan has become Asia's largest bond ETF market. By late 2024, fixed income ETF assets reached NT$3.09 trillion, equivalent to $96 billion, and accounted for 48% of the country's ETF assets. Almost half the market was therefore invested in bond funds.
Retail demand for high dividend products and exposure to US Treasuries has shaped Taiwan's expansion. These investments appeal to people seeking income, rather than relying entirely on selling assets at a higher price later.
Ahmed Ibrahim, head of ETF solutions for Asia Pacific at State Street Global Advisors, described the role of individual investors:
The market is super-charged by retail investors. We believe ETF growth will continue, as a growing percentage of the total investing public uses the investment vehicle for wealth accumulation and income generation.
Taiwan's reported annual ETF asset growth was 54%, taking assets to approximately $196.5 billion. The number of ETF beneficiaries increased by 5.42 million to 14.11 million. Those figures show the scale of participation accompanying its rise.
The concentration in income products brings exposure to interest rate changes and shifts in US Federal Reserve policy. Interest rates affect the value of bonds and the relative attraction of different income investments, making monetary policy especially relevant to a market with such a large fixed income share.
Sin described Taiwan's challenge as finding alternatives to the high dividend rush that has absorbed investor attention. Taiwan's Financial Supervisory Commission approved active ETFs and passive funds combining different asset classes to broaden the product range. Expectations for 2025 were that at least five asset managers would launch active ETFs, potentially winning back business lost to passive products.
Asia Pacific Growth Extends Beyond the Rivalry
State Street projected that Asia Pacific ETF assets would grow 30% in 2025 and potentially reach $2.2 trillion. That projection placed the Korea and Taiwan contest within a much larger expansion across the region.
China was expected to overtake Japan as the largest regional ETF market, with assets exceeding $700 billion. Purchases sponsored by the state and regulatory mandates requiring mutual fund firms to increase equity holdings by 10% annually were identified as drivers.
Korea's move above Australia put it fourth in Asia Pacific. Continued product development and wider retail participation supported expectations that it could challenge Taiwan for third place before the end of the forecast year.
Globally, ETFs attracted a record $1.9 trillion in 2024, bringing total assets to $14.7 trillion. Active strategies captured 27% of worldwide flows despite accounting for only 9% of assets. Their share of new investment was therefore three times their share of the existing asset pool.
That global appetite fits Korea's established strength in active ETFs. Potential changes to US distribution fee structures could nevertheless put pressure on ETF expense ratios, the ongoing fund charges expressed as a percentage of assets. Technology volatility is another risk to continued retail demand.
The Dates Behind the Market Shift
The story spans several years of product development, investment flows and stock market gains. The main dated milestones show how Korea's ETF expansion developed alongside a changing regional market:
- 2019: The starting point for the period in which South Korea trailed Taiwan in ETF assets.
- Since 2022: The number of active ETFs in Korea more than doubled.
- 2024: Active strategies received 33% of Korean ETF flows; global ETFs attracted $1.9 trillion and reached $14.7 trillion in assets.
- Late 2024: Taiwan's bond ETFs reached NT$3.09 trillion, or $96 billion, representing 48% of its ETF assets.
- Late February 2025: The Korean asset snapshot was $239 billion, with Taiwan ahead by $11 billion; Sin forecast a Korean takeover by May.
- 2025: The Kospi rose 76%; regional forecasts anticipated wider ETF expansion and new active products in Taiwan.
- January 2026: South Korea surpassed Germany in equity market capitalisation and entered the global top ten.
- Early February 2026: The Kospi's gain for the year reached 22%, compared with 9.8% for the Taiex, alongside two intraday Korean market falls exceeding 4%.
Korea's central advantage is the combination of fresh investment, an established active ETF industry and strong demand for its memory chip companies. Taiwan's large base of income investors remains a source of strength, while its product approvals seek to create more choices beyond bonds and high dividend strategies.
The Bottom Line
- Korean ETF assets were $239 billion in the cited late February 2025 snapshot, only $11 billion below Taiwan.
- Average weekly inflows were $1.2 billion for Korea and $330 million for Taiwan.
- Fresh capital supplied 57% of Korea's reported asset growth, compared with 41% in Taiwan.
- Shareholder reforms and AI demand for memory chips supported Korea's expansion.
- The Kospi rose 76% in 2025 and another 22% in early 2026, while sharp daily swings exposed investor nervousness.
- Active ETFs held a large share of Korean assets; bond ETFs accounted for 48% of Taiwan's market in late 2024.
- Sin's forecast of a takeover by May 2025 has no confirmed outcome in the figures given as of February 6, 2026.