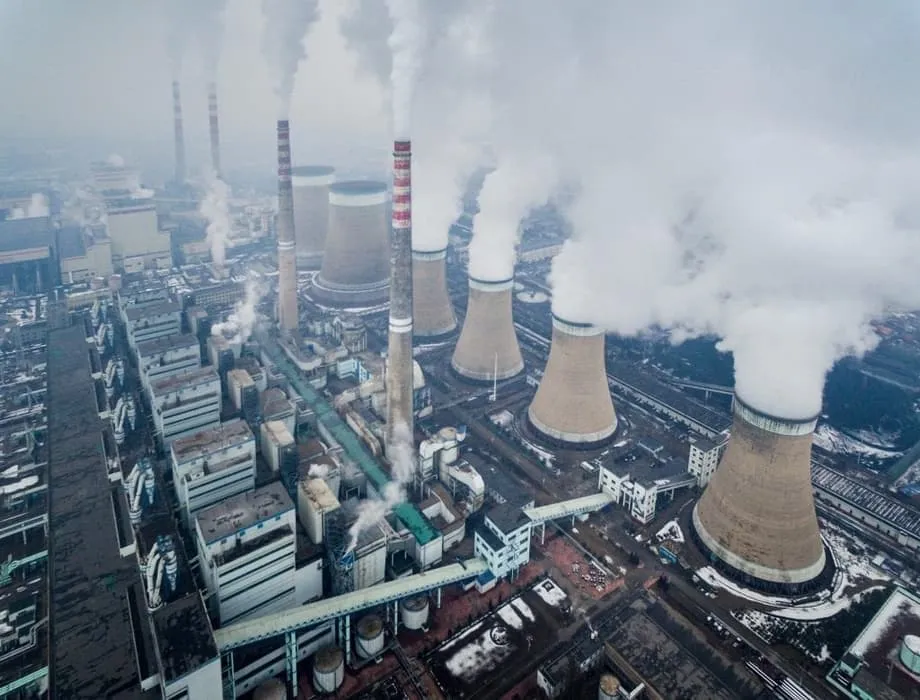
More Coal Plants, Less Coal Power
China commissioned 78 gigawatts of new coal power capacity in 2025, its highest annual total in a decade, while installing 315 gigawatts of solar capacity and 119 gigawatts of wind power. The country was expanding the machinery of its clean energy transition and the infrastructure of the fuel that transition is meant to replace.
Contents
- More Coal Plants, Less Coal Power
- A Construction Wave With More Still Coming
- Why Electricity Shortages Still Shape Decisions
- Permits From Earlier Years Keep Plants Moving
- The Decisions Behind the 2025 Surge
- China and India Stand Apart From Coal Retreats
- Clean Electricity Is Already Reducing Coal Output
- Who Pays When New Plants Run Less?
- Renewable Waste and Slow Coal Retirements
- The Next Five Years Put Coal's Role to the Test
- Key Points
A joint report by the Centre for Research on Energy and Clean Air and Global Energy Monitor describes the scale of that contradiction. More than 50 large coal units, each with a generating capacity of at least 1 gigawatt, entered service during 2025. China commissioned more coal power capacity in that single year than India did during the entire preceding decade.
Clean energy sources nevertheless passed 60% of China's total installed electricity capacity, with capacity from sources other than fossil fuels overtaking thermal generation capacity for the first time. Coal's share of electricity actually generated fell to 51% in June, its lowest level in nine years.
Capacity and generation measure different things. Capacity describes how much electricity a plant can produce at a given moment; generation measures how much it actually produces over time. A country can therefore build more coal plants while burning less coal for electricity, if those plants operate less frequently.
One gigawatt can supply several hundred thousand to more than 2 million homes, depending on how much electricity those households use. China's additions are consequently large even when individual plants spend much of their time idle. For the world's largest greenhouse gas emitter, the central issue is whether those plants become occasional backup or continue producing electricity for decades.
A Construction Wave With More Still Coming
China's 78 gigawatts of coal additions marked a sharp break from recent patterns. During the preceding decade, fewer than 20 large coal units had been commissioned annually. The 2025 surge returned construction activity to levels not seen since 2016, and projections indicated that additions for the full year could exceed 80 gigawatts.
The first half of 2025 had already delivered 21 gigawatts of newly commissioned coal capacity, the highest total for that period since 2016. Construction started on another 83 gigawatts during the year, while work restarted on 46 gigawatts of projects. The restarted capacity alone was equivalent to South Korea's entire coal power capacity.
Those construction starts and restarts point toward another wave of completed plants in 2026 and 2027. A plant entering service in 2025 is the result of decisions made earlier, while construction beginning now creates capacity that could shape the electricity system for years.
New and revived project proposals reached a record 161 gigawatts in 2025. By the end of the year, 291 gigawatts remained either permitted or under construction, equivalent to roughly 23% of China's existing operational coal fleet.
Xinjiang, Inner Mongolia and Shaanxi, all provinces or regions with substantial coal resources, led both commissioning and construction starts. More than three quarters of newly approved projects were financed by coal mining companies or energy groups with mining operations. Building power stations gives those businesses a way to secure demand for their coal through 2030 and beyond.
Why Electricity Shortages Still Shape Decisions
Power shortages in 2021 and 2022 left a lasting mark on China's energy policy. Severe droughts in the southwest reduced hydropower output, contributing to electricity shortages, factory shutdowns and rolling blackouts in some cities. Some factories temporarily stopped production, and one city imposed rolling blackouts.
China's government responded by signalling that it wanted more coal plants. Applications and construction permits surged as provincial authorities sought to prevent another period in which electricity supplies could interrupt industrial production and daily life.
The National Development and Reform Commission, China's lead economic planning agency, has said coal should retain an important foundational and balancing role for years to come. The approach is often described as establishing the new before breaking the old: expand cleaner energy while keeping existing sources available to protect electricity supplies.
Wind and solar output change with weather and the time of day. Coal plants can provide backup when those sources produce less electricity, although the usefulness of that backup depends on how plants are operated and how the grid moves electricity to where it is needed.
China's ambitions in artificial intelligence and advanced manufacturing add to the demand for dependable electricity. Data centres and factories require reliable power, including what is known as baseload power, a steady supply for continuing demand. Current limitations in storage and transmission mean renewables alone cannot yet guarantee that supply.
Household demand is also rising as more of China's 1.4 billion people enter the middle class and use air conditioning and other appliances. Electricity consumption increased 3.7% in the first half of 2025. Energy security concerns, industrial priorities and growing household consumption together help explain why coal construction continues even as cleaner sources expand.
Permits From Earlier Years Keep Plants Moving
Provincial governments approved more than 100 gigawatts of coal power annually in both 2022 and 2023, averaging two new projects a week. Local concerns about electricity security drove that surge, rather than national carbon targets. Many of those decisions are now producing completed plants.
Qi Qin, a China analyst at the Centre for Research on Energy and Clean Air, explained why earlier approvals continue to influence construction even when market conditions change.
Once permits are issued, projects are difficult to reverse,
Construction activity reached a high of 94.5 gigawatts in 2024, the largest total in 10 years, setting up the commissioning boom in 2025. Permits, financing and construction create momentum that can persist while demand for coal generation weakens.
Only 25 gigawatts were permitted in the first half of 2025, below the peak years. Yet new and revived proposals reached 75 gigawatts during that same period, the highest level in a decade. The combination suggests that a slower rate of approvals had not ended the industry's push for more projects.
China's commitment to peak carbon emissions before 2030 adds urgency for companies seeking approval before tighter policies arrive. The record 161 gigawatts of new and revived proposals during 2025 signals a rush to advance projects while that opportunity remains.
Qi's assessment centres on how the plants will be used. Whether expansion produces higher emissions depends on whether coal is genuinely limited to backup and support, or continues to provide baseload generation. Political and financial pressure to operate new plants could leave less room on the grid for other electricity sources.
The Decisions Behind the 2025 Surge
China's coal expansion unfolded across several years, with electricity shortages followed by approvals, construction and commissioning. The next policy decisions will arrive while projects from that earlier cycle are still being completed.
- 2021 and 2022: Electricity shortages, including drought related losses of hydropower in southwest China, strengthened the government's focus on energy security.
- 2022 and 2023: Provincial governments approved more than 100 gigawatts of coal power each year, averaging two new projects a week.
- 2024: Coal construction activity reached a high of 94.5 gigawatts, preparing the ground for a surge in completed plants.
- First half of 2025: China commissioned 21 gigawatts, permitted 25 gigawatts and recorded 75 gigawatts of new and revived proposals.
- Full year 2025: China commissioned 78 gigawatts, started construction on 83 gigawatts, restarted work on 46 gigawatts and recorded 161 gigawatts of new and revived proposals.
- March 2026: Approval of the 15th Five-Year Plan, covering 2026 to 2030, was expected.
- 2026 and 2027: Recent construction starts and restarts suggest another wave of coal plant completions.
The timeline explains why a change in policy cannot instantly change the fleet. Plants completed in one year often reflect approvals issued several years earlier, while today's construction decisions extend into the next planning period.
China and India Stand Apart From Coal Retreats
China and India accounted for 87% of new coal power capacity commissioned globally in the first half of 2025. Their continued expansion contrasts with closures and abandoned proposals across several other regions.
The European Union closed 2.5 gigawatts of coal capacity during that period, nearly matching its entire retirement total for 2023. Ireland became the fifth EU country to phase out coal power entirely in June 2025.
Latin America had no active coal plant proposals after projects in Honduras and Brazil were shelved, the first such absence in recent memory. Honduras had joined the Powering Past Coal Alliance in May.
The United States remained on track to retire more coal capacity in 2025 than in 2024 despite policy shifts under the Trump administration. Utilities planned nearly 100 gigawatts of closures by 2035.
Vietnam, Indonesia and South Africa were pursuing just energy transition partnerships while maintaining coal use and planning its eventual phaseout. Those partnerships form part of their efforts to manage the move away from the fuel. China, by contrast, had not publicly discussed a timetable for ending coal use.
Advanced economies are dismantling coal infrastructure while China and India continue expanding it, citing development needs and grid stability. China consumes more than half of all coal burned worldwide, giving its decisions an especially large influence on global emissions.
Clean Electricity Is Already Reducing Coal Output
Coal generation in China declined 2.9% in the first half of 2025, while solar generation rose 20% and wind generation increased 10.6%. Clean energy supplied all the net growth in electricity demand, allowing coal's share to fall even as new plants opened.
The solar and wind capacity installed during the full year totalled 434 gigawatts, combining 315 gigawatts of solar with 119 gigawatts of wind. That was more than five times the 78 gigawatts of newly commissioned coal capacity. The figures describe generating equipment, while actual electricity output depends on how often each source operates.
China's average coal plant operated at a utilisation rate of just 47% in 2025, down from historical norms of around 70%. The lower rate means the fleet was being used much less intensively, adding to concerns that more capacity is being built than the system needs.
Tim Buckley, director of the Sydney based think tank Climate Energy Finance, described the 47% figure as a record low. He said the pace of renewable installations and future nuclear additions would help determine the direction of coal generation.
If renewable installs can run at anywhere near current rates, and nuclear can pick up to 10 gigawatts a year over the coming decade, we will see a plateau and then slow decline in coal power generation,
The International Energy Agency projected that China's coal demand would fall to 4,879 million tonnes by 2027 and decline further to 4,772 million tonnes by 2030. Renewables were expected to supply 49% of China's electricity by 2030, surpassing coal. The projected reduction in Chinese coal demand would more than offset expected increases in US coal use under current policies.
China also added around 74 gigawatts of new energy storage capacity in 2025, broadly comparable to the coal capacity commissioned that year. Storage can hold energy for use later, helping the grid meet peaks in demand and balance changes in wind and solar output. Its expansion is steadily reducing coal's role in those tasks.
Who Pays When New Plants Run Less?
The 291 gigawatts of permitted or unfinished coal projects create a financial risk as plant utilisation falls. A stranded asset is a plant that becomes uneconomical before earning back its construction costs. More plants competing for fewer operating hours can make that risk harder to avoid.
The rush to advance projects before tighter policies arrive could waste investment and crowd out renewable generation. Coal companies and other investors have an interest in keeping completed plants running, even when cleaner electricity is available.
Provincial power systems help protect coal through purchase contracts covering the medium and long term, alongside coal supply agreements that oblige utilities to use the fuel regardless of cost. Those commitments can preserve coal consumption even when market conditions would favour another source.
Capacity payment mechanisms also reward installed coal capacity rather than flexibility or actual performance. A capacity payment compensates a plant for being available, rather than simply for the electricity it sells. The concern is that payment rules may support the size of the coal fleet without rewarding the services the changing grid needs most.
Wind and solar developers, meanwhile, face fluctuating prices and uncertain demand. Coal plants insulated from competition can keep operating while renewable producers struggle to sell their electricity. The result depends on both investment decisions and dispatch rules, the instructions that determine which plants supply power at a given time.
Renewable Waste and Slow Coal Retirements
Renewable curtailment is rising. Curtailment happens when usable wind or solar electricity is kept off the grid because the system cannot accept it or gives other generators priority. It wastes electricity that could otherwise serve consumers.
The estimated curtailment rate in the final quarter of 2024 was around 5.5%, compared with the officially reported 3.2%. The higher estimate attributed the lost generation to structural constraints rather than weather. A large coal fleet operating under inflexible dispatch rules can reduce the space available for clean energy.
Coal retirements were also falling behind the target in the 14th Five-Year Plan. Only 1 gigawatt was retired during the first half of 2025, bringing the total closed since 2021 to 16 gigawatts.
The plan called for 30 gigawatts of retirements by the end of 2025. Analysts estimated that 13 gigawatts would need to close in the second half of the year to meet the goal and viewed that pace as increasingly unlikely. The final retirement outcome was not given.
New construction and slow closures work in the same direction: they increase the amount of coal equipment that the electricity system must accommodate. Growing renewable output then competes with a larger fleet whose owners have contracts, payment arrangements and investment costs encouraging continued operation.
The Next Five Years Put Coal's Role to the Test
China has pledged to peak carbon emissions before 2030 and reach carbon neutrality by 2060. Carbon neutrality means balancing the carbon released with an equivalent amount removed or otherwise offset. The continued expansion of coal infrastructure creates tension with those commitments.
Analysts argue that power sector emissions must not increase between 2025 and 2030 for China to meet its goals. Their proposed response is an immediate shift from building more coal capacity toward retiring existing plants.
The 15th Five-Year Plan, covering 2026 to 2030 and expected to be approved in March, is the next major policy window. Researchers are urging Beijing to set explicit targets for the peak in power sector emissions, stop new coal approvals and accelerate the retirement of ageing, inefficient or underused units.
The climate policy timetable also included an expectation that President Xi Jinping would announce China's Nationally Determined Contributions before the COP30 climate summit in Brazil. Those contributions set out a national commitment to reduce greenhouse gas emissions by 2035. Details were also expected in the Five-Year Plan.
The planning decisions will help determine whether coal capacity keeps growing or shifts toward a smaller supporting role. Without a clear end to net capacity growth, new plants could become a lasting obstacle to the energy transition, even while renewable installations continue at an exceptional pace.
China's position combines two powerful trends: cleaner sources are taking a larger share of electricity production, while coal investors continue building. Reforming approvals, retirement rules, contracts and payments would connect the physical fleet more closely to the electricity system's changing needs. Without reform, China risks leaving billions in coal investment stranded while missing its climate targets.
Key Points
- China commissioned 78 gigawatts of coal capacity in 2025 while adding 315 gigawatts of solar and 119 gigawatts of wind.
- Coal generation fell 2.9% in the first half of 2025, and coal's share of electricity output reached 51% in June.
- More than 50 coal units with capacity of at least 1 gigawatt entered service, while average coal plant utilisation fell to 47%.
- New and revived proposals reached 161 gigawatts, with 291 gigawatts permitted or under construction at the end of 2025.
- China and India accounted for 87% of global coal capacity additions in the first half of 2025.
- The International Energy Agency projected Chinese coal demand of 4,879 million tonnes in 2027 and 4,772 million tonnes in 2030.
- The 15th Five-Year Plan, expected for approval in March 2026, will guide policy through 2030 as another wave of plants approaches completion.