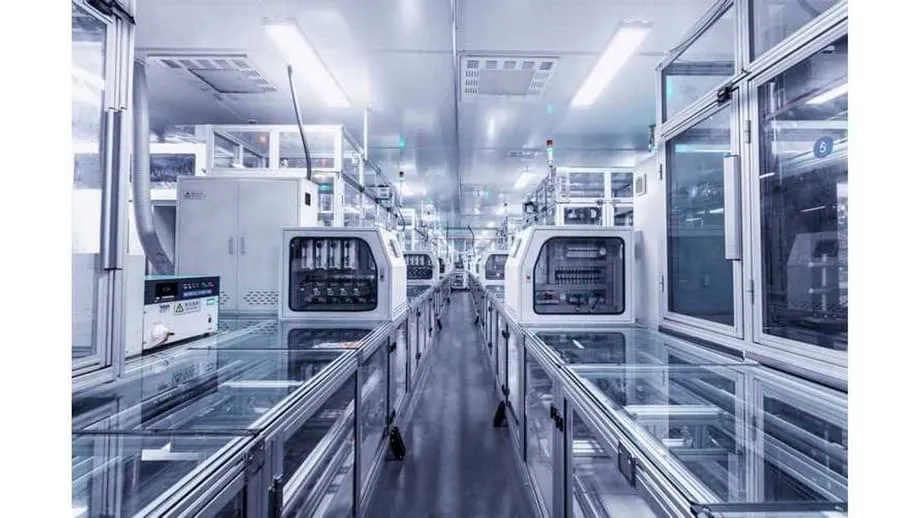
A $110 Billion Battery Business Behind BYD's Cars
BYD's battery operations could be worth about $110 billion, close to the Chinese company's roughly $115 billion stock market value, according to Bernstein. The investment firm's assessment, published here on January 21, 2026, puts a business often overshadowed by vehicle sales at the center of its case for buying BYD shares.
Contents
- A $110 Billion Battery Business Behind BYD's Cars
- What the Valuation Argument Means
- Battery Roots and the Blade Design
- Other Automakers Become Battery Customers
- Energy Storage Opens Another Market
- From Lithium Supplies to Semiconductor Chips
- Factories and Ships Support Expansion
- Sales Leadership Meets Pressure on Prices
- Different Models Produce Different Share Values
- Trade Barriers and the Demands of Growth
- The Bottom Line
Bernstein analyst Eunice Lee maintains an outperform rating, a recommendation expressing confidence that the shares will beat their benchmark, and a price target of HK$130 ($16.67). That target is approximately 30% above recent trading levels. Her argument is that investors largely price BYD as a Chinese electric vehicle maker while heavily discounting its batteries, electronics, semiconductors and other operations.
BYD is the world's second largest manufacturer of batteries for electric vehicles. It ships 70% more batteries than the third largest competitor. Its battery division contributed more than 10% of company revenue last year, with Bernstein expecting that share to reach the middle of the teens this year.
Battery shipments grew 47% last year, and Bernstein projects another 35% increase this year. Demand comes from three directions: BYD's own vehicles, other automakers buying its batteries, and energy storage systems that hold electricity for later use.
Lee's assessment also describes the battery business as approaching BYD's entire enterprise value. Enterprise value measures the value of a company's operations by taking its stock market value, adding debt and subtracting cash. Stock market value measures the value of its shares alone. Bernstein's central claim is that batteries account for almost all the value investors currently assign to the wider group.
What the Valuation Argument Means
Bernstein's valuation would leave little additional value assigned to BYD's automotive, electronics, semiconductor and other businesses. In investment terms, a buyer would effectively receive those operations at little or no extra cost if the firm's estimate for batteries is right.
The figures show how large that claim is: a $110 billion battery valuation equals about 96% of BYD's $115 billion market capitalization. Market capitalization is the share price multiplied by the number of shares. The comparison is a way to understand Bernstein's argument, while enterprise value also takes account of cash and borrowing.
BYD's market capitalization is more than twice Ford Motor's approximately $55 billion valuation. A decade ago, Ford was worth far more than the Chinese company. Bernstein nevertheless sees substantial value still hidden inside BYD, particularly as batteries become a larger contributor to revenue.
Investors buying into that argument are backing both manufacturing growth and a reassessment of the business. The battery division would need to deliver the sales and earnings expected of it, while the market would need to assign those operations more value.
Battery Roots and the Blade Design
BYD began making cellphone batteries in the 1990s and entered the automotive industry in 2003. That history gave it battery expertise before electric vehicles became a major market. Many traditional automakers had to secure supplies from specialist battery manufacturers, while BYD developed its own technology internally.
BYD carried that control into vehicle production. Its battery work now includes designing and manufacturing cells, modules and packs for different vehicle layouts and performance requirements. Cells are the individual units that store energy; modules group cells together; a pack combines them into the battery system used by a vehicle.
BYD produces its batteries through FinDreams Battery, which operates multiple manufacturing facilities. Making them internally reduces dependence on suppliers such as CATL and LG Energy Solution and gives BYD more control over costs, supply and the pace of product development.
The Blade battery, introduced in 2020 in the sporty Han sedan, is the centerpiece of that technology. It uses lithium iron phosphate, or LFP, chemistry rather than the nickel, manganese and cobalt combination used in other batteries. Its long, blade shaped cells fit densely into a pack, improving energy density while retaining safety advantages.
Energy density describes how much energy a battery can store for its size or weight. The Blade design seeks to improve the amount stored in the finished pack through the arrangement of its cells, alongside advantages in safety, durability and cost compared with conventional nickel, manganese and cobalt batteries.
BYD's nail penetration testing demonstrated the Blade battery's stability under conditions that can cause conventional batteries to enter thermal runaway. Thermal runaway is a chain reaction in which rising heat triggers further heating and can lead to fire. Battery safety has become a selling point for buyers concerned about electric vehicle fires.
Bernstein credits this focus on safety and cost with helping BYD reach leadership in electric vehicle sales and surpass Tesla in total electric vehicle deliveries. BYD's figures include battery electric vehicles and plug-in hybrids. The Blade battery's lower costs also support competitive vehicle prices while protecting margins in China's increasingly price sensitive market.
Other Automakers Become Battery Customers
Approximately half of BYD's battery production powers its own vehicles. Sales outside the group are growing rapidly: Bernstein says battery shipments to external automakers nearly tripled last year. Xiaomi and XPeng each accounted for 25% of those external electric vehicle battery shipments, together representing half of that category.
Toyota has also become a significant customer. Its joint development agreement with BYD was established in 2019, followed by a joint venture in 2020. The relationship brings BYD's battery and electric vehicle development capabilities together with Toyota's experience in vehicle quality and safety.
BYD Senior Vice President Lian Yu-bo described the combination as drawing on BYD's development strengths and competitiveness in battery electric vehicles alongside Toyota's quality and safety technology. The partnership illustrates how an automaker that competes with BYD can also work with it on electrification.
Toyota Executive Vice President Shigeki Terashi described the companies as setting rivalry aside to promote wider adoption of electrified vehicles. He used this word for the relationship:
teammates
Ford Motor has reportedly held talks about buying BYD batteries for some hybrid vehicles outside the United States. Neither company has confirmed those discussions. A Ford spokesperson said the company engages with many potential partners; no purchase agreement or timetable was given.
External customers give BYD a way to sell its technology beyond its own cars. Its production capacity and competitive pricing position it to win business from automakers seeking reliable supplies amid battery shortages. That expands the potential customer base and makes battery revenue less dependent on sales of BYD vehicles alone, although sales to other automakers still depend on demand for cars.
Energy Storage Opens Another Market
BYD's energy storage battery shipments more than doubled last year. In September, the company revealed a system for utilities based on Blade battery technology called Haohan. Bernstein says the system costs less to manufacture than competing solutions, giving BYD a pricing advantage in a market with strong growth prospects.
Energy storage systems save electricity when it is available and release it when it is needed. They are useful for renewable power because solar and wind generation vary with the weather and time of day. Utilities can use batteries to help balance supply and demand rather than rely entirely on electricity being generated at the moment it is consumed.
Grid operators also use storage to manage peak demand and regulate frequency, the rhythm at which an electricity grid operates. Keeping that rhythm stable helps the network deliver reliable power. These uses create a market for batteries beyond vehicles, drawing on BYD's existing manufacturing and research capabilities.
Bernstein highlights BYD's leading rankings in both energy storage cell shipments and system integration. Cell shipments measure the batteries delivered; integration involves assembling batteries and the equipment needed to operate them as a complete storage system.
BYD's energy storage operations diversify its revenue beyond the competitive automotive market. Bernstein also sees possible growth from emerging technologies such as sodium-ion batteries. The broader investment case rests on BYD applying its battery production scale and cost advantages to electricity networks as renewable generation expands.
From Lithium Supplies to Semiconductor Chips
BYD's control of production extends from access to raw materials through batteries, chips, vehicle assembly and software development. This approach is called vertical integration: a company performs several stages of production itself instead of buying each stage from an outside supplier.
BYD has formed partnerships lasting many years and acquired stakes in mining companies to secure lithium and other critical materials. It recently acquired mineral rights covering two plots totaling 852 hectares in Brazil's Jequitinhonha Valley, an area often called Brazil's Lithium Valley.
Access to raw materials helps BYD manage exposure to price swings and supply disruptions. FinDreams also operates facilities that process lithium into chemicals suitable for batteries. Internal refining gives the group control over quality, reduces dependence on outside processors and helps it respond when demand rises.
BYD established BYD Semiconductor in 2004. The division produces chips for battery management systems, motor controllers and smart cockpit functions. Battery management systems monitor and control batteries; motor controllers regulate the electric motors that move a vehicle.
Control over chip design and manufacturing reduces BYD's exposure to semiconductor shortages. It also allows the company to tailor hardware to its software and vehicle systems. This wider control of its supply chain helped BYD navigate the global semiconductor shortage more successfully than many competitors.
BYD's manufacturing model seeks cost savings across those connected operations. Keeping more work inside the group can shorten the distance between design and production, support faster changes and reduce dependence on the prices and delivery schedules of outside suppliers.
Factories and Ships Support Expansion
BYD operates large manufacturing complexes in Xi'an, Changsha and Shenzhen. Different vehicle components are assembled within unified facilities, reducing transport between suppliers and improving production efficiency. These sites support the scale needed for millions of annual vehicle sales.
In 2024, BYD delivered more than 4.27 million new energy vehicles. The category includes vehicles running entirely on batteries and plug-in hybrids, which combine a rechargeable battery with an engine. In the first quarter of 2025, sales approached 1 million, up 60% from the same period a year earlier.
BYD is extending its manufacturing presence overseas rather than relying entirely on exports from China. It broke ground on its first European passenger vehicle factory in Szeged, Hungary, in 2024. The plant is intended to shorten delivery times for European customers and help the company navigate trade barriers through local production.
BYD has also invested in its own fleet of roll-on/roll-off ships, vessels onto which vehicles can be driven for transport. Its recently unveiled BYD Shenzhen can carry 9,200 vehicles and was described as the world's largest vehicle carrier. Control over shipping gives the company greater flexibility in international deliveries and reduces exposure to shortages of transport capacity.
Several dates trace how BYD built the operations behind today's battery valuation argument:
- 1990s: BYD began manufacturing cellphone batteries.
- 2003: The company entered the automotive industry.
- 2004: BYD Semiconductor was established.
- 2019: BYD and Toyota established a joint development agreement.
- 2020: Their joint venture was established, and BYD launched the Blade battery in the Han sedan.
- 2024: BYD delivered more than 4.27 million new energy vehicles and broke ground on its factory in Szeged.
- First quarter of 2025: Vehicle sales approached 1 million, increasing 60% from a year earlier.
- September 2025: BYD revealed its Haohan energy storage system.
Sales Leadership Meets Pressure on Prices
BYD has become China's best selling car brand, with more than 2.4 million new registrations, displacing Volkswagen after more than 15 years at the top. It has also surpassed Tesla in total electric vehicle sales, with BYD selling both battery electric vehicles and plug-in hybrids.
The International Energy Agency puts BYD and Tesla's combined share at 35% of global electric car sales, more than the combined sales of all major carmakers outside China. BYD alone has a 20% share of the global electric car market when battery electric vehicles and plug-in hybrids are counted together.
China's market remains intensely competitive, with dozens of manufacturers seeking buyers. BYD has reduced model prices by 10% to 20% to maintain sales momentum. Lower prices put pressure on profit margins, while the company's control over production gives it cost buffers that less integrated competitors lack.
Only about one third of Chinese carmakers met their sales targets in 2023. BYD was among those that did, while several rivals missed their targets for consecutive years. The figures show the uneven results of competing in a market where sales growth and price cuts do not benefit every manufacturer equally.
Bernstein projects 10% growth in BYD's domestic vehicle sales this year to 5.4 million units, alongside a 4.4% increase in overseas sales to 1.5 million. Those two projected totals amount to 6.9 million vehicles. The firm's expectations sit against projected growth of just 1% for China's automotive market, making gains in market share part of its case.
The China Association of Automobile Manufacturers forecasts 15.2% growth in new energy vehicle sales this year and a 4.3% increase in exports. The faster expected growth in new energy vehicles than in the wider Chinese car market helps explain why battery manufacturers can have stronger prospects than the automotive market's headline growth rate suggests.
Different Models Produce Different Share Values
Bernstein's HK$130 target is higher than the HK$106 target attached to a Buy upgrade from TipRanks-PerPlexity. The forecasts point in the same direction but put different values on the expected growth.
A Simply Wall Street valuation puts BYD's price-to-earnings ratio at 20.2 times, above an 8.8 times peer average and an estimated fair ratio of 14 times. A price-to-earnings ratio compares a company's share price with the profit earned per share. A higher ratio generally means investors are paying more for each unit of current earnings in anticipation of future growth.
BYD's ratio is about 2.3 times the peer average, using the stated figures of 20.2 and 8.8. That premium leaves the shares vulnerable if earnings fall short of expectations. A discounted cash flow calculation, however, suggests BYD trades 17.7% below estimated fair value.
Discounted cash flow models estimate the money a company may generate in future years and translate it into a value today. The earnings ratio focuses on the price paid for earnings, while the cash flow method relies on assumptions about future cash generation. Their different conclusions show why the same company can appear expensive under one approach and inexpensive under another.
Bernstein expects near term support from upgrades to battery electric vehicles and battery technology, along with new products. BYD is slated to introduce at least 10 automotive models this year. Those launches give the company several chances to attract buyers, while battery upgrades could support demand from outside customers as well as its own vehicle business.
Trade Barriers and the Demands of Growth
BYD's international expansion faces trade barriers as well as competition. Its strategy includes building factories in key markets and controlling more of its shipping capacity, reducing reliance on a business based solely on exporting finished vehicles from China.
The trade discussion accompanying the valuation case referred to the European Union's investigation into subsidies for electric vehicle imports and possible new tariffs from July 2024. It also cited United States import taxes of 27% on Chinese vehicles as a constraint on direct access to that market. Those references belong to the trade backdrop described with the investment case.
Slower growth in important markets is another risk. Bernstein's forecasts require BYD to expand vehicle sales while increasing battery shipments by 35%, building external customer relationships and supplying a growing energy storage business. Competition and price reductions can affect how much profit those additional sales generate.
BYD's breadth is central to Bernstein's argument: the company has battery expertise developed since the 1990s, a large internal vehicle customer, growing sales to rival automakers and a storage business whose shipments more than doubled last year. The investment question is how much those connected operations can earn and what investors will pay for them.
The Bottom Line
- Bernstein values BYD's battery business at about $110 billion against a company market capitalization of roughly $115 billion.
- Its outperform rating carries a HK$130 ($16.67) target, approximately 30% above recent trading levels.
- BYD ranks second in electric vehicle batteries, shipping 70% more than the third largest competitor.
- Battery shipments grew 47% last year; Bernstein forecasts 35% growth this year.
- External automotive battery shipments nearly tripled, with Xiaomi and XPeng each accounting for 25% of that category.
- Energy storage battery shipments more than doubled, and BYD introduced its Haohan system in September.
- BYD delivered more than 4.27 million new energy vehicles in 2024 and approached 1 million sales in the first quarter of 2025.
- At least 10 automotive model launches are expected this year, alongside vehicle and battery technology upgrades.
- Competing valuation methods give different results, while price pressure, trade barriers and slower market growth remain risks.