A third factory takes shape in Wuhan
Yangtze Memory Technologies Corp has begun construction of a third memory factory in Wuhan, with production targeted for 2027, as China seeks more locally made chips for artificial intelligence, cloud services and consumer devices. A new entity created to build the factory has about 20.7 billion yuan in registered capital, according to Chinese corporate registry filings.
Contents
- A third factory takes shape in Wuhan
- How much capacity could the expansion add?
- What the new factory is expected to make
- Understanding 232 layers and Xtacking
- Chinese equipment becomes central to the plan
- How export controls affect the expansion
- Why DRAM and high bandwidth memory are being considered
- Packaging skills could support a broader memory business
- Who would buy the additional memory?
- The production and financial risks
- The milestones leading to 2027
- Key Points
The expansion puts China's leading maker of NAND flash on a growth path despite restrictions on its access to advanced manufacturing equipment. YMTC remains on the United States Entity List, which limits access to many tools used to make modern chips. The new factory is expected to rely more heavily on Chinese equipment than its two existing plants.
NAND flash is the storage technology that keeps information when power is switched off. It holds files in smartphones and personal computers and provides storage in servers. Training large AI models, running them for users and operating cloud services all require vast amounts of fast, persistent storage.
Chinese customers are shifting toward local suppliers as they redesign supply chains. For policymakers, expanding domestic memory production reduces reliance on imports and supports data infrastructure considered strategically sensitive. YMTC is owned by a holding entity backed by the state, and its expansion fits national investment programs for strategic industries.
As of December 16, 2025, the project also points toward a possible move beyond NAND into dynamic random access memory, or DRAM, and eventually high bandwidth memory for AI processors. Those possibilities sit alongside the immediate task: building a factory, installing suitable equipment and turning new production lines into a dependable source of storage chips.
How much capacity could the expansion add?
YMTC's two existing Wuhan factories were capable of producing about 160,000 wafers measuring 12 inches across per month at the end of 2024. Plans called for another roughly 65,000 wafers per month during 2025 as equipment installations continued. The third factory would provide a separate stream of supply from 2027.
The planned increase during 2025 would bring the existing plants to about 225,000 wafers per month if completed, roughly 41 percent above the level at the end of 2024. That calculation describes the expansion plan; the article's December 2025 account did not confirm that the full increase had been achieved.
Industry estimates put YMTC at roughly 7 to 8 percent of global NAND capacity but less than 5 percent of revenue. Product mix and pricing help explain the gap: a company's share of the chips it can make need not match its share of the money customers spend.
Investment trackers have projected that YMTC could account for a sizable share of global NAND capital spending in 2025. The company aims to join the top tier of producers by capacity as its new lines increase output.
The investment follows a recovery in memory prices after a deep downturn in 2023. Large producers outside China have expanded cautiously to avoid creating another glut, when supply exceeds demand and prices fall. YMTC is pushing ahead to serve domestic customers even if its manufacturing technology does not match the newest processes used by rivals in South Korea and the United States.
What the new factory is expected to make
The project is the third major complex on YMTC's Wuhan campus. Its two existing plants focus on 3D NAND, and the company has been expanding the second site to increase output. The new facility is intended to add meaningful capacity for mainstream data center and consumer storage products.
YMTC intends to produce its first wafers at the third factory in 2027, with mass production also targeted for that year. Output would then rise as equipment becomes ready and yields improve. Yield is the share of manufactured chips that work properly, a measure that directly affects how much usable product a factory produces.
Specific details of the new factory's manufacturing process have not been made public, and no exact date within 2027 was given. The project is expected to carry forward technology in the class of YMTC's existing advanced NAND, while the highest layer counts used by global leaders may remain out of reach in the near term.
A third factory also gives YMTC more space to refine production, improve yields and change the mix of chips it makes. Its potential markets include servers, personal computers, automotive systems and industrial devices, each with different storage needs.
Understanding 232 layers and Xtacking
Modern 3D NAND stacks memory cells vertically. Adding layers puts more storage into a given area and can reduce the cost of each bit of information. The challenge is to manufacture those layers with the precision needed for reliable operation.
YMTC uses an architecture called Xtacking, which bonds a logic wafer to a memory wafer. The logic contains the circuits that control the memory, while the other wafer holds the array of storage cells. Separating their manufacture can improve performance and shorten development cycles.
In 2023, YMTC introduced the X3 9070, a chip with 232 layers that stores four bits in each cell. This type of memory is called QLC, short for quad level cell. The chip reached a storage density of about 19.8 gigabits per square millimeter.
QLC increases the amount of information a chip can hold, but it brings trade offs in performance and endurance, meaning how well memory withstands repeated writing. Those trade offs matter in enterprise drives, where the demands on storage differ from those of many consumer devices.
Industry records show YMTC continues to ship 3D NAND based on Xtacking while qualifying more equipment made in China. The new factory offers additional room to develop that combination of chip design and manufacturing tools.
Chinese equipment becomes central to the plan
Chinese supply chain accounts indicate that the third factory will use a greater proportion of domestic equipment than the first two plants. That shift follows national policy and reflects the practical difficulty of obtaining restricted foreign tools.
Local suppliers are working to fill gaps in lithography, etching, deposition and inspection. These are different stages of chip production: creating patterns, removing material, adding material and checking whether the resulting structures meet requirements.
Progress is steady, but matching the speed and precision of the most advanced imported equipment will take time. YMTC appears confident that domestic tools will support manufacturing at high volumes for mainstream products by the time the new lines begin operating, even if the most advanced features are absent at the start.
Building a native supply chain at scale is a central part of the third factory's strategy. A successful expansion would give Chinese device and server makers a more stable local source of flash memory, with less dependence on restricted imports.
How export controls affect the expansion
The United States placed YMTC on the Entity List in December 2022. That action, together with export rules introduced before and afterward, restricts access to certain lithography, deposition, etching and measurement tools, design software and other items containing United States technology.
In 2024, the United States Bureau of Industry and Security, or BIS, also introduced explicit controls on high bandwidth memory used in AI accelerators. Licensing requirements have become more detailed for facilities in China, increasing the compliance work required of international suppliers.
Companies in China have sought to maintain production using older equipment, modified manufacturing processes and purchases that avoid restricted items. Some have also investigated channels through third parties for spare parts and materials outside the restrictions. These approaches have limits because the most advanced equipment remains difficult to replace.
YMTC's investment therefore depends on more than factory construction. The company needs an equipment supply chain that can operate at scale, produce reliable chips and support future improvements. Its focus on domestic tools connects those manufacturing requirements with China's wider push for local supply.
Why DRAM and high bandwidth memory are being considered
Chinese corporate registry filings show that the new entity supporting the third factory has about 20.7 billion yuan in registered capital. Industry accounts indicate that YMTC is evaluating whether part of the site could be allocated to DRAM development.
DRAM serves a different purpose from NAND. It supplies working memory for processors, while NAND provides persistent storage. High bandwidth memory, or HBM, is a stacked form of DRAM used alongside graphics processors and other accelerators to train and run large AI models.
Access to HBM has become a bottleneck in China following the new export controls. Domestic chip designers, including prominent cloud companies, want local supply options. A potential DRAM program at YMTC would connect the company's expansion to that need, although its established production business remains NAND.
HBM supply is dominated by three companies in South Korea and the United States. Their output is booked well in advance by customers buying AI accelerators. Chinese importers also face licensing barriers and longer delivery times.
Even a modest domestic supply effort would provide another option for Chinese AI servers, edge accelerators and research clusters. Edge accelerators handle AI work closer to where data is generated. The early market would likely consist mainly of Chinese customers able to qualify initial products while the technology develops.
Packaging skills could support a broader memory business
YMTC has been developing through silicon via, or TSV, packaging skills needed to stack DRAM chips into HBM. TSV technology creates connections through the silicon so the chips in a stack can communicate.
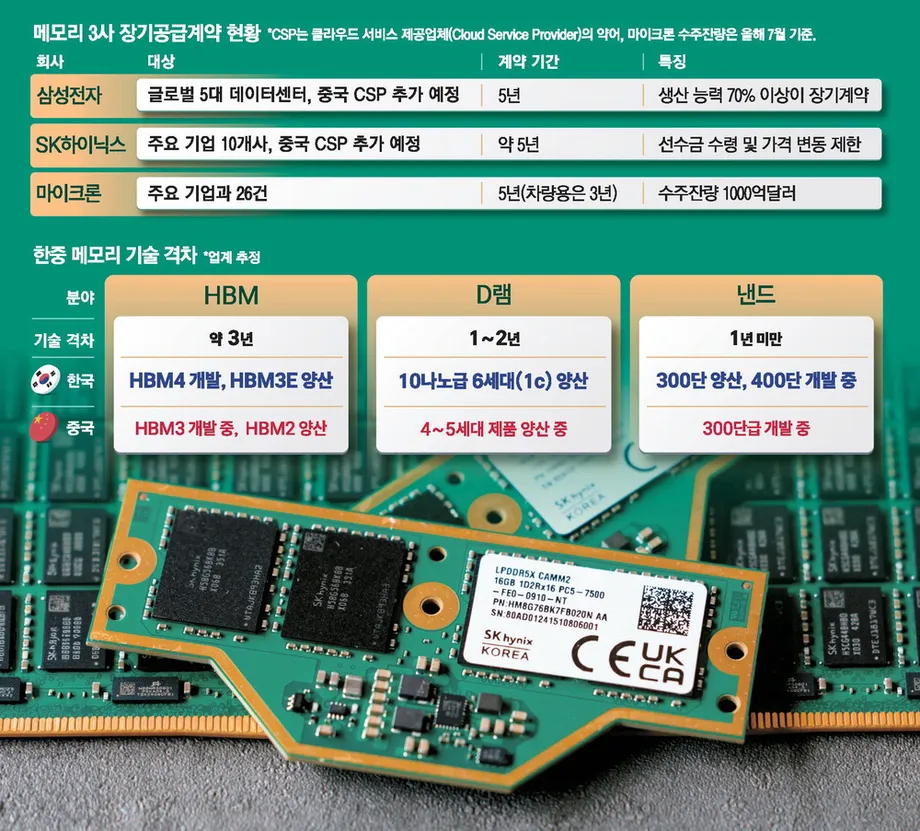
A possible collaboration with ChangXin Memory Technologies, known as CXMT and a leading Chinese DRAM producer, has also been discussed in industry accounts. CXMT has explored HBM2 and is moving toward HBM3 using domestic production lines. Chinese accounts point to 2026 to 2027 as a window for meaningful output.
YMTC brings experience in hybrid bonding from its Xtacking work. That expertise could help align stacked chips, create dense electrical connections and manage heat in HBM modules. These are demanding tasks because several memory chips must function together as a compact unit.
Tongfu Microelectronics and Wuhan Xinxin are among the Chinese companies expanding advanced packaging capacity to connect memory with processors. Their work forms part of the wider effort to build the components and assembly capabilities needed for domestic AI hardware.
YMTC's established NAND expertise, its work on TSV packaging and the possible DRAM allocation describe related development paths. The reported collaboration with CXMT remains a possibility, while the 2026 to 2027 output window concerns CXMT's HBM effort.
Who would buy the additional memory?
Most of YMTC's output is likely to remain in China. Large data center operators, domestic server and storage vendors, smartphone and personal computer makers, surveillance equipment providers and smart car platforms all consume substantial amounts of flash memory.
These customers are also under pressure to reduce exposure to imported components. More YMTC shipments through 2027 could allow them to replace imported NAND in solid state drives and embedded storage, where memory is incorporated into a device.
The shift could affect suppliers outside China even if YMTC exports little. When Chinese buyers purchase more domestic chips, their demand for foreign NAND can fall. That change could influence global pricing as producers compete for the remaining orders.
Data center sales require more than a supply of bare memory chips. YMTC also needs controllers, firmware and qualified module assembly. Controllers and firmware manage how a drive stores and retrieves information, while assembly turns components into a finished product that customers can test and approve.
Qualification by major Chinese cloud and server customers would therefore be an important sign of progress. Buyers need consistent performance and reliability, and the company's product mix must serve both consumer devices and enterprise systems.
The production and financial risks
Memory manufacturing is difficult to expand at a competitive cost. Advanced NAND contains hundreds of layers made within tight tolerances. Every percentage point lost in yield reduces the amount of saleable output and puts pressure on margins in a market where price competition is intense.
QLC adds another product challenge. Its storage density is useful, but enterprise customers must account for its endurance and performance trade offs when choosing drives. Stable chip production must be matched by dependable controllers, firmware and assembly.
Export policy remains a major risk. Rules can change, licenses can be revoked and additional categories of equipment can be placed under controls. Greater use of domestic tools reduces dependence on some foreign supplies, while also placing more demands on local equipment makers.
Memory prices move through cycles, making the timing of expansion financially important. Decisions taken in 2025 will meet market conditions about two years later. A factory intended to address strong demand can face weaker prices if supply grows faster than customer purchases.
YMTC's focus on Chinese customers reduces some exposure to foreign trade barriers. It still faces pressure to meet the quality and reliability standards established by incumbent suppliers. Construction progress, manufacturing yields and customer approvals will all determine how much usable supply the new site delivers.
The milestones leading to 2027
YMTC's expansion spans several years of product development, export restrictions and capacity investment. The key dates show how its established NAND business and possible move into other memory technologies fit together.
- December 2022: The United States placed YMTC on the Entity List.
- 2023: YMTC introduced the X3 9070, a QLC NAND chip with 232 layers and density of about 19.8 gigabits per square millimeter. The memory market also experienced a deep downturn.
- 2024: BIS added explicit controls on HBM. By the end of the year, YMTC's two Wuhan factories had capacity of about 160,000 wafers per month.
- 2025: YMTC planned to add roughly 65,000 wafers per month at its existing facilities. By December 16, construction of its third Wuhan factory had begun.
- 2026 to 2027: Chinese accounts identify this period as a potential window for meaningful CXMT HBM output.
- 2027: YMTC targets first wafers and mass production at its third Wuhan factory, followed by increasing volumes.
Customers and investors will first watch construction and clean room completion, followed by equipment installation and the proportion of tools made domestically. Pilot lines and early wafers during 2026 would offer progress markers before the targeted start in 2027.
Further signs include the first commercial products from the factory, announcements of NAND with more than 232 layers or a new Xtacking generation, and formal steps toward DRAM research, TSV packaging and trial HBM modules. Stable yields, partnerships with controller and SSD makers, and qualification by major cloud or server customers would show whether capacity is becoming dependable supply.
Key Points
- YMTC has begun building a third memory factory in Wuhan, targeting production in 2027.
- A new entity supporting the project has about 20.7 billion yuan in registered capital.
- Existing Wuhan capacity was about 160,000 wafers per month at the end of 2024, with another roughly 65,000 planned during 2025.
- United States restrictions are pushing YMTC toward greater use of Chinese manufacturing equipment.
- YMTC is evaluating DRAM development and building packaging skills relevant to HBM, with a possible CXMT collaboration discussed.
- Industry estimates place YMTC at 7 to 8 percent of global NAND capacity and below 5 percent of revenue.
- Domestic AI, cloud and device customers are the likely main buyers. Equipment readiness, yields, export rules, pricing and customer qualification remain the main constraints.