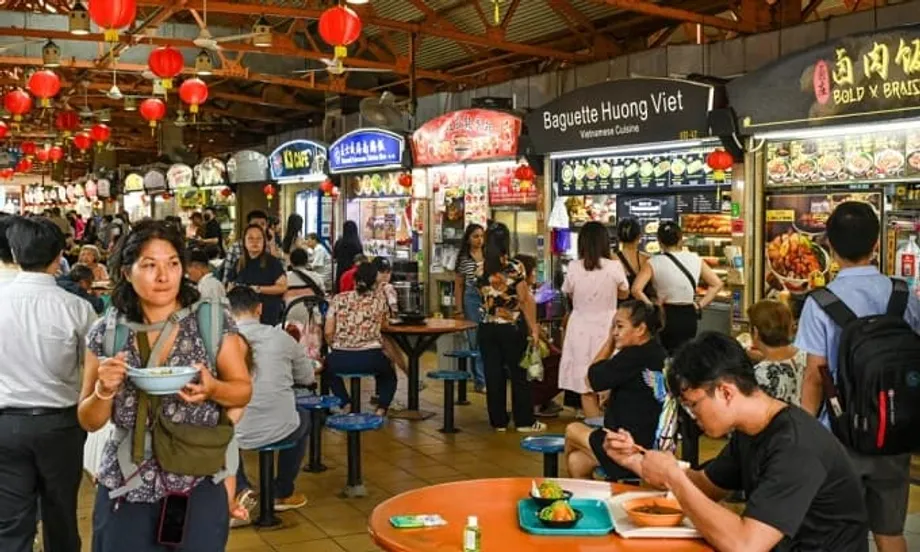
More openings, but many businesses never reached profit
Singapore recorded 2,431 food and beverage outlet closures between January and October 2025, with younger businesses accounting for most of the exits. Government figures shared in Parliament show that 63 percent of the businesses that closed had been registered for five years or less. Among that younger group, 82 percent had never posted a profit in their annual tax filings.
Contents
- More openings, but many businesses never reached profit
- How quickly are outlets closing?
- Why younger businesses struggle to survive
- Rent and staffing costs squeeze the same budget
- Diners are spending more cautiously
- Closures reach chains, acclaimed restaurants and local favourites
- New arrivals keep competition intense
- Policy and lease choices shape viability
- Catering and regular customers offer steadier income
- What neighbourhoods lose when familiar venues disappear
- What to Know
Those figures capture the financial difficulty behind a changing dining scene. Businesses are opening, competing for customers and disappearing, sometimes before they establish a reliable income. The closures reach from hawker stalls and casual chains to bars and restaurants with Michelin recognition.
Singapore also registered 3,357 new outlets during the same ten months, exceeding closures by 926. The city continues to attract entrepreneurs and international brands, even as existing operators struggle with higher rent, rising wages and more cautious spending.
Retail food establishments cover a broad range of businesses: restaurants, cafes, fast food chains, hawker centres, coffee shops, stalls selling cooked food and drinks, pubs, caterers and takeaway kiosks. The pressure therefore reaches far beyond conventional restaurants.
As of November 10, 2025, the picture is one of constant renewal alongside fragile finances. New concepts continue to arrive, but the profitability figures show how difficult it has been for many entrants to turn an appealing idea into a business that pays its bills.
How quickly are outlets closing?
Singapore had already recorded more than 3,000 closures in 2024, a level approaching the highest in almost 20 years. The monthly closure figure given for 2025 is about 307, compared with 254 in 2024 and roughly 230 in both 2023 and 2022.
The January to October total of 2,431, however, works out to about 243 closures a month. The reason for the difference between that calculation and the stated monthly figure of 307 was not given. Both figures belong to the account of the industry's turnover, but the ten month total provides the clearest count for that specific period.
The main developments span several years:
- 2022 and 2023: Closures averaged roughly 230 outlets a month.
- June 2023: Wine RVLT began operating at a loss, according to its cofounder Alvin Goh.
- 2024: More than 3,000 outlets closed, with a monthly average of about 254.
- June 2025: Ramen chain Kanada Ya exited Singapore after operating three shops.
- January to October 2025: Singapore registered 3,357 new food and beverage outlets and recorded 2,431 closures.
- November 10, 2025: Esora was due to close, while Alma by Juan Amador and Euphoria had announced closures.
Why younger businesses struggle to survive
New entrants are drawn by the chance to become their own boss and by Singapore's reputation as a food capital. The industry has relatively low barriers to entry compared with many other sectors. A small team can incorporate a company, sign a lease, recruit staff and open within months.
Opening quickly and becoming profitable are different tasks. Food, rent and manpower take up a large share of expenses, leaving little room for disappointing sales or unexpected bills. Before serving the first customer, an operator may already have paid for fitting out the premises, licences, deposits and marketing.
Many operators underestimate how much time and money they will need before customer traffic becomes steady. If sales fall below their forecasts, the savings set aside to keep the business running can disappear quickly.
Annual tax filings measure profit across a financial year, rather than a few busy weeks. The finding that 82 percent of the younger businesses that closed had never posted an annual profit suggests that many never reached a sustainable level of earnings, or enjoyed profitable trading only briefly before expenses overtook revenue.
Daily consistency adds another challenge. Operating six or seven days a week, often for long hours, requires reliable routines. Staff turnover can weaken service and food quality. Without regular customers and a clear reason for diners to choose the outlet, maintaining enough sales to cover recurring bills becomes difficult.
A rent or wage increase during a lease can push even a modestly profitable concept into losses. Passion may help an entrepreneur launch, but survival depends on reaching a repeatable business model quickly and controlling costs from the start.
Rent and staffing costs squeeze the same budget
Some operators report rent increases of 20 to 49 percent at renewal, describing them as the steepest in 15 to 20 years. As customer traffic returned to prime malls and office districts, landlords gained greater negotiating power and desirable locations again commanded a premium.
Businesses that signed leases when the market was softer have faced difficult renewal discussions. Rent must be paid even on quiet days, making a large increase particularly painful when revenue is already falling.
Manpower is the other major pressure. Salaries have climbed, while larger competitors can offer much higher pay to attract scarce workers. Training takes time, and turnover remains high in a demanding industry.
Hiring foreign workers brings further requirements, including levies, minimum salary conditions and quotas limiting the share of staff from overseas. Levies are charges employers pay for employing foreign workers; quotas restrict how many they can hire. Together, these rules affect both staffing choices and operating costs.
The Restaurant Association of Singapore has warned of a serious manpower crunch and urged a review of foreign worker quotas. For small outlets with uneven sales, meeting staffing needs while paying wages and other employment costs can be especially difficult.
Alvin Goh, cofounder of wine bar Wine RVLT, explained why he decided to end the business after almost a decade:
We've been in the red since 2023 June. We've been topping up money to ensure that rent, salaries and suppliers are being paid.
Wine RVLT's experience illustrates the strain of covering continuing losses with money from its owners. When fixed expenses keep rising and customer spending softens, a business can have little room to recover.
Diners are spending more cautiously
Restaurant owners report revenue declines of around 10 to 30 percent compared with earlier peaks. Customers are choosing cheaper meals or eating at home more often, while some discretionary spending has shifted toward travel and other experiences.
Official data showed a decline in restaurant receipts around the middle of 2025 compared with the same period a year earlier. That fits the weaker trading described by operators. Restaurant receipts measure sales coming into businesses; falling receipts leave less money available for wages, rent, ingredients and other bills.
Johor Bahru is also drawing Singapore residents across the Causeway. Comparable meals there can cost 30 to 40 percent less, making the trip attractive to households trying to stretch their budgets.
For Singapore outlets, money spent on meals across the border is spending that might otherwise have stayed locally. The planned Rapid Transit System between Woodlands and Johor Bahru is expected to increase travel across the border once it opens. Operators are watching how easier journeys could shape weekend meals and leisure dining in the coming years.
Closures reach chains, acclaimed restaurants and local favourites
International brands, restaurants with Michelin recognition, private clubs and longstanding neighbourhood businesses have all featured among the exits. The range shows that the pressure extends across different prices, cuisines and types of venue.
Several businesses had operated for many years before closing. Others were newer arrivals that had entered Singapore with considerable attention. The prominent names include:
- International chains: Burger & Lobster closed its last outlets at Raffles Hotel and Jewel Changi Airport. Eggslut shut its final location after entering Singapore with fanfare in 2021. The Manhattan Fish Market ended a run of nearly two decades when its last outlet closed.
- Casual dining: Kanada Ya exited in June after operating three ramen shops. Hokkaido Ramen Santouka closed its sole outlet after 17 years. Black Cow, an upscale Japanese restaurant serving hotpot and sukiyaki, closed after nine years.
- Fine dining: Esora, a modern Japanese restaurant with one Michelin star, was due to close after eight years. Alma by Juan Amador and Euphoria, both with Michelin recognition, announced closures. Poise and Imbue also left the scene.
- Clubs and bars: Private club 1880 closed after nearly eight years. Wine RVLT ended its nine year run.
- Heritage and neighbourhood businesses: Ka Soh ended an 86 year legacy. Dong Fang Hong Sotong Ball Seafood Soup shut after 45 years. Very Lucky Turtle Soup closed as its owners retired. Burp Kitchen & Bar, a bistro run by a family in Bishan Park, concluded after 11 years.
Retirement was the reason given for Very Lucky Turtle Soup's closure, while Wine RVLT's cofounder described sustained financial losses. The wider list contains businesses at different stages of life, from relatively recent concepts to establishments serving generations of customers.
The loss of familiar neighbourhood venues and celebrated restaurants within months of one another changes where people eat and gather. Its effects extend beyond restaurant rankings and guidebooks.
New arrivals keep competition intense
The 3,357 new registrations between January and October show that entrepreneurs continue to see opportunities. Openings outnumbered closures, keeping competition for workers, customers and suitable premises intense.
International brands still choose Singapore to test concepts or expand. Operators from mainland China have grown rapidly, particularly in hotpot and mala, while some concepts from the United States have arrived through franchise partners. Local groups are also introducing venues ranging from eateries focused on value to restaurants intended as destinations in their own right.
Distinctive hospitality and value remain important attractions. Jay Gray, a restaurateur who opened a new venue in 2025 and has launched several projects over the past decade, explained his continued confidence:
I guess I believe in the Singapore market enough and I do believe if you focus on hospitality, which is the most important thing, you'll be able to sustain it.
Businesses combining a clear identity, consistent service and a sensible cost structure can still grow. The room for error, however, is smaller than during the rebound after COVID-19 restrictions eased.
Policy and lease choices shape viability
The Restaurant Association of Singapore's call to review foreign worker quotas places staffing policy at the centre of the industry's concerns. Operators seeking relief from recruitment difficulties also face the need to protect job quality for resident workers.
Space costs present another difficult calculation. Experienced operators often aim to keep rent below 20 percent of total costs. That means limiting rent to less than one fifth of what the business spends, a target that can be hard to achieve in central locations with the most customer traffic.
Some businesses are choosing smaller premises, units on the second level of buildings, or a mix of dining on site and delivery. These approaches seek to make premises costs more manageable while reaching customers through more than one route.
Some landlords are considering arrangements that take a share of revenue and shorter commitments in selected cases. A revenue share model ties at least part of the landlord's payment to business takings. The negotiating position of tenants and landlords still varies between malls and districts.
Technology and training offer another way to manage staffing demands. Ordering kiosks, QR payments at tables, central kitchens and shorter menus can reduce the work required without weakening service. Government support schemes exist for digital tools and skills upgrading, and operators using them early often manage staff numbers more effectively.
A central kitchen brings preparation into one location instead of repeating the same tasks at every outlet. Such changes can help a viable business withstand pressure, although the underlying concept still needs enough customers and a workable balance between income and expenses.
Catering and regular customers offer steadier income
Catering grew 17.8 percent in the second quarter of 2025, supported by demand from events and corporate customers. That gave some restaurants an opportunity to earn beyond their dining rooms.
Some operators now reserve resources for catering and delivery to stabilise sales when fewer customers eat on the premises. Central kitchens can support this approach by bringing preparation together and reducing duplicated work across outlets.
Businesses holding their ground tend to pay close attention to lease terms and location risk. They keep menus focused to limit waste and variation, build a recognisable brand and develop a community of regular customers.
Reliable routines matter throughout the working day, from preparing food and serving customers to checking that payments and accounts match. These systems help maintain consistent quality across different shifts.
Marketing and loyalty efforts are also becoming more targeted. Incentives for ordering ahead, menus for quieter periods and partnerships with nearby businesses can help fill spare capacity while preserving a restaurant's identity.
Value is a strong attraction when households are watching their spending. Consistency matters too: customers who know what to expect are more likely to return, reducing the amount a business must spend to attract each new diner.
What neighbourhoods lose when familiar venues disappear
Cafes, hawker centres and casual eateries serve as meeting places outside home and work. These are sometimes called third places, where people gather informally and maintain everyday connections.
When a longstanding stall or neighbourhood restaurant closes, customers lose more than a menu. They can also lose a familiar place to meet, while the city's culinary memory becomes narrower as distinctive businesses disappear.
The concern is that tougher economics may favour large chains and standardised concepts able to spread costs across more outlets and use automation. Independent operators can find it harder to absorb the same increases in rent and wages.
Chains can also provide quality food at prices that help households, and new concepts can add variety. Singapore's challenge is to maintain that renewal while retaining heritage businesses and independent creators whose different approaches make the dining scene distinctive.
The closure and opening figures show both sides of this change. Thousands of entrants are still willing to try, while thousands of businesses are leaving. The financial strain falls on operators, but the changing mix of venues also shapes the daily lives of the communities around them.
What to Know
- Singapore recorded 2,431 food and beverage outlet closures and 3,357 new registrations between January and October 2025.
- Businesses registered for five years or less accounted for 63 percent of closures. Among that group, 82 percent had never posted an annual profit in tax filings.
- The stated monthly closure figure for 2025 was 307, compared with 254 in 2024 and roughly 230 in 2023 and 2022. The ten month total averages about 243 a month.
- Some operators reported rent increases of 20 to 49 percent and revenue declines of around 10 to 30 percent from earlier peaks.
- Rising salaries, staffing shortages, foreign worker levies, salary requirements and quotas added pressure. The Restaurant Association of Singapore sought a quota review.
- Meals in Johor Bahru can cost 30 to 40 percent less than comparable options in Singapore, attracting spending across the border.
- Closures affected international chains, restaurants with Michelin recognition, bars, private clubs, heritage eateries and neighbourhood businesses.
- Catering grew 17.8 percent in the second quarter of 2025, supported by events and corporate demand.
- Operators are managing costs through lease discipline, focused menus, technology, central kitchens and efforts to retain regular customers.