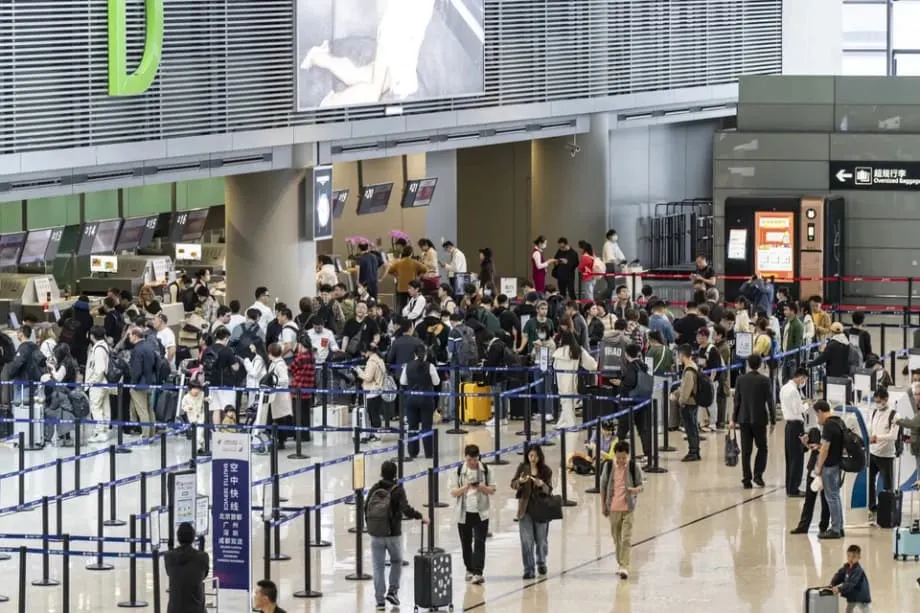
A busy summer brings profits, but cheap seats limit the recovery
China's three largest state airlines earned a combined 11.51 billion yuan in the third quarter of 2025, yet their recovery still faces a basic problem: more passengers do not necessarily mean stronger earnings. International tickets for Chinese travelers remain between 22 percent and 34 percent cheaper than in 2019 on many routes, helping fill aircraft while limiting the revenue airlines collect from each seat.
Contents
- A busy summer brings profits, but cheap seats limit the recovery
- What the third quarter results reveal
- Holiday fares rise, then the low season returns
- Why crowded aircraft can still earn too little
- International seats return unevenly
- A larger winter network brings more competition
- Beijing's airports show where airlines are expanding
- Cheaper fuel helps, but global margins remain thin
- Debt repair and fleet renewal compete with expansion
- What travelers and investors should watch
- Key Points
Air China reported quarterly net profit of 4.14 billion yuan, China Southern Airlines earned 3.84 billion yuan and China Eastern earned 3.53 billion yuan. The summer surge provided relief after all three remained in the red during the first half of the year. Since 2020, their combined losses have reached about 206 billion yuan.
As of October 31, the challenge is to carry that summer recovery through the quieter months. Domestic fares rose during the National Day holiday, then fell again in mid October. Airlines are also preparing to expand international services during the 2025 to 2026 winter spring season, adding seats to a market where pricing is already under pressure.
Chinese travelers have become more sensitive to prices amid a slower domestic economy, a prolonged property slump and cautious consumer spending. Many search for cheaper flights or choose rail when the journey is competitive on time and cost. Discounting helps airlines attract those passengers, but weak passenger yields, the ticket revenue collected per passenger per kilometer, make it harder to rebuild profits as quickly as traffic.
What the third quarter results reveal
China Southern, the country's largest airline by fleet and passenger numbers, reported record quarterly revenue of 51.4 billion yuan. Its third quarter net income rose 20 percent from a year earlier to 3.84 billion yuan, showing how strongly the summer travel season can lift business.
Air China's quarterly profit of 4.14 billion yuan was slightly lower than a year earlier. China Eastern returned to profit with 3.53 billion yuan after three consecutive quarters of losses. Together, the results show a broad seasonal improvement, although each airline entered the summer with a different recent earnings record.
The third quarter is typically the strongest period for Chinese carriers. Families travel during school holidays, and higher demand helps airlines sell more seats. A profitable summer can still be followed by a loss for the full year if earnings are too weak during other seasons.
Analysts have said the three airlines could finish 2025 in the black if autumn and winter losses remain contained. No full year result was yet available on October 31. Weak yields and intense competition remain the main pressures on that prospect.
Holiday fares rise, then the low season returns
During the week long National Day holiday, average domestic fares for travel in one direction rose to about 910 yuan, roughly 10 percent above a year earlier. The increase showed that airlines could charge more when large numbers of passengers wanted to travel at the same time.
From October 13 to 19, average domestic fares fell to about 768 yuan, roughly 12 percent below the previous month's level. Flight frequencies also slipped after the holiday. The movement from holiday prices into the high 700 yuan range illustrates how quickly demand and pricing can cool.
The main stages of the year's recovery show why one strong quarter is only part of the earnings picture:
- First half of 2025: China Southern, Air China and China Eastern all remained loss making as yields lagged.
- Third quarter of 2025: All three reported profits during the strongest seasonal period for Chinese airlines.
- National Day holiday: Average domestic fares reached about 910 yuan, roughly 10 percent above a year earlier.
- October 13 to 19: Average domestic fares dropped to about 768 yuan as the market entered low season.
- 2025 to 2026 winter spring season: Airlines planned further network growth, including new international connections.
Airlines therefore need to manage both sides of the seasonal cycle: earning enough during busy periods and limiting losses when demand weakens. Sustained profitability depends on what passengers will pay beyond the summer peak.
Why crowded aircraft can still earn too little
Passenger yield measures ticket revenue for each passenger and each kilometer flown. It helps airlines compare earnings across journeys of different lengths. A flight can be crowded while producing disappointing revenue if most passengers bought heavily discounted tickets.
Chinese airlines added capacity quickly to capture returning demand. Capacity means the seats available for sale, rather than the number of travelers who actually fly. When airlines offer seats faster than passengers are willing to buy them at stronger prices, carriers compete more aggressively for bookings.
Many travelers continue to search for bargains. High speed rail and low cost airlines also compete strongly on short and medium distances. Together, these forces keep yields soft, particularly on domestic routes and regional international services that were among the first to reopen and expand.
Private low cost rivals pushed into leisure markets and returned to profit earlier than the three large state airlines. Their lower costs allow them to compete differently from full service carriers. When they set low prices on popular leisure routes, larger airlines often match the discounts to protect their share of passengers, pulling yields down across the market.
High speed rail adds another source of pressure on many major domestic routes. Where train journey times are competitive, passengers have a practical alternative to flying. Airlines must consider that choice when setting fares, especially after holiday demand fades.
Falling fares become a financial problem when revenue declines faster than costs. Filling an extra seat helps, but the airline still has to pay for fuel, aircraft and operations. That explains why traffic recovery and profit recovery can move at different speeds.
International seats return unevenly
International capacity to and from China has recovered to roughly 85 percent of 2019 levels. Services to North America, however, remain below one third of activity before the pandemic, amid diplomatic frictions and tight bilateral limits governing flights between countries.
Airlines have put more seats into shorter routes across Northeast and Southeast Asia, where traffic has been easier to restore. The resulting concentration of capacity has increased competition and weakened pricing on popular routes between cities.
Travel between China and South Korea illustrates the problem. Capacity on that corridor has recovered to about 105 percent of its level before the pandemic, compared with roughly 85 percent for China's international market. Visa waivers and the return of tour groups have helped lift passenger numbers.
Analysts caution that more travelers on those routes do not automatically translate into higher profits. Group travel is highly sensitive to price, and airlines tend to discount heavily when available seats exceed demand at stronger fares.
The uneven recovery also shapes where travelers can find bargains. Domestic markets outside major holidays and parts of Northeast and Southeast Asia have abundant capacity. China to North America remains constrained, so the deepest discounts are expected to remain concentrated elsewhere.
A larger winter network brings more competition
The Civil Aviation Administration of China expects about 119,500 passenger and cargo flights each week during the 2025 to 2026 winter spring season, a slight increase from a year earlier. International services are expected to rise by more than 10 percent, with more than 21,000 international flights.
Passenger services operated by 191 airlines will connect China with 83 countries. Cargo routes will reach 49 countries. The expansion extends beyond rebuilding familiar routes, with passenger flights to India set to resume after a halt lasting five years.
Carriers are also adding passenger links to Oman and Argentina, while cargo connections are expanding to Panama, Chile and Switzerland. These changes broaden the destinations available to travelers and businesses.
China's leading hubs are handling a growing share of international passenger flights. At the same time, airlines are spreading their networks across more regional destinations. Beijing's two major airports show how carriers are combining established hubs with new connections.
Additional routes improve connectivity and can create demand over time. They also increase the number of seats for sale immediately. Until enough passengers arrive to fill those seats at worthwhile prices, network growth can continue to hold fares down.
Beijing's airports show where airlines are expanding
China Southern has launched a service from Beijing Daxing International Airport to Doha. China Eastern plans to open a direct route to Muscat and add flights to Bali, Phu Quoc, Kobe and Sapporo, extending its reach across several leisure and regional markets.
Air China intends to operate 452 routes during the winter spring season, including 127 international and regional routes. Its plan calls for about 1,725 flights daily and a 13 percent increase in capacity compared with the previous winter spring schedule.
At Beijing Capital International Airport, He Yawei, a senior official at the airport's operation control center, described expectations for steady growth and explained how new routes would expand the airport's destination network:
We are expecting stable growth this season, with new routes to Tbilisi and Abu Dhabi bringing our total destinations to 212.
The expansion gives passengers more choices and airlines more markets to serve. For carriers trying to restore profits, the financial outcome will depend on how quickly demand grows and how much passengers pay, alongside the number of destinations on the route map.
Cheaper fuel helps, but global margins remain thin
The International Air Transport Association (IATA) projects global airline net profits of about 36 billion dollars in 2025 on record revenue near 979 billion dollars. Those figures put expected profit at about 3.7 percent of revenue, illustrating how little of the industry's sales is expected to remain as net earnings.
IATA expects jet fuel prices to fall about 13 percent compared with 2024. Fuel is one of airlines' largest expenses, so that decline offers relief. Passenger load factors, the share of available seats occupied, are projected to reach a record 84 percent.
Competition and lower fuel costs are also expected to feed through into cheaper tickets. IATA projects passenger yields will fall about 4 percent in 2025. For Chinese airlines, a reduction in ticket revenue can absorb part of the benefit from lower fuel spending.
Willie Walsh, IATA's Director General, described how the industry's headline profit translates into a small amount for each passenger on each flight segment:
While a 36 billion dollar profit sounds large, it equals about 7.20 dollars per passenger per segment. That leaves airlines sensitive to new taxes, higher charges or a demand shock.
Cargo revenue is also expected to soften compared with the peaks of the previous two years. Protectionist trade measures are weighing on cargo yields, adding pressure to a business that can otherwise help airlines balance changes in passenger demand.
Sustainable aviation fuel production is set to double, but it will still supply only a tiny fraction of total fuel use and remains more expensive than conventional jet fuel. The global aircraft order backlog exceeds 17,000 jets, while delivery delays are slowing plans to modernize fleets.
Debt repair and fleet renewal compete with expansion
Air China has announced plans for an A share private placement to raise up to 20 billion yuan, with the aim of repaying debts and strengthening its capital. A private placement raises money by selling shares to selected investors, rather than through a sale open to everyone.
The planned fundraising reflects the need to repair airline finances after years of losses. Stronger capital and lower debt would give Air China more room to invest in efficient aircraft and add capacity where routes can earn a return.
China Eastern's early role as launch customer for the C919 narrow body jet points to gradual renewal using domestically produced aircraft. New aircraft can improve costs per unit of flying on major routes over time, although the pace of that renewal depends on production slots.
Fleet decisions sit alongside immediate cost pressures. Lower fuel prices can support earnings in 2025, while delivery delays restrict how quickly carriers can replace aircraft. Airlines must balance spending on future efficiency with the financial repair required after the losses accumulated since 2020.
What travelers and investors should watch
Travelers are likely to find good deals during low season and on routes with plentiful capacity, particularly in parts of Northeast and Southeast Asia. Fares often rise around Golden Week and winter holidays, then ease again. Passengers able to travel outside peak periods or during the middle of the week should continue to see broad availability below 2019 prices in many markets.
Investors are looking beyond passenger totals toward the quality of revenue. Passenger yields, restraint in adding seats on routes with too much capacity, the balance between longer international flights and regional services, and progress in reducing debt are key measures of the recovery.
Revenue beyond the basic fare can help cushion weak ticket pricing. Extra legroom seats and partnerships involving branded credit cards offer additional income, with stronger loyalty programs giving airlines more opportunities to develop that business.
Cargo can provide seasonal support during the shipping peak near the end of the year, especially for electronics, although its pricing is cooling from earlier highs. The summer results show strong travel demand. Turning that demand into sustained profits requires better pricing, careful route planning and continued cost control.
Key Points
- International fares for Chinese travelers remain 22 percent to 34 percent below 2019 prices on many routes.
- China's three largest state airlines lost about 206 billion yuan combined since 2020 and remained in the red during the first half of 2025.
- Third quarter profits reached 4.14 billion yuan at Air China, 3.84 billion yuan at China Southern and 3.53 billion yuan at China Eastern.
- China Southern recorded quarterly revenue of 51.4 billion yuan, with net income rising 20 percent from a year earlier.
- Domestic fares averaged about 910 yuan during National Day week and about 768 yuan from October 13 to 19.
- International capacity is about 85 percent of 2019 levels, compared with 105 percent on China to South Korea routes and less than one third on North American services.
- The winter spring schedule calls for about 119,500 weekly flights, including more than 21,000 international services.
- IATA projects global airline profit of about 36 billion dollars in 2025, with fuel prices down about 13 percent and passenger yields down about 4 percent.
- Air China plans to raise up to 20 billion yuan to repay debt and strengthen capital.