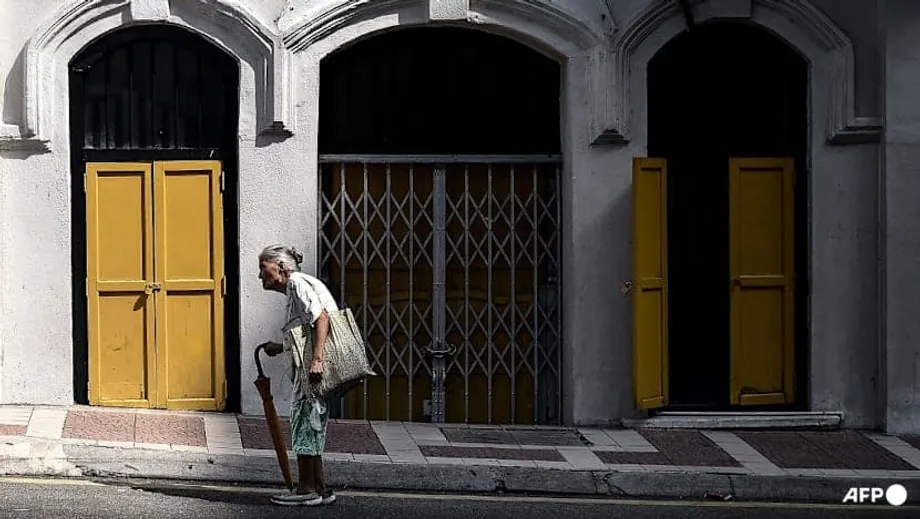
More older Malaysians, too little income support
Malaysia is heading towards a future in which one in five people will be aged 65 or older, yet fewer than one in ten people in that age group currently receive a targeted social pension. The World Bank is urging the country to expand support before rapid population ageing leaves more older Malaysians struggling to pay for basic needs.
Contents
- More older Malaysians, too little income support
- What a social pension does
- Who qualifies for Bantuan Warga Emas?
- Why retirement savings run short
- Why the Bank proposes later access ages
- Expanding coverage while protecting purchasing power
- What the budget and poverty figures show
- Lessons from other countries and choices at home
- The dates and delivery decisions that matter
- Key Points
Bantuan Warga Emas, the main assistance scheme for older people, reaches about 4 percent of seniors. Malaysia's social pension coverage is among the lowest anywhere, falling far below regional peers and global averages. Existing payments are modest and reach a narrow share of the older population.
The country is already an ageing society. Its pace of demographic change now matches the rapid transitions seen in China and Japan. Projections put the share of people aged 65 and above at 14 percent by 2045 and about 20 percent by 2056. Within a generation, the country will need to support a much larger population of senior citizens.
The World Bank's policy paper describes a widening gap between that demographic reality and the support currently available. It calls for a broader, more predictable safety net and warns that insufficient income protection could contribute to a crisis in elderly care.
The World Bank, which sets out the reform proposals in its policy paper, summarises the problem this way:
Malaysia's population is aging rapidly, but its social pension coverage and adequacy are relatively low.
The government's Budget 2026 sets aside 1.26 billion ringgit for senior welfare, with about 180,000 people expected to benefit. That represents a growing commitment to income security in old age, but current commitments still cover only a fraction of the need.
What a social pension does
A social pension is a payment financed by the government for older people who qualify by age, income, or both. Unlike a pension built through contributions from wages, it does not require recipients to have paid into a retirement scheme during their working lives.
That makes social pensions especially relevant to people who spent years in informal work, earned too little to save regularly, or reached retirement with savings that will not last. The payment provides a minimum income when earnings and other support are insufficient.
International evidence described in the World Bank study shows that even modest social pensions can reduce poverty, narrow inequality and improve the well being of recipients and their extended families. They also help households keep paying for everyday needs when illness or job loss affects relatives who support an older person.
Malaysia's two main forms of cash support reach very different shares of the older population. Bantuan Warga Emas reaches about 4 percent of seniors, while Sumbangan Tunai Rahmah, a broader cash transfer for people with low incomes, is received by about 60 percent of older people.
For most older households, the combined value of those transfers typically amounts to less than a tenth of income before the payments are added. A household may therefore receive assistance while still depending heavily on work, savings or relatives to meet its expenses.
Thailand's old age allowance reaches almost nine in ten seniors, providing a predictable minimum income regardless of work history. The Philippines and Vietnam each cover close to three in ten. Those figures show how narrow Malaysia's targeted social pension coverage remains compared with nearby countries.
Who qualifies for Bantuan Warga Emas?
Bantuan Warga Emas pays 600 ringgit a month into the bank accounts of eligible senior citizens to help with basic living expenses. It targets Malaysians aged 60 and above who have no fixed income or pension and whose households fall below the official poverty line.
Applicants cannot be living in government welfare institutions or receiving overlapping assistance. Those conditions, together with the narrow income test, limit how many older people the programme reaches.
Some older Malaysians have small savings that soon run out. Others earn money informally, but not enough to cover rising costs. People with few assets or high medical expenses may also fall outside the programme's eligibility rules despite facing financial hardship.
Household income tests can miss difficulties within families that include several generations. An older person may live in a household whose combined income exceeds the threshold while having little money available for their own needs.
The World Bank argues that eligibility thresholds need to reflect the real cost of decent living. It also calls for payments to rise automatically with inflation, so the amount of food, transport and other essentials a benefit can buy does not shrink as prices increase.
Bantuan Warga Emas and Sumbangan Tunai Rahmah also need a clearer shared policy purpose. Without better coordination, older people can be left relying on a patchwork of small payments. Gaps in support are likely to widen over time if benefit values and eligibility rules remain unchanged.
Why retirement savings run short
Nearly half of Employees Provident Fund members who reached age 55 in 2023 had less than 10,000 ringgit saved. The World Bank estimates that about 250,000 ringgit is needed to maintain a basic standard of living in retirement.
The Employees Provident Fund, or EPF, has a strong investment record and remains central to Malaysia's retirement system. Yet many members contribute irregularly or stop contributing when they move into informal employment. Only about 42 percent of the working age population contributes to any formal pension arrangement.
Early withdrawals during the COVID-19 period reduced many balances further. Savings are often depleted within three to five years after withdrawal, leaving a long stretch of later life without sufficient money from the fund.
EPF withdrawals are permitted at age 55. Many people therefore draw down their savings before they stop working or before they qualify for other support in old age. The resulting gap is especially difficult for women and workers on low wages.
Adult children remain an important source of support for many older Malaysians. Family sizes, however, have fallen, and more seniors now live alone or in households made up only of older people. That leaves fewer relatives available to share the cost of daily living and care.
Why the Bank proposes later access ages
The World Bank recommends gradually raising the EPF withdrawal age into the range of 65 to 70. Keeping savings invested for longer would allow more time for compounding, the process in which investment returns themselves earn further returns, and could improve retirement income.
The Bank also proposes raising the eligibility age for social pensions to at least 65, with future adjustments linked to life expectancy. Its argument is that longer and healthier lives make it possible to reconsider age rules while extending assistance to more people.
A later eligibility age, combined with wider coverage, could create room for higher average payments without putting excessive pressure on public finances. The proposals involve two different parts of retirement protection: when people can access their own EPF savings and when they can begin receiving a government social pension.
Working longer can raise concerns about whether older employees will take jobs that would otherwise go to younger people. The World Bank examined Malaysian labour market data and concluded that employment opportunities for the two groups can grow together.
The World Bank's conclusion on the relationship between longer working lives and jobs for younger people is:
Therefore, extending working lives should not be seen as a threat to youth employment.
Older and younger workers tend to bring different skills. Firms can benefit from experience alongside new ideas, supporting growth in the economy and employment for both groups.
Expanding coverage while protecting purchasing power
The World Bank recommends beginning the expansion of social pensions with older people in the lowest 40 percent of households by income. This would extend protection beyond the narrow group currently reached while directing public money towards those with fewer resources.
Updating income thresholds is another part of the proposed reform. A threshold is the income limit used to decide who qualifies. Revising it to reflect living costs would help the system respond to what households actually need to maintain a decent standard of living.
Automatic indexation would address a different problem: the value of payments after someone qualifies. Linking benefits to inflation would preserve their purchasing power instead of leaving recipients dependent on occasional decisions to increase the amount.
The Bank also calls for better targeting and public databases that can work together. Sharing relevant information between systems could make eligibility decisions more timely and accurate, reduce exclusion and limit the need for older people to approach several agencies to prove their circumstances.
These changes form a sequence intended to balance protection, fairness and the cost to the government. Wider coverage, updated income rules, payments that keep pace with prices and age thresholds linked to life expectancy would work together to build a stronger minimum income in old age.
The World Bank says financing must be designed carefully and that reforms can be introduced in stages to manage costs and public expectations. Its policy paper states:
Fiscal sustainability is key, but expansion is possible with targeted design and revenue reforms.
What the budget and poverty figures show
Budget 2026's allocation of 1.26 billion ringgit for senior welfare is expected to support around 180,000 older Malaysians. The allocation does not yet represent an expanded social pension, although it signals greater attention to financial security in later life.
The World Bank's modelling indicates that an expansion designed carefully would reduce poverty among older people and inequality across the population. Those effects would grow as seniors account for a larger share of Malaysians.
Data from the Household Income and Expenditure Survey shows relative poverty rising with the age of household heads. The figures are around 24 percent for households headed by people aged 60 and above, 42 percent for those aged 65 and above, and 49 percent for those aged 70 and above.
Relative poverty describes having an income that is low compared with the wider population. These figures show why a higher entry age would need to be accompanied by a substantial expansion in coverage: older households face increasing financial pressure, and assistance must reach those most at risk.
Cost control depends on the combination of eligibility, coverage and payment levels. Widening access while raising the entry age could allow higher average benefits within a sustainable budget. Protecting existing recipients while applying a higher age to new entrants could make the transition smoother.
No date is given for implementing the proposed expansion or changes to access ages. The policy choices therefore remain recommendations, alongside the government's stated Budget 2026 commitment.
Lessons from other countries and choices at home
China and India have built social pensions that now reach large numbers of rural residents and informal workers. Across Latin America, modest transfers in old age have been associated with lower poverty and better health outcomes for seniors and their families.
Thailand illustrates the reach of a near universal allowance. A universal benefit is available broadly across the eligible age group, making it simpler and more inclusive, but it requires more public money. A means tested benefit concentrates spending on people judged to be in greater need, but depends on reliable information and effective administration.
Many countries adjust payments with inflation. Others also connect eligibility ages to life expectancy to keep their systems financially stable as people live longer. Malaysia can draw on these approaches while taking account of its available public funds and administrative capacity.
Raising eligibility ages remains politically and socially sensitive. Policymakers need to balance the speed of reform, the adequacy of support and public trust, even as Malaysians live longer and healthier lives than when current rules were set.
Expanding coverage at the same time, protecting current recipients from adverse changes and explaining how payments will keep pace with inflation could help maintain that trust. A transparent indexation rule would also give families greater certainty when planning for later life.
Income protection needs to develop alongside health care and care services for older people. A new assisted living project backed by Retirement Fund Inc in Kepala Batas, Penang, shows how housing and care can evolve alongside financial support to meet the needs of seniors with low incomes.
The dates and delivery decisions that matter
Malaysia's challenge stretches from today's savings shortfalls to a much older population within a generation. The key dates and projections show the scale of that transition:
- 2023: Nearly half of EPF members reaching age 55 had less than 10,000 ringgit saved.
- 2026: The government budget allocates 1.26 billion ringgit for senior welfare, expected to benefit about 180,000 people.
- 2045: People aged 65 and above are projected to make up 14 percent of the population, taking Malaysia into aged society status by the middle of the 2040s.
- 2056: The share aged 65 and above is projected to reach about 20 percent, or one in five people.
The National Ageing Agenda provides a policy platform for strengthening retirement security before population ageing accelerates further. Priorities identified by the World Bank include expanding coverage to the lowest 40 percent of households, setting a formula for indexation, updating income thresholds and planning a gradual rise in eligibility age tied to life expectancy.
Delivery will matter as much as the rules. Stronger outreach could help older people apply early and avoid interruptions in support. Better connected databases could reduce exclusion and simplify eligibility checks.
Regular monitoring of benefit adequacy, take up and poverty by age would show whether the reforms are reaching people and providing enough support. Independent evaluations could guide later adjustments to programme rules.
A stronger social pension would complement the EPF and civil service pensions. Its role would be to fill the gap for people who reach old age with little or no savings, and for those whose retirement money runs out before the end of their lives.
Key Points
- Fewer than 10 percent of Malaysians aged 65 and above receive a targeted social pension; Bantuan Warga Emas reaches about 4 percent of seniors.
- Bantuan Warga Emas pays eligible recipients 600 ringgit a month, while Sumbangan Tunai Rahmah reaches about 60 percent of older people.
- Malaysia's population aged 65 and above is projected to reach 14 percent by 2045 and about 20 percent by 2056.
- Nearly half of EPF members reaching age 55 in 2023 had less than 10,000 ringgit, compared with the Bank's estimated retirement requirement of about 250,000 ringgit.
- Only about 42 percent of the working age population contributes to a formal pension arrangement.
- The World Bank recommends wider social pension coverage, beginning with the lowest 40 percent of households, and benefits linked to inflation.
- The Bank proposes social pension eligibility from at least age 65 and a gradual rise in EPF withdrawal age to between 65 and 70.
- Budget 2026 allocates 1.26 billion ringgit for senior welfare, expected to support about 180,000 people.