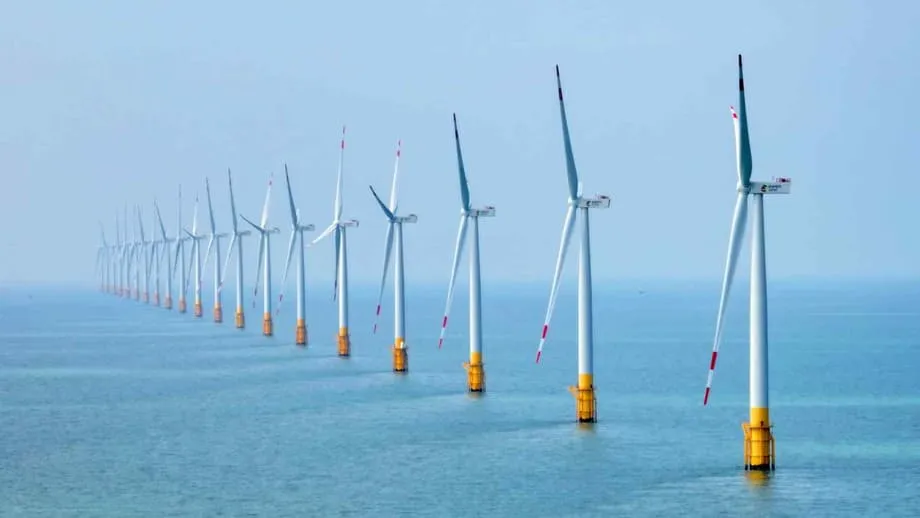
China's coastal expansion puts it at the center of global growth
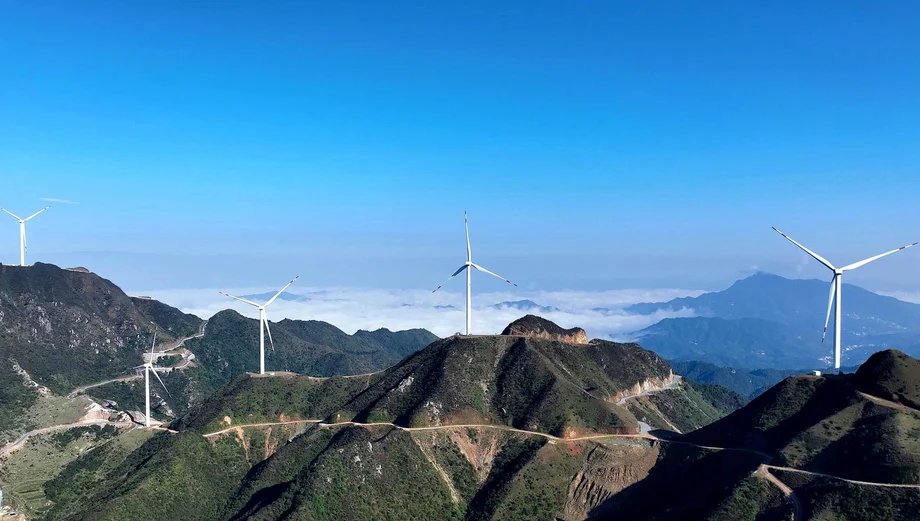
China is expected to account for about half of the world's new offshore wind capacity through 2030, while one leading energy consultancy projects that it could hold around 45 percent of all offshore wind capacity operating worldwide by that year. Provincial ambitions include Guangdong's plans for 23 offshore wind farms totaling about 66.9 gigawatts and a 1.5 gigawatt project that national oil company CNOOC aims to commission off Hainan before 2030.
Contents
- China's coastal expansion puts it at the center of global growth
- What the global capacity figures show
- How policy and factories keep projects competitive
- Provincial plans stretch from Jiangsu to Hainan
- United States setbacks and Europe's investment reset
- Shanghai puts offshore wind to work underwater
- From a 24 megawatt phase to a larger ambition
- The resource is vast, and the grid must keep pace
- Deeper waters bring new engineering choices
- What needs to happen through 2030
- Key Points
As of October 28, 2025, those forecasts place China at the center of the next wave of construction for a technology that many governments see as essential to clean electricity and energy security. State support, inexpensive turbines from domestic manufacturers and a deep pipeline of projects along the eastern seaboard are driving the expansion.
China's momentum contrasts with a less consistent picture elsewhere. Inflation, higher interest rates and project cancellations have slowed some markets. China's established supply chain, manufacturing scale and policy continuity have helped keep costs competitive, while grid operators connect coastal wind farms to regions with heavy industry and growing digital infrastructure.
Offshore wind is also becoming a source of electricity for coastal technology clusters, including advanced manufacturing and data centers. Shanghai's Lin gang Special Area offers a concrete example: the first phase of an underwater data center has about 24 megawatts of power capacity and is designed to run almost entirely on electricity from nearby offshore wind farms.
Industry demand, government targets and domestic manufacturing reinforce one another. Developers have customers that need electricity, planners have large coastal projects to advance, and suppliers have the factories and components needed to build them.
What the global capacity figures show
The world's operating offshore wind fleet reached roughly 83 gigawatts by the end of 2024, after 8 gigawatts were connected during that year, according to international industry tallies. A gigawatt is a measure of generating capacity. Electricity actually produced depends on how often turbines operate and the strength of the wind.
Government auctions awarded a record wave of future capacity, and nearly 50 gigawatts of projects are already under construction worldwide. Auctions allow governments to select developers and set terms for projects and their electricity. An award starts a development process that still requires construction and a grid connection.
Forecasts point to annual offshore wind installations rising from single digits in the middle of the 2020s to about 34 gigawatts in 2030. Compared with the 8 gigawatts connected in 2024, that would mean annual additions more than quadrupling. The projected expansion explains why factories, ports and electricity networks will need to grow alongside the project pipeline.
China has been the largest offshore wind builder for several years. By the middle of 2023, it already had more than 31 gigawatts operating offshore, more than any other country. Near term growth is concentrated in China and Europe, while Japan and South Korea are advancing policy frameworks and grid upgrades for projects expected later in the decade.
The two forecasts for China's position measure different things. About half of new additions refers to the capacity built during the period through 2030. Around 45 percent of cumulative capacity refers to China's share of everything operating worldwide by 2030, including older projects.
If global annual installations reach the low to middle 30 gigawatts and China continues adding capacity at a double digit gigawatt pace each year, other regions can expand while China retains a large share. Both forecasts point to Chinese construction playing a central role in global wind targets.
How policy and factories keep projects competitive
China's energy planners have used five year plans, auctions and grid connection mandates to guide investment. That policy clarity matters because offshore wind projects can take several years to build and connect. Stable rules help developers and lenders assess financing risks across that period.
Recent policy changes encourage renewable electricity prices to be set through markets. The aim is to improve bankability, meaning a project's ability to secure financing, while giving developers incentives that better match the needs of the electricity grid. Prices can help encourage electricity use or storage when wind generation is abundant.
Global wind factories could produce roughly 170 to 180 gigawatts of equipment in 2023, with China serving as the main manufacturing hub. That industrial footprint includes blades, towers and nacelles, the housings for equipment at the top of turbines, alongside a growing supply of offshore foundations and cables.
Chinese turbine manufacturers have introduced larger machines. More capacity from each turbine can reduce the number of units a wind farm needs, lowering installation and maintenance costs per megawatt. Developers also benefit from improvements in project design, installation vessels and port logistics, allowing them to obtain more capacity for each yuan invested.
Competition among domestic turbine makers, a dense network of component suppliers and proximity to coastal construction sites help keep prices low. Shorter development timelines and established ports capable of handling increasingly large components also reduce costs. Together, these advantages tighten auction bids and help projects proceed despite a tougher global financing environment.
Those savings feed into the levelized cost of electricity, a measure of the full cost of building and operating a power plant over its lifetime, spread across the electricity it produces. China's cost advantage has widened as some Western markets face higher interest rates and currency volatility.
Provincial plans stretch from Jiangsu to Hainan
About three quarters of China's operating offshore wind capacity is concentrated in Jiangsu, Guangdong and Fujian. The project pipeline now extends farther north and south, with major plans in Zhejiang and Shandong and new activity off Hainan Island.
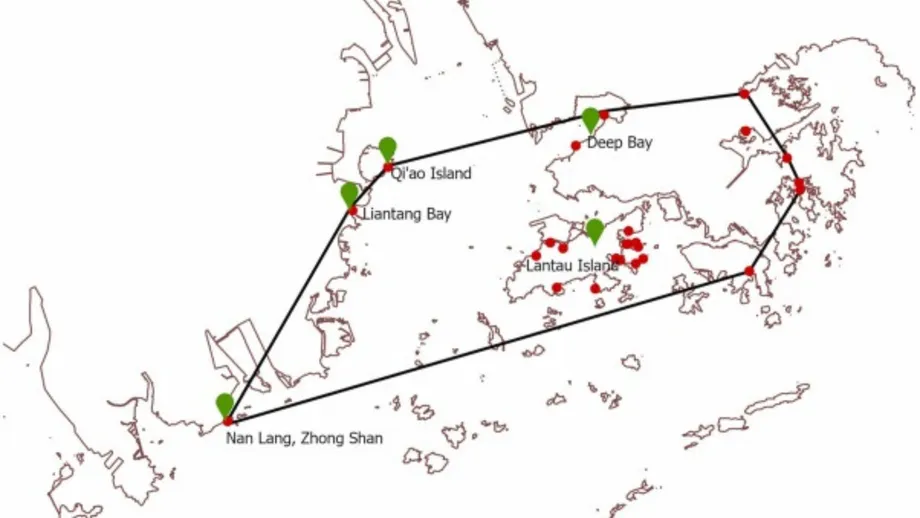
Guangdong's ambitions are especially large. Provincial planning documents and academic assessments indicate plans for 23 offshore wind farms totaling about 66.9 gigawatts by 2030. Guangdong is a major manufacturing and technology hub near strong wind resources in the South China Sea, giving developers access to both a substantial resource and large electricity customers.
Earlier blueprints designated Fujian, Shandong, Zhejiang and Jiangsu as offshore wind power bases through 2025, each with prospective capacity measured in multiple gigawatts. CNOOC is also increasing its involvement, with a 1.5 gigawatt project in Hainan's CZ7 zone targeted for commissioning before 2030.
Guangdong's planned expansion would supply clean electricity to industrial clusters and businesses that depend on data processing. Delivering it requires strong grid connections, storage that can shift electricity to hours when it is needed, including at night, and coordinated ports that can maintain a steady flow of large components.
The main milestones span several years:
- By the middle of 2023, China had more than 31 gigawatts of offshore wind operating.
- By the end of 2024, global offshore wind capacity reached roughly 83 gigawatts, including 8 gigawatts connected that year.
- Through 2025, earlier Chinese blueprints identified several coastal provinces as offshore wind power bases.
- During 2026 to 2030, industry targets call for China to add at least 15 gigawatts of offshore wind capacity each year.
- Before 2030, CNOOC aims to commission the 1.5 gigawatt Hainan CZ7 project.
- By 2030, Guangdong's plans point to about 66.9 gigawatts across 23 offshore wind farms.
United States setbacks and Europe's investment reset
The United States, once expected to expand offshore wind rapidly, has faced policy reversals, rising costs and legal challenges. Stop work orders affected prominent projects in the Northeast before some restrictions were lifted. Renewable energy investment fell sharply in early 2025, and developers reassessed their exposure to the US market.
Those setbacks slowed construction and weakened confidence in near term auctions. Offshore projects require substantial spending before electricity sales begin, making changes in construction permissions, borrowing costs and expected revenue important to investment decisions.
European investors have redirected capital and sought more predictable rules following failed auctions and cost spikes. Policymakers are also trying to reduce reliance on imports from China by supporting domestic factories for blades, nacelles, towers and cables.
A sizeable share of the manufacturing sites producing key components for Western turbine platforms is located in China. Moving that production quickly is difficult without raising costs for consumers. Governments must balance the price of equipment with quality and the ability to keep supplies flowing when individual factories or transport routes face problems.
A more geographically diverse manufacturing network would reduce bottlenecks, while China's breadth of production makes it difficult to replace quickly. Governments are expected to adjust auction rules so developers and electricity buyers share risks more evenly, and to fund ports, grids and workforce training that support construction schedules.
Shanghai puts offshore wind to work underwater
Shanghai's Lin gang Special Area connects offshore wind with another rapidly growing electricity user: digital infrastructure. Its first underwater data center phase has about 24 megawatts of power capacity and is designed to operate almost entirely on electricity from nearby offshore wind farms.
Server modules are submerged in the sea, using the surrounding water for cooling and sharply reducing the electricity needed for air conditioning. Data centers produce heat as their computers operate, so cooling is a major part of keeping equipment running reliably.
Su Yang, general manager of Shanghai Hicloud Technology, one of the contractors, explained how the marine setting reduces cooling demand.
Seawater acts as a natural cooling system, which reduces the energy demand for cooling to less than 10 percent.
The system is designed for a power usage effectiveness of no more than 1.15. This measure compares a facility's total electricity consumption with the electricity used by its computing equipment. At 1.15, total consumption is 1.15 times the computing load, with the remainder going to cooling and other supporting functions. Typical facilities on land often rely heavily on air conditioning.
Huang Dinan, president of Shenergy Group, another contractor, described the local wind resource and its value for operations.
The East China Sea offers unique offshore wind resources with more than 3,000 hours of annual utilization.
From a 24 megawatt phase to a larger ambition
The Shanghai project partners have signed an agreement to pursue a much larger underwater data center powered by wind, with capacity of about 500 megawatts. That is roughly 21 times the 24 megawatts in the first phase, showing the scale of the proposed expansion.
Moving from a pilot to a system at that scale will require careful engineering and lessons from operation. Offshore wind is increasingly connected with data centers and industrial parks that need low carbon electricity around the clock, putting reliable power supply and reliable equipment at the center of development.
Wang Shifeng, president of Third Harbor Engineering, said wider deployment depends on improving operations and proving reliability.
For broader deployment, operation and maintenance optimization, as well as technological reliability, must be achieved first.
No completion date was given for the proposed 500 megawatt development. The agreement sets an ambition, while the operational work described by Wang is the next practical step toward expanding it.
The resource is vast, and the grid must keep pace
Researchers estimate that China's offshore wind resources have the technical potential to generate around 17.5 petawatt hours of electricity annually, more than twice the country's current national electricity consumption. Technical potential describes what the resource could produce within technical limits; actual development depends on building projects and connecting their output to customers.
Research also projects that development through the middle of the century could avoid coal use and reduce annual emissions in coastal regions by roughly 294 million tons of carbon dioxide equivalent. Carbon dioxide equivalent expresses the warming effect of different greenhouse gases using a common measure. The projected reduction is greater than the total annual emissions of most countries.
Transmission lines, upgraded substations, digital controls and storage are needed to bring large volumes of offshore wind onto the grid. Curtailment occurs when electricity that turbines could generate is left unused because the network or demand cannot absorb it. Moving power efficiently and storing it for later use can reduce that waste.
China's move toward market based renewable electricity pricing can reward flexible demand and storage that smooth changes in wind generation. International agencies expect renewables to take a steadily larger share of the electricity mix through 2030, with wind becoming a leading source after solar power.
Deeper waters bring new engineering choices
Most Chinese offshore turbines stand on foundations fixed to the seabed in relatively shallow water. Floating platforms offer a way to reach deeper seas with stronger winds, expanding the areas where developers could build beyond shallow continental shelves.
Floating wind remains a small part of global capacity, measured in the hundreds of megawatts. Several Chinese developers and research institutes are testing designs. Lower costs as production grows could make deeper offshore zones more accessible.
State backed developers are moving from waters near the shore toward deeper areas, while oil and gas companies are entering the market through large projects such as Hainan CZ7. Grid operators are investing in new subsea links and stronger networks on land to carry electricity into urban and industrial centers.
What needs to happen through 2030
The global industry is expected to connect more than 30 gigawatts of offshore wind in 2030, with annual growth recovering after cost pressures. Developers and governments are redesigning auctions to distribute risks more evenly, adjust contract prices as costs change and secure power purchase agreements that support financing over many years.
Ports, cable factories and installation vessels must keep pace with those plans. In China, provincial pipelines point to another construction wave in Guangdong, Jiangsu, Fujian, Zhejiang, Shandong and Hainan. Meeting the industry target of at least 15 gigawatts of new offshore capacity annually during 2026 to 2030 would make China a continuing anchor of global construction.
Higher interest rates and shortages of equipment or components can raise bid prices. Transmission delays can hold back new capacity, while rules requiring locally produced equipment may increase costs in some markets even as they build domestic skills. Improvements in turbine design, foundations and operations offer ways to contain spending.
China's position through the end of the decade rests on converting its extensive pipeline into operating wind farms, supported by manufacturing and electricity networks. If projects stay on schedule, the combination of coastal demand, policy continuity and competitive equipment costs will keep the country at the center of offshore wind expansion.
Key Points
- China is forecast to deliver about half of new global offshore wind capacity through 2030 and hold around 45 percent of cumulative capacity by that year.
- Global offshore wind capacity reached roughly 83 gigawatts in 2024; annual installations are forecast to reach about 34 gigawatts in 2030.
- Guangdong plans point to 23 offshore wind farms totaling about 66.9 gigawatts by 2030.
- CNOOC targets commissioning of the 1.5 gigawatt Hainan CZ7 project before 2030.
- Chinese industry targets call for at least 15 gigawatts of new offshore capacity annually during 2026 to 2030.
- United States projects face policy and cost pressures, while Europe seeks more predictable investment rules and domestic manufacturing.
- Shanghai's underwater data center has an initial power capacity of about 24 megawatts, with partners pursuing a larger development of about 500 megawatts.
- Research projects possible annual emissions reductions of roughly 294 million tons of carbon dioxide equivalent in coastal China by the middle of the century.
- Grid upgrades, storage, ports, cables and installation vessels are essential to turning project plans into usable electricity.