Seven years of restrictions, and a widening Chinese response
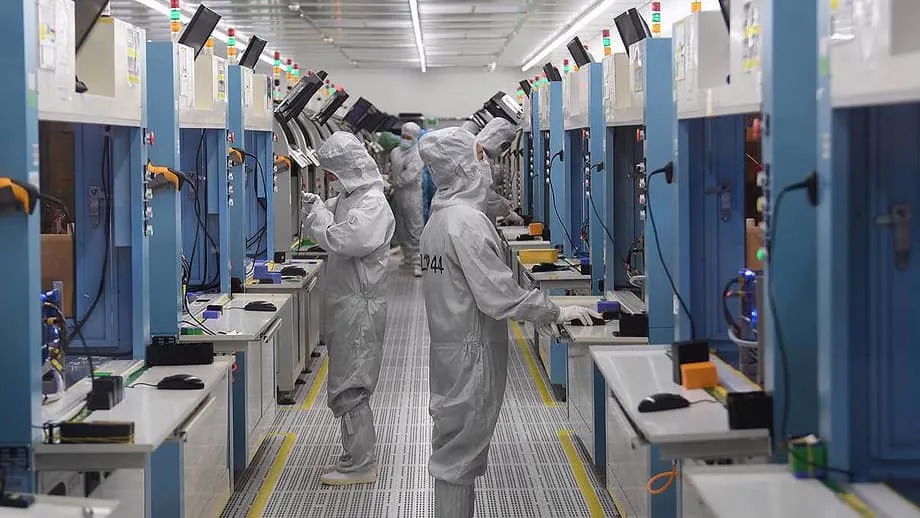
China's semiconductor industry has spent seven years adapting to tighter American restrictions on chips, design software and factory equipment. By October 24, 2025, that pressure has helped drive a much broader domestic effort: Huawei and SMIC are pursuing advanced processors, local governments are financing equipment and packaging, and Chinese AI companies are building software around domestic computing systems.
Contents
- Seven years of restrictions, and a widening Chinese response
- How Washington expanded the restrictions
- Why factory tools are a tighter pressure point
- Beijing sets priorities while cities compete
- SMIC pursues smaller chips with older equipment
- Memory and design software become strategic priorities
- AI companies build around domestic processors
- The gaps that still limit production
- American suppliers face lost sales and changing rules
- What policy choices and production results will decide
- Key Points
Washington's objective was to deny China the most advanced semiconductors and the means to manufacture them, slowing progress in artificial intelligence, high performance computing and military systems. The restrictions have disrupted supply chains, raised costs and limited access to powerful processors. They have also pushed Chinese companies to replace imported technology across almost every stage of chip production.
The outcome is a contest over both technical capability and industrial scale. Producing an advanced chip is one challenge. Making enough reliable chips at an affordable cost, with dependable equipment and software, is another. China's progress in design, memory and manufacturing sits alongside continuing weaknesses in lithography, inspection, advanced memory and production efficiency.
Semiconductors power cloud data centers, phones, cars, factory robots and weapons systems. That breadth explains why governments treat access to chips and the machinery behind them as a strategic asset. China still depends on foreign technology at the leading edge, while American companies and allied suppliers risk losing customers in the world's largest chip market.
The next stage turns on two connected questions: how far China can scale its domestic alternatives, and how the United States can refine restrictions while strengthening its own research and manufacturing base.
How Washington expanded the restrictions
American controls developed in successive waves, moving from restrictions on individual companies toward broader limits on computing power, manufacturing equipment and the technologies used to design chips.
- 2018 and 2019: Early measures placed Chinese companies on the Entity List, requiring licenses for access to US technology.
- 2022: Washington widened restrictions to advanced AI processors, graphics processing units used in data centers and key chipmaking equipment.
- 2023 and 2024: Further measures added equipment categories and Chinese entities, while restrictions expanded to high bandwidth memory, design software and cloud access for training AI models.
- Early 2025: Washington introduced a tiered framework differentiating access by country and company. Some proposals sought to limit shipments to a long list of nations.
The Foreign Direct Product Rule extended the reach of American controls beyond US companies. It brought certain chips designed with American software or manufactured using American tools within the restrictions, even when the companies making them were elsewhere.
US graphics processor suppliers responded by designing chips with lower performance for China that could meet the rules. Later revisions closed some of those openings. Products developed for one set of thresholds could become restricted under the next, leaving suppliers and customers facing another round of adjustments.
The Netherlands and Japan also coordinated with Washington on controls covering advanced manufacturing equipment. Restrictions affecting lithography, deposition and etching created pressure at particular stages of production. Lithography forms the tiny patterns used to build chips; deposition adds material, while etching removes selected portions.
American toolmakers faced license delays and less visibility into future business in a market that had accounted for a large share of sales. Repeated changes also made it harder for customers to plan purchases, upgrades and factory expansion.
Why factory tools are a tighter pressure point
Finished chips are small and can move through intermediaries or third countries. Factory equipment is much larger and requires installation, maintenance and continuing technical support. Those differences make equipment harder to smuggle and easier to monitor.
Chinese buyers have used intermediaries and friendly jurisdictions to reroute some advanced components. Enforcement must therefore follow changing trading routes as well as changing technology. Each revision to the rules produces new efforts to comply, adapt or get around the restrictions.
Lithography and certain deposition and etching tools have become especially effective pressure points because advanced manufacturing depends on them. Access to a processor can help a buyer run an AI system; access to production equipment can help a manufacturer build many generations of processors.
Cloud computing presents another enforcement problem because companies can obtain computing capacity remotely. Entity lists, licensing procedures and oversight of shipments through third countries all require continuing updates. The practical reach of restrictions depends on enforcement as well as their wording.
Beijing sets priorities while cities compete
China's response combines national coordination with competition among local governments, private companies and state investors. The aim is to build a nearly complete domestic industry for mature and intermediate manufacturing processes, while pushing selected advanced technologies through alternative methods and substantial investment.
Beijing reorganized science and technology management to centralize funding and oversight in strategic fields, including semiconductors. A leading group chaired at vice premier level sets priorities. The National IC Industry Investment Fund and city funds support equipment, materials and advanced packaging, the processes used to connect and protect chips inside a finished component.
Shenzhen launched a fund spanning several years for chip design, equipment and packaging. Shanghai backed equipment ventures and larger private equity funds focused on local companies. Hangzhou and Hubei also made major commitments, including programs tied to memory manufacturer YMTC.
Competition among cities draws investment and engineers into local projects, speeds the development of pilot production lines and puts pressure on companies to meet technical milestones. National priorities set the direction, but much of the practical work takes place through these local contests.
China's research output in semiconductor design and manufacturing has also surged. Teams are investigating different materials and chip architectures, alongside efforts to reproduce capabilities already established by leading Western and Asian manufacturers.
Wei Shaojun, who leads the integrated circuit design branch of China's main semiconductor association, described the industry's response as a combination of domestic capability and continued international engagement:
The more others suppress us, the more we need to be self reliant. But self reliance does not mean self isolation.
SMIC pursues smaller chips with older equipment
SMIC has produced chips in the 7 nanometer class using deep ultraviolet lithography, known as DUV. These systems predate the more advanced extreme ultraviolet equipment, or EUV, used at the manufacturing frontier.
DUV multi patterning uses repeated patterning steps to create smaller features than a simpler process would allow. It gives engineers a route toward denser chips with existing equipment, but the extra work takes time and increases costs.
SMIC is reported to be pushing toward denser manufacturing processes while working around limits in line width control and yield. Yield is the proportion of manufactured chips that work properly. When fewer usable chips emerge from a production run, the cost of each working chip rises.
Chinese designers are also turning to chiplets and advanced packaging. A chiplet approach joins several smaller pieces of silicon, known as dies, within one module. It provides a way to improve performance without putting every function onto a single large die.
Process improvements and packaging therefore address different parts of the same problem. Smaller features can fit more circuitry onto silicon, while better connections among multiple dies can improve the performance of the complete system. Both require engineering work, investment and reliable production.
Research teams are exploring less conventional options too, including logic devices based on carbon nanotubes. Such experiments may take considerable time to reach mass production, but they give China possible routes beyond simply following existing manufacturing methods.
Memory and design software become strategic priorities
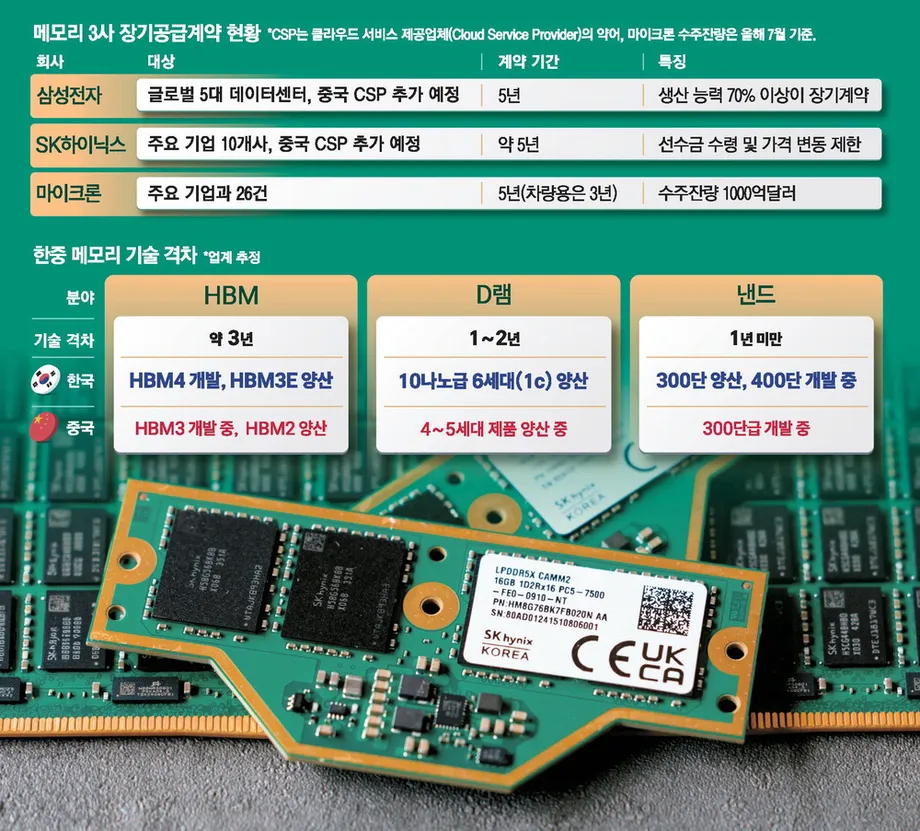
YMTC has advanced in three dimensional NAND memory, shipping products with layer counts near the top of the global industry. Stacking more layers increases storage density, which matters for phones and data centers as well as China's domestic supply security.
Chinese manufacturers of DRAM and specialty memory have also improved, supported by state investment and a growing base of domestic equipment suppliers. Progress in storage, however, sits alongside continuing difficulty in securing the most advanced high bandwidth memory used in AI systems.
High bandwidth memory supplies data rapidly to powerful processors. An AI accelerator needs both computing capacity and a fast flow of data, making this memory a critical part of the complete machine.
Chip design houses under Huawei's umbrella and other Chinese companies are developing AI accelerators using established instruction sets and open alternatives such as RISC V. An instruction set defines the basic commands a processor understands.
Restrictions on leading Western electronic design automation software have increased investment in domestic alternatives. These tools, usually called EDA, help engineers design circuits and check whether they will work before manufacturing begins.
Chinese developers are building software for placing and connecting circuit elements, verifying designs and designing analog circuits. Limited access to the most advanced EDA features slows the journey from a design to a finished product and makes verification more difficult. Equipment, software and manufacturing therefore have to advance together.
AI companies build around domestic processors
Chinese cloud companies, AI startups and processor designers have formed alliances as access to leading American graphics processors has tightened. An industry group launched in Shanghai to promote domestic processors for AI training reflects the effort to build a shared software and hardware foundation.
Huawei's Ascend processors are a focal point. Companies are adapting frameworks, compilers and model development tools to Ascend and other domestic accelerators. These software layers translate the work an AI developer wants to perform into operations the hardware can execute efficiently.
Prominent Chinese AI developers say they have trained large models on domestic computing clusters. AI company iFlytek described its latest reasoning model as an example of that shift:
Our Spark X1 model was trained on China's own computational infrastructure.
DeepSeek demonstrated a different kind of adaptation, presenting a large language model with a surprisingly low reported computing budget. Its approach drew on more efficient data selection, training schedules and methods for running a trained model, a stage known as inference.
Some DeepSeek claims remain debated. The wider development is a stronger focus on extracting more performance from less powerful or intermediate hardware through software, data pipelines and model design.
Training large AI models has become the main driver of demand for advanced chips. That demand gives domestic accelerator companies potential customers and gives software developers a reason to support their hardware. If local processors become competitive in particular tasks, purchasing decisions and software development could shift faster together.
The gaps that still limit production
Lithography remains China's most visible weakness. ASML is the sole supplier of EUV systems, and those machines are unavailable to Chinese factories. Domestic lithography manufacturer SMEE is improving in mature and intermediate processes but remains far behind in the most advanced scanners.
Manufacturers also need the right supporting tools and photoresists, the materials used to transfer patterns during lithography. Without the full range of allied equipment and materials, achieving reliable yields at advanced processes remains difficult.
Taiwan and Korea retain a strong lead in cost per wafer and throughput, or the amount a factory can process in a given time. Advanced processes built around repeated DUV patterning are expensive and difficult to scale compared with competing production using EUV.
China has leading companies in etching and deposition, but gaps persist in metrology, inspection and photoresists. Metrology measures whether features have been made correctly; inspection looks for defects. Weakness at any of these stages adds time, expense and uncertainty to the entire production line.
Domestic accelerator software also trails the libraries and development tools built over many years around American chips. Better processors still need dependable software support before customers can use them efficiently across many workloads.
China has many engineers, yet experience in building and operating the most advanced factories at large scale remains concentrated in a small number of companies. The head of a leading Chinese etching equipment supplier framed the effort to catch leading global competitors as a task measured in years:
Give us five to ten years, and we will stand with the best.
The timetable for closing all these gaps remains uncertain. Production yields, volumes, equipment reliability and software maturity will determine how quickly individual advances become an industry capable of meeting demand.
American suppliers face lost sales and changing rules
US chip designers have lost access to major sales opportunities as restrictions have expanded. Changing performance thresholds and long licensing processes make planning harder, particularly when a product created specifically for China later falls outside revised limits.
Some suppliers have been left with inventory in limbo. Equipment manufacturers have experienced strong demand in friendly markets while losing visibility into Chinese service contracts and upgrades. The consequences reach beyond initial shipments because factories depend on continuing support.
Nvidia chief executive Jensen Huang described the change in his company's position after Washington expanded restrictions:
China is essentially closed to us now. We went from almost the entire market to zero.
Huang also pointed to the broader strategic cost of losing access to the world's largest AI market. For American suppliers, fewer sales can mean losing part of the customer base that supports research and production scale.
Chinese competitors gain an opening when imported products become unavailable. Domestic purchases give local chip designers and equipment makers more opportunities to expand production, reduce costs and improve performance over time.
The commercial pressure therefore runs in both directions. Restrictions interrupt China's access to advanced technology, while the resulting demand for substitutes helps Chinese suppliers develop. Broad controls can also encourage customers outside China to consider Chinese products.
What policy choices and production results will decide
Washington faces a tradeoff between slowing China's progress at the technological frontier and preserving the markets that support American suppliers. A policy approach discussed in the debate combines precise restrictions, stronger enforcement on factory equipment and closer allied coordination with investment in US research, workers and manufacturing.
China has responded through countermeasures involving critical minerals and by encouraging the use of domestic EDA software and semiconductor equipment. Longer restrictions give companies more reason to make lasting changes to suppliers and production plans.
Equipment controls can buy time where EUV and advanced inspection systems have few alternatives. American investment in semiconductor research centers, grants for new factories and programs attracting global talent affects what the United States builds during that period.
Several practical measures will show how the contest is developing: yields and production volumes for Chinese chips in the 7 nanometer class and denser processes; domestic high bandwidth memory and packaging capability; and the quality of compilers, frameworks and libraries supporting local AI accelerators.
Enforcement against shipments through third countries and remote cloud access will also matter, alongside allied coordination on equipment and servicing restrictions. US decisions about market access will continue to shape the business case for domestic investment on both sides.
China's expansion in mature and intermediate processes, combined with selected advances in packaging and complete computing systems, could allow it to meet much of its own demand and compete in overseas markets where price matters most. Tighter allied equipment controls and stronger investment in their own industries could help the United States and its partners retain leadership in the most advanced manufacturing processes and tools.
Key Points
- US controls expanded from company restrictions in 2018 and 2019 to advanced processors, manufacturing tools, memory, software and cloud access.
- China is combining national coordination, local investment and company alliances to develop domestic alternatives.
- SMIC has produced chips in the 7 nanometer class using DUV equipment, while chiplets and advanced packaging provide other routes to better performance.
- YMTC has advanced in NAND storage, but leading lithography, high bandwidth memory, design tools and production yields remain difficult areas.
- Huawei Ascend, domestic software development and more efficient AI models are central to China's computing response.
- American suppliers face lost sales as Chinese buyers shift toward local alternatives.
- Production scale, costs, software quality, enforcement and investment will determine how far the changes go.