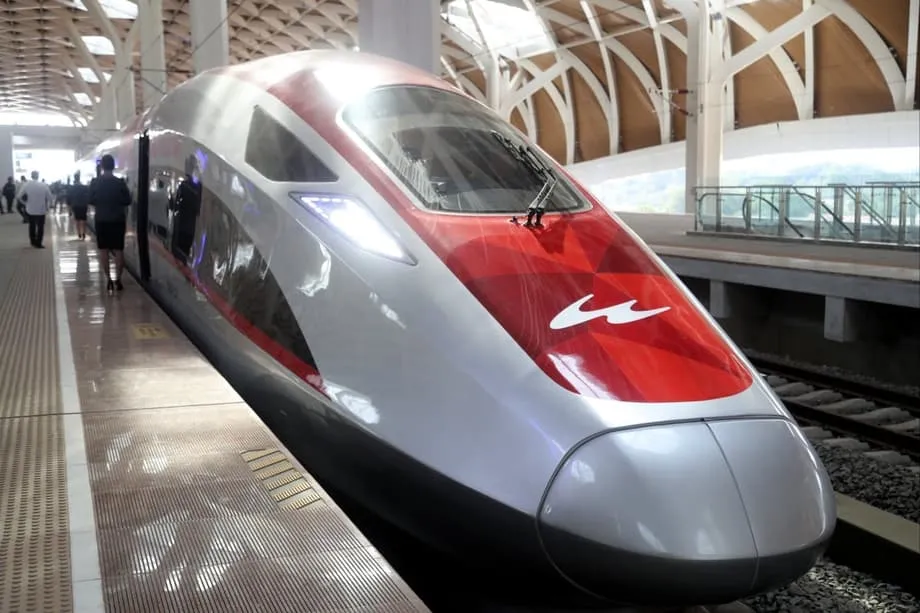
Who pays for a railway costing $7.27 billion?
Indonesia is refusing to use its state budget to pay the mounting debts of Whoosh, the high speed railway between Jakarta and Bandung, while China has signaled willingness to discuss restructuring. As of October 23, 2025, the government wants the financial burden handled by state enterprises and Danantara, the new sovereign wealth fund that manages their operations and dividends.
Contents
- Who pays for a railway costing $7.27 billion?
- Restructuring is the government's preferred route
- How construction costs became a debt burden
- The companies carrying the losses
- Danantara is weighing two ways to intervene
- More passengers have not yet closed the gap
- What China could agree to change
- How the financial pressure developed
- The Surabaya extension remains part of the debate
- Other regional rail projects show similar pressures
- What taxpayers and commuters stand to gain or lose
- The next decisions will shape the railway's finances
- At a Glance
The dispute concerns a railway whose construction cost rose from an initial estimate near $6 billion to about $7.27 billion. Its operator, PT Kereta Cepat Indonesia China (KCIC), recorded a loss of about 1.6 trillion rupiah in the first half of 2025, even as passenger numbers grew. Officials want to keep trains running while changing how the debt is repaid.
Finance Minister Purbaya Yudhi Sadewa, who oversees fiscal policy and the state enterprise dividend framework, says responsibility belongs with Danantara. The fund manages the operations and dividend flows of roughly 1,000 state firms. Purbaya argues that an institution receiving their profits should also take responsibility for their liabilities.
Purbaya put that position directly, pointing to the approximately 80 trillion rupiah in dividends that Danantara had taken over:
Whoosh is already managed by Danantara. Danantara has already taken over about 80 trillion rupiah in dividends from state owned enterprises. They should just manage it from there. Using the state budget to pay Whoosh's debt is a bit ridiculous. All the SOEs' profits go to Danantara, but the burden comes our way. If Danantara takes the dividends from SOEs, they should take everything, including the debt burden.
The government faces two connected tasks: easing the railway's repayment burden and deciding where that burden should sit. Keeping it within state companies avoids direct budget payments, but still commits money held by public institutions.
Restructuring is the government's preferred route
Luhut Binsar Pandjaitan, chair of the National Economic Council and a key coordinator on strategic projects, also rejects using the state budget. He says the answer is a formal restructuring with lenders and has indicated that a presidential decree is expected to authorize a negotiation team.
Luhut described the government's position after consultations with Beijing:
The real problem is only restructuring, and no one has ever asked to use the state budget for that.
Restructuring means changing the agreed repayment terms. A lender might allow more years to repay, reduce an interest rate or introduce a grace period before certain payments begin. Those changes can give a borrower more room to meet its bills while revenue grows.
China's openness to talks could allow a longer repayment schedule, lower interest on the loan covering construction cost overruns or new grace periods. The immediate objective for both sides is to preserve service while restoring financial stability. No final restructuring terms or date for an agreement had been given.
How construction costs became a debt burden
Whoosh began commercial service in October 2023. The 142 kilometer railway reduces travel between Jakarta and Bandung from around three hours to roughly 40 minutes at peak speed. The faster journey is the central benefit for passengers, but the construction bill has created a continuing financial challenge.
Delays, difficulties acquiring land and disruptions during the pandemic pushed the estimated cost from near $6 billion to about $7.27 billion. China Development Bank financed roughly 75 percent of construction through loans. The original loan tranche, meaning a portion of the financing with its own terms, carried annual interest of 2 percent.
An additional loan covered the agreed cost overrun of roughly 18 trillion rupiah. Its interest rate was higher, at 3.4 percent, increasing the annual cash needed for financing. The combined interest bill tied to the bank's loans was estimated at roughly $121 million a year before repayments of principal, the amount originally borrowed.
The project used a business to business financing structure. A joint venture borrowed the money and built the railway, while Indonesian state enterprises supplied equity through their companies and holding structures. Equity is money invested in exchange for ownership, rather than money lent with a repayment schedule.
This arrangement limited explicit state budget exposure at the outset. It also placed substantial risk inside state companies, which now have to support a railway whose revenue is still insufficient to meet its full operating and financing burden.
The companies carrying the losses
KCIC is a joint venture with a majority Indonesian stake held through PT Pilar Sinergi BUMN Indonesia (PSBI). The Indonesian group comprises railway operator Kereta Api Indonesia (KAI), construction company Wijaya Karya, toll road company Jasa Marga and plantation company PTPN VIII.
The Chinese partners include state railway and engineering companies that supplied technology, construction and rolling stock, the trains used on the line. KCIC relied on China Development Bank loans for roughly three quarters of the project's cost, followed by the additional borrowing for the construction overrun.
Company filings and official briefings put KCIC's loss in the first half of 2025 at about 1.6 trillion rupiah. KAI absorbed approximately 951 billion rupiah through its shareholding. PSBI recorded losses of around 4.2 trillion rupiah in 2024 and about 1.6 trillion rupiah in the first half of 2025.
KAI, the largest shareholder, bore the biggest share of the strain, including roughly 2.23 trillion rupiah in 2024. The railway company also set aside a sinking fund that year, a reserve intended to keep cash available if KCIC faced another shortage.
The figures trace the pressure through the ownership structure: financial trouble at the project company reaches the consortium and its state enterprise shareholders. KAI's reserve addresses the immediate need for available cash, while restructuring would address the timing and cost of debt payments.
Danantara is weighing two ways to intervene
Danantara sits at the center of the proposed solution because it controls state company operations and dividend flows. Officials want it to keep Whoosh running, protect the finances of key state enterprises and handle the obligations without drawing on the state budget.
Two strategic options are under review. One is to inject fresh equity into the operating consortium. The other is to move the railway asset into full public ownership, with operations contracted out and debt handled through a centralized arrangement. Either approach would likely accompany loan restructuring.
New equity could strengthen KCIC's balance sheet, the record of what it owns and owes, and help it meet loan covenants. Covenants are conditions a borrower agrees to follow. A stronger financial position could also help the company negotiate more manageable terms.
The money would have to come from the state company ecosystem. Committing it to Whoosh would reduce funds available for other investments or dividend payments. A capital injection therefore involves a choice about how public enterprise resources are used, even when the state budget makes no direct payment.
Moving the infrastructure into a public portfolio could make responsibility for the asset and its long term planning clearer, while a separate company runs the service. It would concentrate liabilities under Danantara's management and would need safeguards to prevent obligations from moving into the budget.
Critics caution that an ownership transfer needs transparent accounting and clear rules about who pays when revenue falls. Those rules address moral hazard, the risk that companies take on excessive obligations because they expect another institution to rescue them.
More passengers have not yet closed the gap
Whoosh carried about 2.9 million passengers in the first half of 2025. Recent daily volumes have ranged between 20,000 and 30,000 passengers, providing a growing base of users for the service.
Higher ridership has improved operating performance, but ticket revenue has not yet covered the combined burden of energy, maintenance, staffing, track access and debt service. Reaching breakeven, where income meets costs, likely requires a sharp rise in demand, a different financing profile or both.
KAI president director Bobby Rasyidin warned lawmakers about the size and structure of the obligations. He described the risks in stark terms:
The project's financial and operational problems resemble a ticking time bomb.
The relatively short route limits revenue per passenger compared with longer corridors. Fares must remain affordable enough to attract travelers while producing enough income to help cover costs. Raising passenger numbers and reducing financing pressure address different parts of the same problem.
Better connections between stations and passengers' final destinations, along with integrated ticketing, could increase demand. Debt restructuring could reduce the cash leaving the company for repayments. Lasting stability is likely to require progress on both fronts.
What China could agree to change
Officials involved in discussions say China is open to restructuring repayments to keep Whoosh operating. The railway is Southeast Asia's first true high speed service and a flagship cooperation project, giving both sides commercial and diplomatic reasons to seek a workable settlement.
A longer loan maturity would spread repayments over more years. A lower rate on the cost overrun loan would reduce interest costs. Grace periods could postpone principal payments while passenger demand develops. Another option would be to consolidate obligations into a new schedule matched to expected cash flow.
Lenders want the railway to stabilize and preserve their ability to recover the money lent. The operator needs rising demand to translate into reliable service and payments it can plan for. A repayment schedule suited to the railway's income would help connect those objectives.
Danantara's leadership says a detailed evaluation is underway. The expected presidential decree would formalize the negotiation team. Talks will likely require audited financial statements, updated revenue forecasts and a term sheet setting out interest rates, maturities and security, including what backs the borrowing.
A settlement would also need to specify how state enterprise dividends cover annual obligations without budget payments. Investors will want clarity on whether state guarantees exist and how they would operate.
How the financial pressure developed
The sequence shows how a newly operating railway has become a test of Indonesia's infrastructure financing arrangements. Construction costs rose before passenger revenue had time to develop, and the losses then reached the state companies behind the project.
- October 2023: Whoosh began commercial service on the 142 kilometer Jakarta to Bandung route.
- 2024: PSBI recorded losses of around 4.2 trillion rupiah, while KAI bore roughly 2.23 trillion rupiah and established a sinking fund for possible cash shortages at KCIC.
- First half of 2025: KCIC recorded a loss of about 1.6 trillion rupiah and carried roughly 2.9 million passengers. KAI absorbed approximately 951 billion rupiah through its shareholding.
- October 23, 2025: The government rejected state budget debt payments, Danantara was evaluating options, and China had indicated openness to restructuring discussions.
The next steps identified by officials are the presidential decree, a detailed Danantara plan and negotiations over loan terms. The higher interest rate on the cost overrun borrowing is expected to be a central issue.
The Surabaya extension remains part of the debate
Indonesia wants to resolve Whoosh's debt problems without abandoning plans to extend high speed service east to Surabaya. A longer corridor would open larger travel markets and could increase revenue per kilometer, while requiring coordination over land, stations and connections to commuter rail and airports.
Coordinating Minister for Infrastructure and Regional Development Agus Harimurti Yudhoyono, known as AHY, acknowledged the financing challenge while supporting the expansion plan:
Debt issues in the Jakarta to Bandung high speed rail must not hinder the planned expansion to Surabaya.
Addressing the existing balance sheet strain is a prerequisite for expansion. Investors will seek a clear funding model and rules dividing risk among the parties. Demand forecasts must account for changing travel patterns, including Jakarta's rail network upgrades and the planned relocation of the national capital to East Kalimantan.
A longer railway could improve the system's commercial prospects if its financing reflects realistic demand and sets clear limits on public exposure. The current line's performance and any reduction in repayment pressure will shape how easily an extension can attract funding.
Other regional rail projects show similar pressures
Chinese backed railway projects across Southeast Asia have produced mixed results. Thailand and Malaysia renegotiated high speed rail proposals to reduce debt burdens and adjust the sharing of risk. The Philippines cancelled several railway loans amid political changes.
Laos completed its railway crossing the border, but multilateral assessments describe it as a large contingent liability with uncertain returns. A contingent liability is a possible financial obligation that may have to be met if specified circumstances arise.
Cambodia is seeking support for a new railway. Vietnam has approved Chinese loans for a new line in the north and continues to pursue an ambitious high speed corridor running from north to south that could cost tens of billions of dollars.
Indonesia's experience fits a regional pattern in which passenger demand, construction cost control and the division of financial risk determine whether a railway creates value. A pledge to avoid budget funding leaves difficult choices when losses accumulate inside state companies.
Realistic revenue forecasts, transparent financial reporting, carefully designed guarantees and contingency reserves can protect commuters and taxpayers. When the assumptions behind a project change, timely restructuring can help restore financial balance while preserving service.
What taxpayers and commuters stand to gain or lose
The Finance Ministry maintains that Indonesia's state budget, known as APBN, will not pay Whoosh's debts. It points to the business to business financing model and places responsibility with state companies and Danantara.
State enterprise dividends are public assets too. Heavy losses or large commitments to rail debt leave fewer resources for other priorities. The government has separated state enterprise dividends from the budget and is working to keep Whoosh's obligations within Danantara, with the aim of containing those risks.
For passengers, the railway already offers a major improvement in journey time and comfort. Competitive fares, dependable schedules and convenient links to commuter rail, MRT, LRT and buses could help make it a more regular travel choice. Ticketing that works smoothly across transport modes would also make complete journeys easier.
Growing ridership can improve operating efficiency. Lower debt payments could leave more cash for maintenance and service frequency. Together, those changes could strengthen the railway's user base while improving its finances.
Regular financial and performance updates would show how much of Danantara's dividend pool is committed to rail obligations and when the fund must intervene. Transparent rules would help prevent the burden from drifting into the state budget during difficult years.
The next decisions will shape the railway's finances
Danantara must develop a detailed plan weighing fresh equity against an ownership transfer, with a full account of the costs and benefits. The negotiation team, once authorized, would work with China Development Bank and other creditors on a revised repayment profile.
Operational measures will also matter: passenger growth, the proportion of seats filled during busy and quieter periods, punctuality and fare adjustments. Those figures will help show whether revenue is moving closer to the railway's costs.
Steady gains on the Jakarta to Bandung route and reduced repayment pressure would support efforts to finance a Surabaya extension. The government's chosen approach calls for state companies and Danantara to manage the financial repair without state budget debt payments, while keeping the existing service reliable.
At a Glance
- Indonesia rejects state budget payments for Whoosh's debts and assigns responsibility to state enterprises and Danantara.
- The railway's estimated construction cost rose from near $6 billion to about $7.27 billion.
- China Development Bank financed roughly 75 percent of construction, with interest of 2 percent on the original loan and 3.4 percent on the cost overrun loan.
- KCIC lost about 1.6 trillion rupiah in the first half of 2025, while KAI absorbed approximately 951 billion rupiah through its stake.
- Whoosh carried about 2.9 million passengers in the first half of 2025, but revenue still fell short of operating and financing needs.
- Danantara is considering fresh equity or a move into full public ownership alongside debt restructuring.
- China has indicated openness to repayment talks; final terms have not been announced.
- Officials want the financial repair to preserve service and support plans for an extension to Surabaya.