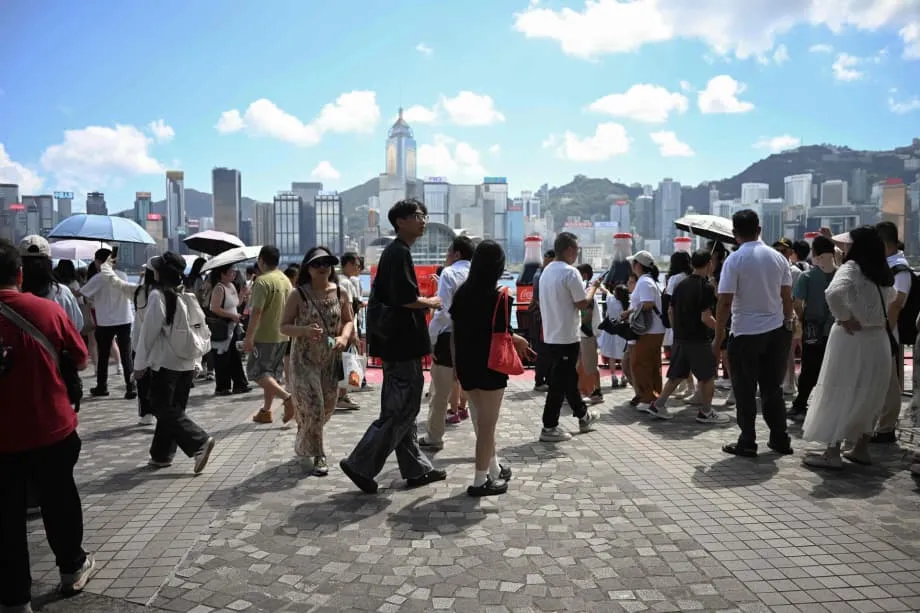
A changing balance on Hong Kong's shopping streets
Mainland Chinese brands account for roughly 35 percent of new retailers entering Hong Kong each year, while Chinese marques make up seven in ten newly registered electric vehicles in 2025. Those two figures capture a wider change visible across the city's restaurants, tea shops, sportswear stores, jewelers and electronics outlets: businesses from across the boundary are winning customers in a market once defined by Hong Kong labels.
Contents
- A changing balance on Hong Kong's shopping streets
- How the old quality advantage narrowed
- Why service, speed and scale matter
- Phones and noodles show the pressure on local rivals
- Electric cars and gold gain new audiences
- Falling sales reset the rental market
- More visitors, different spending habits
- Hong Kong products still find buyers online
- Integration brings a debate about identity
- Practical choices for Hong Kong businesses
- Key Points
As of October 18, 2025, the shift reaches beyond cheaper prices. Shoppers are responding to fresh designs, faster service, frequent product updates and stores that offer more room to explore. Mainland companies are arriving as Hong Kong's retail property market becomes more affordable, giving newcomers access to prominent locations that previously demanded much higher rents.
Honor, the Chinese smartphone maker, offers an example just across the boundary. Its recently opened flagship in Shenzhen Bay, minutes from Hong Kong, occupies two levels, displays a full ecosystem of devices and uses robots to assist visitors. The store offers a more interactive experience than the repetitive layouts found in some Hong Kong phone shops.
Hong Kong residents increasingly spend weekends north of the boundary for shopping and dining. Product variety, attentive follow ups and the appeal of something new help explain those journeys. Mainland brands are also bringing that approach directly into Hong Kong, connecting physical stores with digital shopping and customer service.
Local businesses face pressure from both directions: residents can travel to mainland stores, and mainland competitors can open nearby. Hong Kong brands still command trust, particularly among mainland consumers shopping online, but that reputation now competes with a broader range of products that customers regard as reliable, attractive and good value.
How the old quality advantage narrowed
Hong Kong's relationship with mainland consumer goods once ran largely in the opposite direction. During the city's economic boom in the 1970s and 1980s, residents took medicines, small electronics and canned goods to relatives on the mainland. Hong Kong products carried an assurance of quality that was harder to find elsewhere.
Trust in Hong Kong quality reached a high point around 2010, when uneven production standards and counterfeit goods remained problems on the mainland. Since then, mainland manufacturing has moved into more valuable and sophisticated products. Quality control has improved, and companies have become better at explaining their products and building recognizable brands.
Factories that previously made goods for global labels now produce premium ranges for homegrown companies. Hong Kong shoppers increasingly view mainland phones, pantry staples and other everyday goods as safe, well designed and reasonably priced. Long established Hong Kong names can look rigid or dated beside competitors that refresh products and presentation more quickly.
The change has unfolded over decades rather than through a single opening or shopping season:
- In the 1970s and 1980s, Hong Kong residents brought consumer goods to relatives on the mainland.
- In 2009, Laopu Gold was founded, entering a jewelry market where Hong Kong houses enjoyed considerable prestige.
- Around 2010, confidence in Hong Kong quality peaked while mainland production still faced uneven standards and counterfeits.
- Before 2022, Tesla dominated electric vehicle registrations in Hong Kong.
- Since 2022, nearly 100,000 visas have been issued under the Top Talent Pass, about 95 percent to mainland professionals.
- In 2024, Hong Kong retail sales fell 7.3 percent for the full year.
- By 2025, Chinese marques account for seven in ten newly registered electric vehicles in Hong Kong.
For consumers, the practical change is a wider choice of brands whose quality they trust. For Hong Kong businesses, a familiar name alone provides less protection when a rival offers a newer product, a more inviting store or faster help after a purchase.
Why service, speed and scale matter
Mainland retailers combine large supply networks with digital platforms, allowing stock to move quickly and store selections to reflect what customers browse online. New models arrive on tight schedules. Customer service teams follow up by phone or chat, keeping contact with shoppers after they leave the store.
Flagship stores make room for large demonstration areas and guided stations where visitors can try products. Instant payments and simpler returns reduce everyday inconvenience. In technology and wearable devices, connected product ecosystems also matter: phones, accessories and other devices are presented as parts of a coordinated range rather than isolated purchases.
Price remains a powerful attraction, but many mainland entrants have reasons to accept modest earnings initially. Hong Kong gives them a visible stage on which to build recognition, test operations intended for overseas markets and demonstrate ambition to business partners. Some prioritize visibility over immediate profit while tourism and local spending stabilize.
Language and cultural familiarity make expansion easier. Staff can move between Cantonese, Mandarin and English, while companies can adjust product features to local preferences without long delays. Hong Kong also provides an accessible first step toward Southeast Asia, giving mainland brands another reason to establish prominent stores.
The estimate that mainland brands make up roughly 35 percent of new retail entrants comes from leasing brokers. Their share has risen from less than a third, and analysts describe it as more than a third of new arrivals each year. The figure concerns businesses entering the market, while the established retail landscape still includes local and international operators.
Lower rents strengthen this strategy. A brand seeking recognition can now secure more space for displays and polished interiors at a lower cost than during the property market's peak. Customers see the result in stores that feel newer and more generous, reinforcing the impression that their money buys more.
Phones and noodles show the pressure on local rivals
Chinese smartphone makers have overtaken Apple and Samsung in Hong Kong market share in recent years. Releases from Huawei, Honor and Xiaomi often sell out quickly, leaving stores struggling to meet demand during the first weeks. Manufacturing strength, sleek marketing and fast support after a sale have helped attract younger buyers in particular.
Honor's Shenzhen Bay store illustrates how these companies sell an experience as well as a device. Its connected product displays and robotic assistance give visitors reasons to spend time exploring. Frequent updates and customer follow ups help sustain interest beyond a single purchase.
Tsim Sha Tsui's dining streets show similar competition at a more everyday level. Long running local restaurants now operate beside bright, spacious mainland chains. Hefu Noodle has drawn steady queues with stylish interiors, menu innovation and trained staff, despite charging prices similar to traditional noodle shops.
Prince Noodles, a neighborhood favorite serving brisket and offal, has seen traffic fall next to the new competitor. A staff member described the effect of Hefu Noodle's arrival on the shop's business:
They have taken away half of our business since they opened, because their mainland owner has deep pockets for top notch decorations.
The worker's account describes a direct loss of trade at one restaurant. It also shows why similar prices can produce very different outcomes: customers compare the surroundings, menu and service alongside the cost of a bowl of noodles.
Mainland entrants began with coffee, hotpot and noodles before expanding into sportswear, jewelry and consumer electronics. Some mainland internet groups have also opened physical stores to meet customers face to face and build communities around their platforms. The boundary between an online business and a street retailer is becoming less rigid.
Electric cars and gold gain new audiences
Hong Kong's electric vehicle market has changed sharply since the period before 2022, when Tesla dominated registrations. By 2025, Chinese marques account for seven in ten newly registered electric vehicles, showing how consumer views of mainland manufacturing have shifted in a costly and highly visible product category.
Eric Wong, chairman and chief executive of vehicle dealer Richburg Motors, described the change in customer attitudes:
In the old days, Hong Kong people would not buy Chinese cars. Now the quality is good, the price is hard to beat and the design is fashionable.
Automakers see Hong Kong as a proving ground even though the market is small, competitive and offers thin margins. Meeting European level certification standards in the city helps prepare them for entry into other regions. A Hong Kong presence can therefore serve a wider expansion plan as well as local sales.
Laopu Gold is bringing fresh competition to jewelry, another category long associated with Hong Kong prestige. Founded in 2009, it has outperformed traditional Hong Kong jewelry houses during key shopping periods by promoting traditional gold craftsmanship and royal techniques in contemporary designs.
The company has opened multiple Hong Kong branches and treats the city as a springboard for overseas markets. Its flagship in Tsim Sha Tsui's Silvercord center covers 10,000 square feet and costs about HKD 1.5 million a month in rent. A leading luxury fashion label previously occupied the same site at rents above HKD 6 million during the peak.
Using those figures, Laopu's monthly rent is less than a quarter of the earlier peak rent, a reduction of more than 75 percent. That difference gives a newcomer much more room to fund a prominent store. Lower occupancy costs, marketing rich in product stories and a steady flow of younger shoppers have helped generate heavy footfall.
Falling sales reset the rental market
Official data show that Hong Kong retail sales declined month after month through late 2024, leaving sales for the full year down 7.3 percent. Landlords responded with shorter leases, more flexible terms and lower headline rents, opening streets that emerging operators previously struggled to afford.
Vacant premises in parts of Tsim Sha Tsui and Causeway Bay after the pandemic created space for businesses to try new formats. Mainland brands moved quickly into that opening. Their willingness to invest in visibility met a property market in which owners were more willing to negotiate.
Andy Kong, chief sales director at Midland Shops, expects further changes among tenants as competition continues. He described both the risk of business closures and the opportunity created by empty premises:
It is anticipated that the retail market will undergo significant restructuring, with some brands likely to be eliminated due to market competition, leading to high vacancy rates. On the positive side, the vacant shops present opportunities for emerging businesses.
For an existing retailer, a new neighbor with substantial financial backing can make a difficult trading environment tougher. For an incoming business, the same conditions can reduce the cost of establishing a presence in a famous shopping district. Landlords face the task of replacing departed tenants while adjusting expectations about rent.
Some overseas brands have consolidated their stores or paused new openings until sales stabilize. Mainland companies seeking an overseas platform have a different incentive to expand, even when immediate returns are limited. The changing mix of storefronts reflects those different business priorities as well as customer demand.
More visitors, different spending habits
Mainland tourists represented about three quarters of the more than 20 million visitors recorded in Hong Kong during the first five months of 2025. Their importance to the city remains large, but the familiar pattern of visitors arriving for shopping sprees has softened.
High spenders now divide purchases among Shenzhen, duty free zones in Hainan and overseas destinations where exchange rates and tax conditions are favorable. Luxury brands are widely available on the mainland, reducing the need to travel to Hong Kong to find them.
A visitor from Liaoning, in Hong Kong on a business trip, described that change in personal spending:
I am staying four days in Hong Kong, but I do not want to spend a penny here. I used to buy bags and watches, but luxury goods are not cost effective anymore since most brands are available on the mainland.
Hong Kong residents are also looking elsewhere for value. A strong Hong Kong dollar raises the cost of imports, while a soft property market weakens the wealth effect for middle class households. The wealth effect describes how the value of assets, such as a home, can influence a person's willingness to spend. Residents also shop during trips to Japan and Southeast Asia for bargains and variety.
New arrivals are changing the local customer base. Since 2022, nearly 100,000 visas have been issued through the Top Talent Pass, with about 95 percent going to professionals from the mainland. Closer integration with the Greater Bay Area and the changing resident mix help shape demand for brands already familiar north of the boundary.
Visitors can also find mainland brands part of Hong Kong's attraction. During a June trip, a tourist from Thailand headed straight to a popular tea chain, described the experience as more authentic and enjoyed its branded bag. For that traveler, familiarity combined with a different setting added to the appeal.
Hong Kong products still find buyers online
A recent survey of consumers with middle to high incomes across mainland cities found that 78 percent had bought Hong Kong products online during the previous year. Respondents rated those goods highly for safety and authenticity, with consumer electronics, fashion and luxury among the favored categories.
Tmall International and JD International handle much of this shopping through marketplaces that allow purchases across the boundary. Fast delivery is an advantage. When choosing products, consumers rank authenticity, the merchant's reputation and a wide selection above low prices.
China's social commerce market also keeps expanding. Shopping through live broadcasts generated hundreds of billions of dollars in sales in the previous year and is growing quickly from year to year. A growing creator economy includes studios using digital avatars to produce more content and reach particular customer groups.
Eric Chu Tak hin, an economist at the Hong Kong Trade Development Council, advised brands to use several routes to reach buyers and select partners suited to their products:
Adopt a multichannel strategy. Use established marketplaces and rising social platforms, study the audience and pick influencer partners that fit the product, then show authentic user experiences.
A multichannel strategy means selling and communicating through several connected places, such as a shop, an online marketplace and a social platform. Mainland brands succeeding in Hong Kong already connect content, shopping and physical stores in this way. They keep product stories fresh and use the languages and channels their customers prefer.
For Hong Kong companies, the survey points to demand beyond their domestic stores. Consumers who value authenticity and safety give them a basis for growth on the mainland, even as they face tougher competition at home.
Integration brings a debate about identity
Government figures show that in 2024 more mainland companies than foreign firms established themselves in Hong Kong with official assistance, reversing the pattern of previous years. Corporate arrivals mirror the changing retail mix as the city retains its financial center role, sits beside the mainland's manufacturing heartland and aligns with national priorities on security and development.
Gary Ng, senior economist for Asia Pacific at Natixis, linked the new mix of tenants and arrivals to both practical conditions and policy. He also warned about the effect on Hong Kong's distinct character:
It is much easier to attract Chinese chains than foreign ones, and the presence of big Chinese names can be presented as a political success. The risk is that dominance by mainland brands erodes Hong Kong's unique identity.
Anthony Cheung, a former secretary for transport and housing and now a professor of public policy, placed the retail shift within a longer economic cycle. He described how the balance between Hong Kong and mainland cities has changed:
It is a natural phenomenon driven by changing asymmetries. Many mainland cities today have greater gross domestic product than Hong Kong. There is still a sense of local belonging, but what that means will evolve over time.
Gross domestic product measures the value of goods and services produced in an economy. Cheung's comparison concerns the changing economic size of mainland cities relative to Hong Kong, which helps explain why mainland companies now arrive with the resources to compete strongly.
Hong Kong's shopping districts consequently bring together different interests: residents seeking value, visitors seeking familiar brands in a new setting, businesses pursuing expansion and people concerned about local identity. The new storefronts change both where customers spend and how the city presents itself.
Practical choices for Hong Kong businesses
Hong Kong labels retain a reservoir of trust, especially among mainland shoppers who value authentic products. Their task is to update products, stores and customer contact while preserving that confidence. The competitive pressures described across phones, food and jewelry point to practical changes rather than reliance on reputation alone.
Businesses can respond through several connected steps:
- Rework store layouts to encourage browsing and product demonstrations, and train staff to follow up through chat and phone.
- Shorten product cycles, test small batches and collect feedback within weeks rather than quarters.
- Use online retail, social commerce and marketplaces serving mainland customers, with clear evidence of authenticity and safety.
- Invest in design, packaging and straightforward stories about craftsmanship and function that appeal to younger shoppers.
- Work with payment and logistics providers that simplify exchanges and returns, provide fast delivery and make tracking transparent.
- Consider joint releases with complementary mainland brands, creating products that combine their strengths.
- Measure results and adjust products and promotions by district, where neighborhood preferences and visitor mixes differ.
Hong Kong's historic strengths in service, trust and speed remain useful. Mainland competitors are challenging local businesses to deliver those qualities in updated ways, while online demand gives Hong Kong brands opportunities across the boundary. Companies that respond quickly can pursue growth both at home and on the mainland.
Key Points
- Mainland brands account for roughly 35 percent of new retail entrants in Hong Kong each year.
- Chinese smartphone makers have overtaken Apple and Samsung in local market share, while Huawei, Honor and Xiaomi launches often sell out quickly.
- Hefu Noodle's store design, menu and service are drawing customers and putting pressure on nearby local restaurants.
- Chinese marques account for seven in ten newly registered electric vehicles in Hong Kong in 2025.
- Laopu Gold has expanded in the city, with its Silvercord flagship paying about HKD 1.5 million in monthly rent.
- Hong Kong retail sales fell 7.3 percent in 2024, helping drive more flexible leases and lower rents.
- Tourists are spending more selectively, while residents seek shopping value on the mainland and overseas.
- Nearly 100,000 Top Talent Pass visas have been issued since 2022, about 95 percent to mainland professionals.
- A survey found that 78 percent of mainland consumers with middle to high incomes had bought Hong Kong products online in the previous year.
- Updated stores, faster product cycles and connected online sales channels offer Hong Kong brands practical ways to compete.