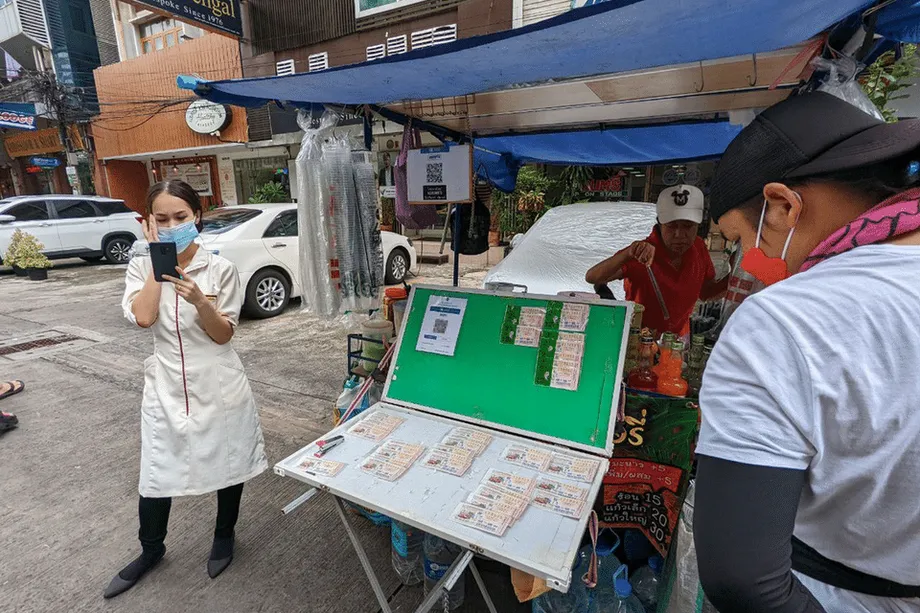
Lottery losses could help build a retirement fund
Thailand plans to convert part of the money spent on losing digital lottery tickets into retirement savings, with withdrawals available from age 55. Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas is championing the policy, which officials aim to launch within four months of the timetable outlined as of October 2, 2025.
Contents
- Lottery losses could help build a retirement fund
- How losing tickets would generate savings
- Where the savings credit would come from
- Why Pao Tang buyers would qualify first
- A separate lottery would make every ticket savings
- Which approvals are still needed?
- Turning a common expense into future income
- A bond option for older savers
- International interest and the test of public trust
- What officials plan to do next
- Key Points
The scheme would apply to tickets purchased through the government's Pao Tang app. When a ticket fails to win, a defined share of its purchase price would go automatically into the buyer's savings account. The exact share has yet to be announced.
A separate retirement lottery under the National Savings Fund (NSF) would make every ticket a savings deposit from the outset, whether the buyer wins a prize or not. Its proposed tickets cost 50 baht, with purchases limited to 3,000 baht per person each month and ordinary access to accumulated savings at age 60.
The two initiatives share an aim: directing some of Thailand's familiar lottery spending toward financial security in old age. Their rules differ, however, including how much becomes savings, when people can withdraw it and which legal steps remain before they can begin.
Thailand faces a rapidly aging population and uneven household savings. Many people move between informal jobs that provide no pension, leaving them dependent on family support and the state old age allowance. Those sources of help can be thin. Officials hope that attaching savings to an existing habit will build a financial cushion for people who otherwise put little aside.
How losing tickets would generate savings
Under the conversion proposal, part of the cost of a non-winning digital ticket would be credited to an individual savings account. The money would remain invested under conservative rules, with safety and preservation of capital guiding its management.
Officials describe the legal and technological arrangements as ready. The scheme would use Pao Tang to connect each purchase to a verified buyer and credit the correct account automatically. Ekniti has identified it as a priority that can be delivered quickly because the digital ticketing and payment infrastructure already exists.
The savings vehicle would follow rules similar to Thailand's Retirement Mutual Fund framework. These funds are intended for saving over a long period. In this proposal, the central idea is straightforward: a portion of money spent on an unsuccessful ticket would remain available for the buyer's retirement instead of disappearing entirely as a lottery loss.
Participants could begin withdrawing at age 55. People aged 56 and above would be able to continue adding money for another five years. The accumulated balance could also be pledged as collateral for a loan, meaning it would serve as security for money borrowed.
Officials intend that borrowing option to help households meet urgent expenses without immediately withdrawing their retirement savings. The Ministry of Finance still plans to finalize the withdrawal conditions and the process for using balances as collateral.
Where the savings credit would come from
Thailand's official lottery divides ticket revenue among prizes, government revenue and administrative costs. The government plans to finance the savings credit by redirecting part of the allocation currently set aside for the Government Lottery Office.
The proposal would move a slice of that existing allocation into buyers' savings accounts without changing the prize pool. It would therefore change how part of the ticket revenue is used, while keeping the lottery's prize arrangements intact.
The Ministry of Finance has indicated that investment safety will be a priority. Administrators have pointed to principles similar to those used for Retirement Mutual Funds, with portfolios leaning toward bonds and other instruments of high quality rather than speculative assets. Existing financial rules would provide oversight intended to protect savers.
Conservative investing means placing greater weight on protecting money and allowing it to grow prudently over time. The amount ultimately available to a participant would depend on the savings credited and how the fund performs. The government has not supplied the final crediting formula, which will be central to understanding how much an individual could accumulate.
Why Pao Tang buyers would qualify first
Pao Tang is the government backed app used for public payments, welfare programs and official digital lottery sales. It connects purchases to a verified profile that includes a bank link. Those records would allow administrators to identify a losing ticket and direct the savings credit to its owner.
Paper tickets would be outside the scheme at launch because they cannot reliably be matched to a verified saver in real time. Officials argue that beginning with digital purchases is necessary for accurate payments and protection against abuse.
The digital transaction record could reduce fraud, simplify reporting and allow administrators to monitor unusual spending patterns. It could also support spending safeguards and targeted education about responsible lottery purchases. Personal data would remain subject to privacy obligations, with program rules expected to explain how information is used, stored and protected.
The restriction creates a practical divide. People who continue buying paper tickets would receive no savings credit, while some older or rural buyers could struggle to join without help using the app. Outreach and assistance with registration would therefore matter to access.
Other purchase channels could be considered later if officials can resolve the verification problems while maintaining protections. For the first phase, the government's stated priority is a system that can trace purchases accurately and credit savings automatically.
A separate lottery would make every ticket savings
The NSF retirement lottery would work differently from the conversion of losing digital tickets. Each 50 baht ticket would become savings from the moment of purchase, with a chance of winning a cash prize added to it.
Weekly draws are planned for Fridays at 5 pm. Each draw would offer five top prizes of 1 million baht and 10,000 second prizes of 1,000 baht. Prize payments would go to bank accounts linked to PromptPay.
Money spent on tickets would accumulate with the NSF and be returned with investment returns at age 60. Buyers who do not win would still retain their ticket spending as savings. The original savings commitment applies whether a ticket wins or loses.
Purchases would be capped at 3,000 baht per person per month, a limit intended to promote fairness and prevent wealthy participants from concentrating purchases. At 50 baht a ticket, that monthly limit would allow up to 60 tickets per person.
People older than 60 could also participate if they accepted a wait of ten years before accessing their money. Policymakers are exploring limited early withdrawal provisions through ministerial regulations, including possible partial access for medical needs.
Deputy Finance Minister Paopoom Rojanasakul has described the NSF lottery as a savings mechanism with a prize draw attached. He expressed its intended purpose in these words:
It is structured saving, not gambling.
The difference between the two programs matters to buyers. The losing ticket scheme would save a portion of an unsuccessful digital purchase and allow withdrawals from age 55. The NSF lottery would save the entire ticket price, with the standard repayment point at age 60.
Which approvals are still needed?
The Cabinet previously endorsed amendments to the NSF law to authorize the retirement lottery. The House of Representatives has since passed the bill with overwhelming support. As of October 2, the measure was moving to the Senate, with implementing regulations also required.
Officials have pointed to a launch in the fourth quarter of 2025 if the remaining steps are completed on schedule. The NSF is expected to publish operational details on eligibility, prize distribution and any early withdrawal criteria after the legal process is finished.
The two programs have separate schedules and approval processes. The sequence outlined by officials is:
- The Cabinet endorsed changes to the NSF law allowing a retirement lottery.
- The House of Representatives passed the bill, sending it toward Senate consideration and subsequent regulations.
- Officials targeted the fourth quarter of 2025 for the NSF lottery, subject to completion of those steps.
- The Ministry of Finance aimed to introduce the losing digital ticket conversion within four months of the timetable described as of October 2, 2025.
Lawmakers have asked for more flexible access to retirement lottery savings for medical bills and other essential expenses. They have also sought clarity on minimum returns and prize structures. Officials argue that conservative investments and the monthly purchase limit provide a balance between attracting participants and controlling risk.
Final regulations will determine the practical details of those protections and exceptions. The launch targets remain dependent on completion of the required work.
Turning a common expense into future income
Lottery spending, both official and underground, is widespread in Thailand. The government hopes to direct part of that regular outlay into formal savings that people can carry into old age.
The conversion of losing tickets would act as a financial nudge: someone making a familiar purchase would begin accumulating savings automatically. The retirement lottery would go further by treating the whole purchase as money set aside, with prizes providing an additional incentive.
For workers without a pension from employment, either account could eventually supplement the state old age allowance or support from relatives. The proposed collateral option could also provide a way to borrow during a period of financial strain while keeping savings invested.
Officials say the purpose is to promote thrift rather than increase gambling. That aim will require careful communication because the savings feature could also make frequent lottery purchases feel more acceptable. Spending limits where appropriate, responsible play warnings and clear explanations of the rules are among the protections identified as important.
The NSF lottery's monthly cap is one defined limit. For the conversion scheme, administrators could use the digital record to monitor unusual purchases and develop safeguards as needed. Participation would still depend on people understanding how much is saved and when it can be accessed.
A bond option for older savers
The Ministry of Finance is also preparing a monthly government bond offering for elderly and retired citizens with a 1 percent coupon. The coupon is the stated interest payment attached to a bond.
The program is intended to give older people a simple, safe place to hold cash or receive predictable income without taking on the market risk of more speculative investments. Its 1 percent return would be modest, but ease of purchase is part of the intended appeal.
The bond proposal sits alongside the lottery measures in the government's effort to strengthen retirement readiness. It would give people another savings choice, while the lottery schemes would try to reach those already spending regularly on draws.
International interest and the test of public trust
The World Bank has expressed interest in Thailand's approach following meetings with Thai officials. It praised the idea of using a familiar cultural habit to encourage retirement saving at relatively low fiscal cost.
The institution described the retirement lottery in these terms:
The retirement lottery is a remarkable innovation for boosting retirement savings.
The approach could be relevant to other aging societies where pension coverage is limited and lotteries or similar games are popular. Its attraction lies in connecting an existing behavior with a formal savings account, instead of relying entirely on people to begin a new habit.
The two Thai initiatives are experiments in behavioral finance, which examines how people's habits and choices affect their use of money. Their practical success will depend on trust in fund management, an easy experience through Pao Tang and timely information about participants' rights.
People would need to feel confident that their money is protected, their balances are easy to follow and withdrawals will be available under the promised rules. Problems with administration or communication could damage that confidence.
What officials plan to do next
The Ministry of Finance plans to use the coming four months to complete the losing ticket conversion rules. Its work includes defining the savings credit, confirming withdrawal conditions and establishing how balances can be pledged for loans.
Pao Tang would need updates so users can see, track and manage their savings in one place. Public communications are expected to focus on saving rather than encouraging additional lottery spending.
The NSF retirement lottery must continue through Senate review and the issuing of regulations. The fund is expected to explain how draws will operate, how savings repayments will be credited and which early withdrawal exceptions will apply. A public education campaign is also expected to explain that every ticket becomes savings and that prize money arrives through PromptPay without extra steps.
Key Points
- Thailand plans to credit part of spending on losing Pao Tang lottery tickets to individual retirement savings accounts.
- Withdrawals would begin at age 55, with people aged 56 and above able to keep adding savings for another five years.
- Balances could serve as loan collateral, and funding would come from part of the Government Lottery Office's existing revenue allocation.
- The separate NSF retirement lottery would sell 50 baht tickets, with a monthly purchase cap of 3,000 baht and standard access to savings at age 60.
- Friday draws at 5 pm would offer five prizes of 1 million baht and 10,000 prizes of 1,000 baht.
- The NSF bill has passed the House and awaits Senate consideration and regulations, with officials targeting the fourth quarter of 2025.
- The Finance Ministry also plans a monthly government bond offering for older citizens with a 1 percent coupon.