Automated factories run into a storage squeeze
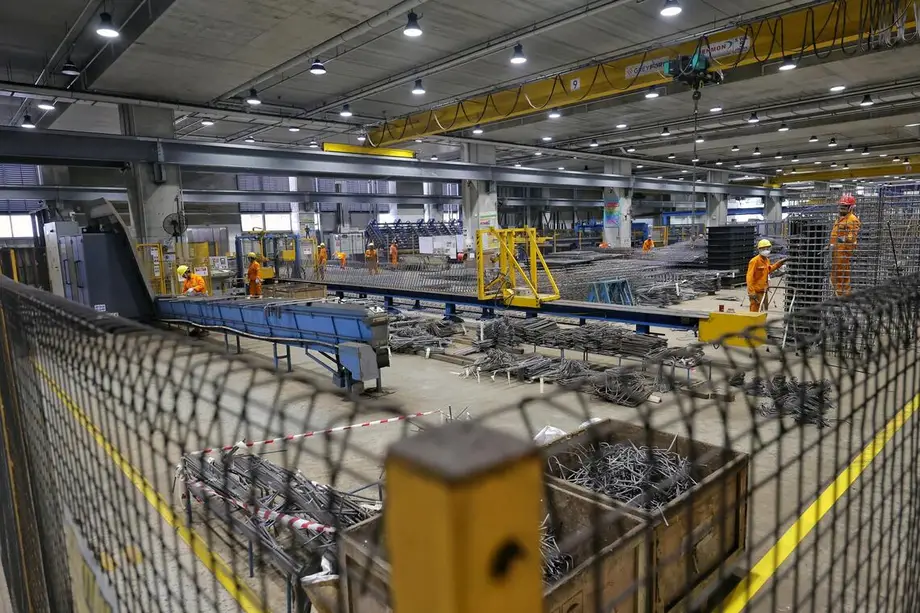
Singapore's automated concrete factories were built to make construction faster and less dependent on workers. Yet operators said output during parts of 2024 ran 20 percent to 50 percent below capacity, as delayed building projects left finished components with nowhere to go.
Contents
- Automated factories run into a storage squeeze
- How factory production changes building work
- Why a late delivery can stop a production line
- Malaysian yards compete on cost and space
- Housing procurement changes the demand picture
- Why HDB moved towards flat components
- Standard parts could improve factory economics
- Grants and tax support have limits
- Tiong Seng offers an example of continuity
- Digital coordination must reach the building site
- Other housing programmes face similar tradeoffs
- Cleaner production still depends on reliable demand
- The Bottom Line
On some weeks, a public road in an industrial estate becomes an unofficial storage yard. Trailers loaded with concrete walls, floor slabs and bathroom pods wait for construction sites that are not ready to receive them. Inside the factories, keeping those components would fill the limited storage space and obstruct production. Outside, parking them on public roads risks fines and damages public goodwill.
The factories are known as integrated construction and prefabrication hubs, or ICPHs. These facilities use several storeys and automated equipment to produce building components indoors, preparing them for delivery just when construction crews need them. Their efficiency depends on a steady flow from factory to building site.
Only six ICPHs have been built, short of a target set a decade earlier to have ten by 2020. A site in Kaki Bukit remained vacant for an extended period after two operators were wound up, before a new operator was appointed in 2025. Public tenders for new hubs attracted no bids when they closed in 2020, amid pandemic uncertainty and a pause in capital spending.
The pressures extend beyond delayed deliveries. Cheaper production in Malaysia, changes in public housing procurement and a move away from some large concrete modules have weakened the business case for investments intended to transform construction.
How factory production changes building work
ICPHs bring an approach called design for manufacturing and assembly into concrete construction. Instead of completing most tasks at a building site, companies manufacture parts in a factory and send them to the site for installation.
The hubs produce flat, or 2D, elements such as walls and floor slabs. They can also make 3D modules, including bathrooms and fully finished rooms. Conventional precast yards generally pour concrete into moulds outdoors. ICPHs move that work into a controlled environment and automate many of the steps.
Design teams first settle dimensions and the joints that will connect components. Precise digital models guide standardised moulds and reinforcement work. Machines bend and place reinforcing steel, while automated beds pour concrete to tight tolerances. Reinforcement cages and casting processes can be automated or partly automated.
Temperature and humidity are controlled while the concrete cures, helping to limit defects. Workers then remove components from their moulds, finish them, check their quality and give them unique identifiers. Radio frequency identification, known as RFID, or Bluetooth tags can track each piece from casting through installation.
At the building site, crews lift the completed parts into position and connect them. The intended benefits are better quality, safer working conditions, shorter construction periods, less rework and fewer workers in a tight labour market. HDB has reported man hour savings of up to 2.5 times for some precast processes, including floor slabs, where automation improves consistency and reduces human error.
Why a late delivery can stop a production line
Heavy rain, design changes, conflicts involving utilities, shortages of workers and other site constraints can delay construction. A postponed floor cycle can leave a day's production of walls and slabs waiting at the factory.
ICPHs have limited footprints and less room to stack finished components than open yards. Once storage fills, managers may slow or stop production for a month or two while construction sites catch up. A factory designed to produce large volumes then becomes a stop and start operation.
Lim Han Ren, group chief executive of Soilbuild Construction Group, which operates an ICPH in Paya Lebar, described the gap between the expected productivity gains and the time needed to achieve them.
The reality is that this future as we see it takes a longer time to materialise than we thought.
Lim said the hub averaged about 30,000 cubic metres of output over the previous two years, roughly one quarter below capacity. Lower production means the factory has fewer components over which to spread its building, equipment and other fixed costs.
The Building and Construction Authority, or BCA, has allocated plots under temporary occupation licences for overflow storage, usually for up to three years. These plots provide breathing room, but factories still need closer coordination with project teams so deliveries arrive when sites can accept them.
Shared storage, digital delivery slots and better alignment of production and installation schedules could reduce interruptions. Keeping completed modules on public roads may cost less than shutting a plant, but it brings enforcement risks and leaves the underlying delivery problem unresolved.
Malaysian yards compete on cost and space
Conventional precast yards in Malaysia benefit from more land and lower costs. Their concrete components can be priced roughly 15 percent to 20 percent below those made by Singapore's ICPHs.
Some precasters based in Singapore maintain a small local yard to qualify as approved suppliers while manufacturing most of their volume at larger Malaysian facilities. That arrangement helps them compete in Singapore and elsewhere in the region. It also puts pressure on local automated hubs with higher fixed costs and less storage.
Singapore's higher land and labour costs are familiar business expenses. Automated hubs add substantial spending on buildings, machinery and software. Depreciation, the accounting cost of using those assets over time, continues even when a factory has slowed production because deliveries are delayed.
Lower priced imports can draw orders across the border while local production lines remain underused. Operators who initially expected a quick return on their investment now describe much longer repayment periods, constrained by leases lasting 30 years and construction cycles outside their control.
Housing procurement changes the demand picture
Public housing procurement has changed over the past three years. An approach introduced in early 2022 required a larger share of key precast elements to be sourced locally. In April 2024, HDB gave contractors more flexibility to use both local and foreign plants.
HDB plans to launch about 55,000 Build to Order flats from 2025 to 2027. The agency said local factories sometimes operate near their optimum level, making several supply channels necessary to meet peak demand without compromising construction schedules.
Factories facing spare capacity and a public buyer preparing for busy periods are dealing with different parts of the same scheduling problem. Demand must match the components needed, the timing of production and the readiness of individual sites.
The main milestones show how investment and procurement have developed:
- 2012: Tiong Seng Prefab Hub opened, outside the later BCA land tender programme.
- 2017: The Land Intensification Allowance was extended to ICPHs.
- 2020: The target year for ten hubs passed with only six built, while tenders for new hubs closed without bids.
- Early 2022: Public housing requirements increased the locally sourced share of key precast elements.
- April 2024: HDB allowed contractors greater flexibility to source from local and foreign plants.
- 2025: A new operator was appointed for the Kaki Bukit site, and Budget 2025 extended the land allowance until the end of 2030.
Why HDB moved towards flat components
HDB has also reviewed prefabricated prefinished volumetric construction, or PPVC. This method uses 3D modules, such as rooms and bathrooms, with finishing work completed before installation.
Most recent HDB projects have shifted towards the Advanced Precast Concrete System, or APCS, which mainly uses 2D components. HDB explained the cost difference identified in its trials.
The overall costs for PPVC projects piloted by HDB were, on average, as much as 20 percent higher than APCS projects primarily built using 2D components, due to factors such as production, storage and transport.
The change reduced demand for 3D modules and made investments focused on PPVC harder to justify. Industry leaders also say the supply chain for 2D elements is more resilient because their moulds are cheaper and quicker to reproduce when demand rises.
Factories built around heavy modules face a particular mismatch. A 3D module can weigh 25 to 40 tonnes. Plants configured to handle them bought larger gantry cranes, often costing around S$250,000 each, and provided greater clearance between floors and ceilings for heavy lifting.
Those investments suited an expanding market for PPVC. A shift towards flat components leaves some equipment and building features less suited to current orders. Factory design and the purchasing plans of major buyers need to stay closely aligned.
Standard parts could improve factory economics
Kevin Soh, director at Integrated Precast Solutions, sees greater standardisation as a way to make automated production more efficient. Common designs would allow factories to reuse moulds and maintain more consistent processes.
Further standardising the design of precast components will allow automated technologies to be tapped more efficiently, since the moulds and processes used to produce them can be kept more constant.
HDB and BCA have started standardisation work on prefabricated bathroom units and household shelters. Industry proposals would extend that approach to a broader catalogue of walls, slabs, facades and bathroom units used by both public and private developers.
Longer batches of similar components would mean fewer production changes and more frequent reuse of moulds. Factories could spend more time producing and less time preparing for different designs, bringing output closer to their rated capacity.
Soh and other industry participants also favour longer leases. Most ICPHs occupy land under leases lasting 30 years. A longer operating period would allow capital costs to be spread over more years and could make financing easier, while recognising production time lost during pandemic disruption.
A lease extension would address fixed costs without an operating subsidy. Longer leases and wider standardisation remain industry proposals rather than announced changes.
Grants and tax support have limits
BCA has supported technology adoption through several measures. The Productivity Innovation Project cofunded up to 70 percent of qualifying technology costs, capped at S$10 million, for solutions delivering at least a 40 percent productivity gain in a process.
That scheme has ended and has been replaced by the Built Environment Technology and Capability Grant. Tax support includes the Land Intensification Allowance, extended to ICPHs in 2017 and renewed at Budget 2025 until the end of 2030.
Only one ICPH has used the allowance so far. Most hubs were developed before 2017 and could not benefit from it, limiting its reach among existing operators.
A BCA spokesperson described the commercial factors affecting the hubs and the agency's work with major buyers.
The financial viability of ICPHs depends on various factors, including their market positioning, product offerings and pricing strategies. BCA will continue working with key procurers such as HDB to provide ICPH operators with visibility of upcoming precast demand and specific product requirements.
Earlier information about future orders and product specifications would help operators decide what equipment to buy, which components to make and when to schedule production.
Tiong Seng offers an example of continuity
Tiong Seng Prefab Hub, which opened in 2012, cost about S$36 million and was developed outside the later BCA land tender programme. Its operator says the facility has maintained consistent service across major projects, even as profits have risen and fallen with market cycles.
The experience points to a continuing role for automated hubs when product mix and demand are stable. A factory can remain useful through changing market conditions, although consistent service does not remove fluctuations in profitability.
Industry proposals also call for rules on local presence and imported precast that support supply security while avoiding a shift of volume away from Singapore when local factories have spare capacity. Operators want a more predictable public sector pipeline, with specifications released early enough to guide investment decisions.
Digital coordination must reach the building site
Integrated digital delivery connects design models, shop drawings, manufacturing steps and site plans on one platform. Linking those activities can help factory managers see when components will be needed and allow contractors to plan for their arrival.
RFID and Bluetooth tracking can support scheduling, delivery acceptance and warranty records. A component's identifier follows it through production and installation, making its location and status easier to manage.
HDB has tested crane path planning aided by artificial intelligence, systems that help prevent collisions, and devices that turn panels into the required position before installation. These measures aim to reduce manual handling and improve the movement of components at the site.
Used together with shared storage and coordinated delivery slots, these tools could help factories spend less time holding finished stock. Faster casting brings limited benefit when the next stage of construction cannot receive the output.
Other housing programmes face similar tradeoffs
Comparative research on modular construction in mainland China, Hong Kong and Singapore identifies common benefits: shorter construction periods and better quality. It also identifies higher initial costs than traditional building, longer preparation periods and technical standards that lag behind innovation.
Clear specifications, supportive policies and close coordination between public buyers, contractors and factories are recurring requirements. Singapore's experience places particular weight on matching factory investment to purchasing decisions and site schedules.
India's Global Housing Technology Challenge established six light house projects to test construction methods at scale. The methods include 2D precast, 3D volumetric modules, tunnel form and composite systems.
Those projects use live housing developments to demonstrate speed and quality and help move methods from trials into wider use. Public procurement can set expectations and reduce investment risk by giving manufacturers a clearer view of what buyers need.
Cleaner production still depends on reliable demand
Precast production can reduce material spillage, improve concrete curing and limit defects and rework. These benefits support cleaner construction alongside the gains in speed and labour productivity.
Research into sustainable construction materials made from waste streams points towards new blends that could reduce carbon intensity while maintaining strength and durability. Factories control their concrete mixes and quality checks, giving them a setting in which to test and expand the use of such materials.
HDB targets a 40 percent improvement in site productivity by 2030. Automated precast production, standard components and digital coordination can support that goal, provided factory output reaches sites when it is needed.
Singapore also needs the flexibility to import during periods of peak demand. Competitive local factories would provide a dependable production base when supply chains come under pressure. The practical challenge is to keep that capacity commercially viable between busy periods, rather than letting completed components accumulate while production lines wait.
The Bottom Line
- Six ICPHs have been built, below the target of ten by 2020. A new operator was appointed for the Kaki Bukit site in 2025.
- Operators said output during parts of 2024 was 20 percent to 50 percent below capacity as project delays filled storage space.
- Malaysian yards can price precast components roughly 15 percent to 20 percent below Singapore ICPHs.
- HDB gave contractors more sourcing flexibility in April 2024 and plans about 55,000 Build to Order flats from 2025 to 2027.
- HDB's PPVC trials cost, on average, as much as 20 percent more than APCS projects mainly using 2D components.
- Government support includes technology grants and a land allowance extended until the end of 2030, although only one hub has used that allowance.
- Industry proposals centre on standard components, longer leases, earlier demand information, shared storage and closer coordination with construction sites.