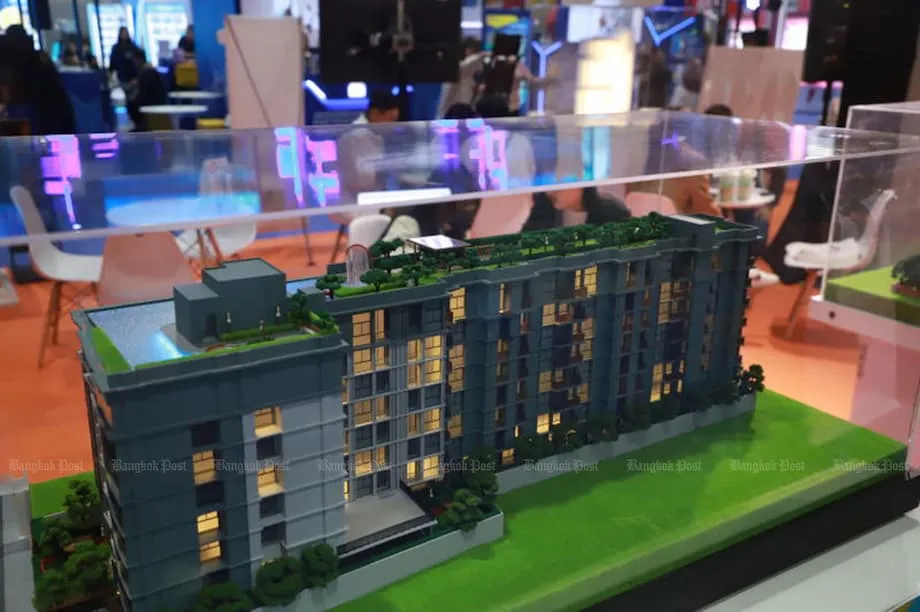
Lower prices meet a market short of willing buyers
A new condominium project in Bangkok's Rama IV corridor has opened at about 120,000 baht per square metre, against more than 150,000 baht at nearby buildings launched earlier. Across the Chao Phraya River in Tha Phra, new units are being offered at 60,000 to 70,000 baht per square metre, well below the common market average of more than 100,000 baht.
Contents
- Lower prices meet a market short of willing buyers
- How far have prices moved?
- Higher building costs squeeze developers
- Unsold homes reshape the launch calendar
- Why cheaper homes still struggle to find buyers
- Policy support meets strict lending standards
- Buying before completion or moving in now
- Luxury homes and rentals show greater strength
- Safety becomes part of the buying decision
- What buyers can check before committing
- What could bring demand and supply closer together?
- Key Points
As of September 18, 2025, those prices illustrate how developers are accepting smaller profits to attract buyers facing weak purchasing power and difficult mortgage approvals. Some new launches carry prices reminiscent of 2015, even though land, materials and labour have become more expensive.
The Thai Condominium Association says some developers paused launches during the first half of 2025 before returning in the third quarter with aggressive prices. Project sponsors that once earned margins near 30 percent are cutting them deeply to generate sales. A profit margin is the share of sales revenue left after the relevant costs are paid.
Bangkok's large stock of unsold condominiums gives buyers plenty of alternatives. Developers must compete on the price and payment terms as well as location, design and amenities, while banks remain cautious about lending to households already carrying substantial debt.
The pressure is uneven. More affordable projects outside the centre are competing hard for buyers, while some expensive downtown developments continue to sell strongly. The result is a market in which a lower launch price can sit alongside resilient luxury sales and an active rental business.
How far have prices moved?
The Rama IV launch price is about 30,000 baht per square metre below a comparison price of 150,000 baht. Because the nearby earlier launches exceeded that level, the gap is more than 20 percent. These are comparisons between projects launched at different times, rather than a reduction applied to every existing apartment.
Tha Phra's range of 60,000 to 70,000 baht per square metre gives buyers another route to a lower purchase price. Developers are targeting both investors prepared to wait for construction to finish and people buying homes for themselves who need manageable payments.
Consultancy figures for the second quarter show average asking prices of about 239,475 baht per square metre in the central business district. That was unchanged from the previous quarter but lower than a year earlier. Asking prices on the city fringe slipped to about 126,897 baht per square metre, while suburban prices eased to 72,193 baht.
The average selling price for newly launched projects fell to about 89,500 baht per square metre in the second quarter, from more than 144,000 baht in the first quarter. That is a decline of roughly 38 percent, reflecting a shift in launches toward cheaper inventory in outer areas as developers seek prices more buyers can afford.
Asking prices and the final cost to a buyer can also be different. Competition and unsold stock have limited increases in advertised prices, while discounts and promotional packages have pushed the effective purchase cost lower in many neighbourhoods.
Higher building costs squeeze developers
Land near transit lines remains expensive, and the construction cost index rose roughly 4 percent from a year earlier. Materials, including tiles and sanitary ware, cost more, while labour costs have also increased.
Those expenses would normally put upward pressure on new home prices. Instead, developers are accepting thinner margins, offering discounts and adding free items to reach monthly payment levels their customers can manage. A lower selling price leaves less room to absorb rising costs.
Smaller homes and sharper promotions are helping some projects sell in the city fringe and suburbs, where buyers are especially sensitive to price. The central business district has held up better, although its decline from a year earlier shows that prime locations also face softer demand.
Unsold homes reshape the launch calendar
Bangkok entered 2025 with a substantial backlog of unsold condominiums. Developers slowed new projects, offered existing stock at more competitive prices and concentrated on turning completed or previously launched units into cash.
Several market trackers recorded a sharp fall in launches compared with 2024, although their estimates vary by survey. Some put second quarter launch volumes at their weakest since 2009. Many of the projects that did enter the market were outside the central area, where developers could offer more accessible total prices.
Late in 2024, thousands of new units came onto the market while the sales rate hovered in the mid 30 percent range, below the level regarded as healthy. That weak pace continued into 2025, encouraging larger developers to reduce releases, clear inventory and preserve cash.
The recent sequence shows how the slowdown developed:
- In late 2024, thousands of new condominium units were launched, but sales rates remained around the mid 30 percent range.
- During the first half of 2025, some developers paused launches, and residential property transfers fell from a year earlier.
- In the second quarter of 2025, some surveys recorded the weakest launch volumes since 2009, while the average selling price of new projects fell to about 89,500 baht per square metre.
- In the third quarter of 2025, some developers returned with aggressive pricing intended to attract buyers with limited purchasing power.
Some companies have diversified into low rise housing or markets such as Phuket, where foreign demand is stronger. Others are releasing only portions of projects to test demand, adjust prices and, where necessary, move toward smaller or more affordable layouts.
Frank Khan, executive director and head of residential at Knight Frank Thailand, expects the inventory backlog to keep pressure on prices and promotions throughout the year:
What we will see is an influx of unsold inventory entering the market. Developers will lower prices and offer more promotions. Like last year, it will remain a buyer's market.
Why cheaper homes still struggle to find buyers
Household debt and uncertainty are limiting demand even as developers reduce prices. Many buyers are unwilling to make a large, lasting financial commitment while they are unsure about the economy and political stability.
Khan describes the concerns keeping households on the sidelines:
The world is full of wars and negative news, so people are reluctant to commit. They are waiting for stronger economic conditions and political stability, which are critical factors.
Banks have also tightened mortgage approvals. Rejection rates rose through 2024, with industry estimates putting denials at a high share of applications. Non performing loans, meaning loans on which borrowers have fallen behind, have increased.
Lenders are taking a conservative approach to debt service ratios and loan to value thresholds. The first measures how much of a borrower's income goes toward debt payments. The second compares the size of the mortgage with the value of the property securing it.
For many buyers in the middle of the market, the practical choices are to save for longer, purchase a smaller unit or continue renting. A developer can offer a discount, but the buyer still needs enough income and a financial record that satisfies the bank.
Residential property transfers fell from a year earlier in the first half of 2025. Mortgage growth has remained subdued despite central bank interest rate cuts and temporary support measures, showing how difficult it has been to turn lower costs into completed purchases.
Policy support meets strict lending standards
Reductions in property transfer and mortgage fees, together with relaxed loan to value rules, are intended to ease the burden on first time buyers. Lower fees reduce transaction costs, while more flexible loan limits can reduce the cash a buyer needs at the outset.
Banks still apply strict credit standards, so the improvement from those policies has been gradual. Easier borrowing limits help only when a lender is satisfied that the applicant can repay the loan.
Developers face financing pressure of their own. Debentures coming due create refinancing risks, and listed developers report substantial long term debt. Debentures are borrowing instruments that companies must repay or replace with new financing when they mature.
Those obligations increase the urgency of converting unsold homes into cash. Large discounts, free furnishings and flexible payment plans are ways to keep sales moving while mortgage approval rates remain weak.
Buying before completion or moving in now
New projects sold before construction is complete can offer entry prices below those of homes ready for occupation. Investors who can wait for handover may choose them in the hope that values will rise as the market stabilises.
Buyers purchasing a home for themselves often favour completed units, even when the price per square metre is higher. They can move in immediately and avoid the risk that construction takes longer than expected.
Both choices require a comparison of the effective price after promotions. A cash discount, furniture package, contribution toward transfer fees or flexible payment schedule changes the value of an offer. Comparing the advertised price alone can leave out a meaningful part of the purchase cost.
Selective releases also mean that a developer may bring only part of a project to market at first. That allows the company to judge demand before committing to a wider release and to adjust its mix of units when sales are slow.
Luxury homes and rentals show greater strength
Prime and super prime condominiums remain more resilient, with many projects recording take up rates above 80 percent. Take up describes the proportion of units sold. Homes priced at roughly 320,000 to 500,000 baht per square metre and branded residences associated with leading hotel names continue to attract wealthy buyers.
Rare downtown properties also stand out. Large apartments with two or three bedrooms remain in short supply, and sales of completed downtown units have been strong. Their scarcity gives them a different position from projects competing with large numbers of similar homes.
Bangkok's expatriate population increased in 2024, while the tourism recovery has helped keep rental demand active in key districts. In the prime segment, rents have risen for several consecutive quarters as expatriates and corporate tenants return.
Gross rental yields of around 6 percent are achievable in many segments. Gross yield compares annual rent with the purchase price before expenses are deducted. For investors seeking income while waiting for property values to stabilise, that rental stream can be an attraction.
Foreign buyers account for a meaningful share of Bangkok condominium activity by both unit numbers and transaction value. Chinese, Myanmar, Russian and European buyers are present, although their purchasing volumes change with confidence and wider economic conditions.
Transit locations, riverside neighbourhoods and parts of Sukhumvit attract both Thai and foreign demand. Prices there can be more resilient than in projects serving mainly suburban buyers. Developers targeting these customers have focused on quality, larger floor plans, services and branding.
Safety becomes part of the buying decision
Regional tremors earlier in 2025 brought renewed scrutiny to high rise living. Social media discussions and consumer surveys showed some buyers placing greater weight on structural design, certification and maintenance records.
Thailand's building codes and engineering standards are designed to address seismic risk under Bangkok's soil conditions. Developers have responded to buyer concerns by providing more detailed information about construction safety and demonstrating engineering systems at their sites.
Construction quality has become another part of the sales conversation alongside price and financing. Buyers already seeking reassurance about the economy are also looking for clear information about how a building was designed, built and maintained.
What buyers can check before committing
Bangkok's unsold inventory gives buyers room to negotiate, but the lowest advertised price is only one part of a purchase. Mortgage access, construction timing, developer finances and the likely cost of owning the unit all affect whether a home is affordable.
Several checks can help buyers compare the options:
- Seek bank pre approval early to establish a realistic borrowing limit and strengthen your position when discussing terms with sales teams.
- Consider transit access, established amenities and neighbourhood rental demand alongside the price per square metre.
- Compare effective prices after cash discounts, transfer fee support, furniture packages and payment terms.
- Check construction milestones, escrow protections and refund policies in the event of delays.
- Review the developer's record of completing projects and its upcoming debenture maturities to assess delivery risk.
- Ask for structural certificates, material specifications and warranties, and visit completed projects by the same contractor where possible.
- For a rental investment, compare achievable rents at nearby properties and deduct service charges when estimating net yield.
Investors also need to distinguish the gross rental figure from the income left after costs. Buyers seeking a home need to weigh any saving from an unfinished project against the value of moving into a completed unit immediately.
What could bring demand and supply closer together?
Lower interest rates could reduce monthly mortgage payments and help some applicants qualify for loans. Continued fee reductions and targeted support for first time buyers could also encourage households that have postponed purchases.
Growth in the expatriate population and steady tourism would support rentals, giving investors another reason to buy. Fewer launches and more selective releases could allow existing homes to sell before a large amount of new stock arrives. That process would gradually reduce the unsold pool.
Thailand's economy is on a slow growth path in 2025, with contained inflation. An ageing population and high household debt remain constraints on demand. Developers nevertheless have projects ready and marketing budgets set, making bursts of activity likely when interest rates fall or incentives are extended.
No firm date has been given for a broader recovery. Through the next few quarters, stronger confidence, more affordable financing and restraint in new supply would help the market absorb its backlog. Until then, developers' need for sales and cash is likely to keep discounts and promotions central to the competition for buyers.
Key Points
- Some Bangkok launches are priced near 2015 levels as developers cut margins that once approached 30 percent.
- New prices include about 120,000 baht per square metre in Rama IV and 60,000 to 70,000 baht in Tha Phra.
- The average selling price of new launches fell to about 89,500 baht per square metre in the second quarter, reflecting a shift toward cheaper outer areas.
- Unsold inventory, household debt and strict mortgage approvals are keeping pressure on sales despite policy support.
- Some surveys put second quarter launch volumes at their lowest since 2009.
- Many prime and super prime projects have take up rates above 80 percent, while gross rental yields around 6 percent remain achievable in many segments.
- Buyers need to compare financing, effective prices, completion risks, developer finances and building safety before committing.