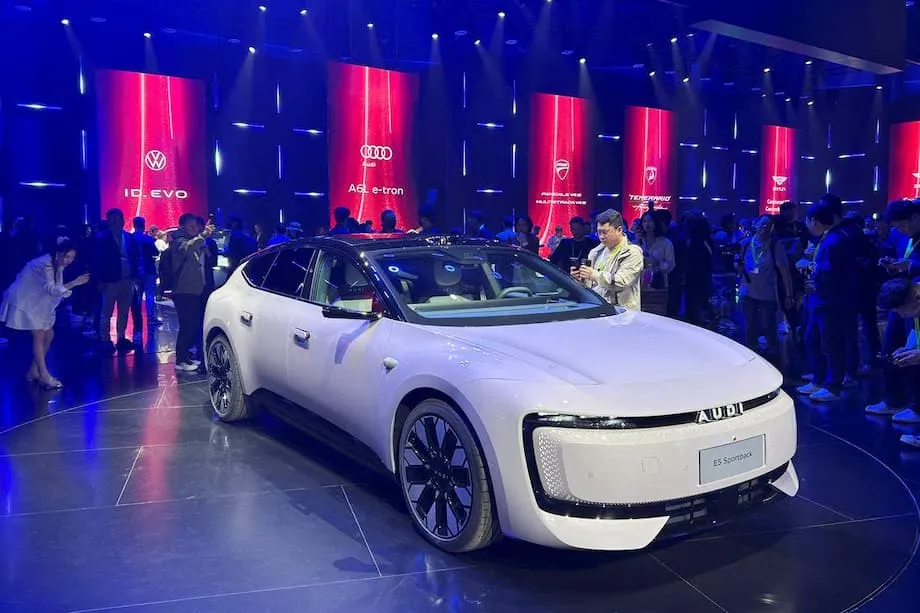
Audi's 18 months reveal a new pace for electric cars
Audi developed its E5 Sportback for China in 18 months using core technology from local partner SAIC, including batteries, electric motors, infotainment and driver assistance. The project followed a surprise for senior Audi managers: the Zeekr 001, a long range electric fastback combining European styling with Chinese software and battery expertise, showed how quickly their competitors were advancing.
Contents
- Audi's 18 months reveal a new pace for electric cars
- How policy and scale built China's advantage
- Batteries and software change the engineering
- Partnerships spread from Audi to Renault and Toyota
- Could a Chinese core sit beneath a global badge?
- CATL offers the engineering beneath the body
- China protects technology as it sells it abroad
- Tariffs redraw the routes into overseas markets
- A price war at home pushes expansion abroad
- What established brands gain and put at risk
- What buyers and climate goals stand to gain
- What to Know
Stefan Poetzl, who leads sales and marketing at SAIC Audi, described the reaction to the Chinese model:
The Zeekr 001 back then shocked quite everyone. We needed to do something about it.
By September 13, 2025, the response extended far beyond Audi. Volkswagen, Toyota, Renault and Ford were seeking Chinese platforms, electronics or software to bring electric vehicles to market faster and at lower cost. Chinese companies, facing fierce competition at home and trade barriers abroad, were finding customers for technology as well as finished cars.
The shift reaches deeper than buying cheaper parts. A platform is the shared engineering base beneath a vehicle, including major mechanical and electrical systems. Buying one can change how a car is designed, which company controls its software and how much work a familiar brand performs itself.
Chinese suppliers increasingly offer complete chassis and electronics packages, effectively the foundations of an electric car in a box. Licensing agreements and overseas factory deals give them additional ways to earn money when exporting a finished vehicle becomes expensive or politically difficult.
For established manufacturers, the attraction is immediate: development that traditionally takes four or five years can move closer to two, potentially saving billions of dollars. The longer challenge is preserving the engineering, driving experience and identity that make customers choose one badge over another.
How policy and scale built China's advantage
China's electric vehicle industry grew from national and local policies dating to the early 2000s. Public support funded research, pilot fleets and government purchasing. Subsidies and tax breaks made vehicles cheaper for buyers while giving domestic manufacturers time to improve their products.
Cities strengthened demand by exempting electric cars from license plate restrictions and switching buses and taxis to electric power. These measures helped create a large home market in which manufacturers could expand production and compete.
Global electric car sales approached 14 million in 2023, with China registering about 8.1 million, far ahead of Europe and the United States. Those figures put China's share at roughly 58 percent. Electric cars represented around 18 percent of all global car sales that year.
The development spans two important periods:
- Early 2000s: national and local policies began prioritizing electric mobility through research, pilot fleets and public purchasing.
- 2023: global electric car sales neared 14 million, including about 8.1 million registrations in China.
China also developed a deep supply chain. Its companies became dominant in refining key minerals and making battery components, giving domestic carmakers a more predictable flow of materials and parts. Tesla's Shanghai factory benefited from the same industrial environment, demonstrating that foreign companies could also gain from China's electric vehicle ecosystem.
Batteries and software change the engineering
Chinese battery producers refined lithium iron phosphate, or LFP, cells, which are cheaper and more durable than many chemistries based on nickel. Better pack layouts and temperature management increased energy density, the amount of energy stored in a given space or weight, while improving safety and reducing cost.
Battery development extends beyond the cells themselves. Blade style packs fit cells together more efficiently, while lithium manganese iron phosphate, or LMFP, is moving from laboratories into production. Improvements in cooling, battery management software and the way packs fit into a vehicle support more affordable cars with the driving range buyers want.
Batteries remain the largest individual item in an electric vehicle's materials bill, making them central to price, range and safety. A manufacturer that reduces battery costs can lower the showroom price or provide more capability for the same money.
Chinese consumers' interest in connected features and frequent software updates has also encouraged manufacturers to design vehicles around software from the beginning. Functions ranging from cockpit displays to driver assistance increasingly depend on code rather than separate pieces of dedicated hardware.
Modular engineering ties these changes together. A skateboard chassis places standardized batteries, electric motors and power electronics beneath different vehicle bodies. A centralized electronic architecture gives the car a shared computing structure, allowing manufacturers to develop several models around a stable core.
Software updates delivered over the air can fix problems or add features after purchase without a dealer visit. For established carmakers with complicated internal organizations, adopting a mature Chinese platform or electronics layout can remove years of development work.
Partnerships spread from Audi to Renault and Toyota
Audi's E5 Sportback is one example of a widening set of partnerships. Volkswagen is developing models with Xpeng specifically for China and evaluating its electronics and software architecture. Toyota has worked with GAC on products for the Chinese market.
Renault's budget Dacia Spring for Europe uses a platform from Dongfeng. The next Twingo is being engineered out of Shanghai with help from a Chinese electric vehicle engineering company. Ford has been scouting for a Chinese partner to supply an electric vehicle platform.
Leapmotor's global alliance with Stellantis includes technology licensing and exports of complete vehicles. Together, these arrangements show several routes into international markets: supplying engineering, sharing development or selling finished cars through a larger partner.
Chinese companies gain another source of revenue while a domestic price war squeezes margins. Their customers gain access to packages that can include a chassis, battery integration, powertrain software and advanced driver assistance systems, or ADAS, which help drivers with parts of the driving task.
Could a Chinese core sit beneath a global badge?
Industry executives compare the shift with the computer industry's Intel Inside model of the 1990s, when one company's chips powered machines sold under many different brands. In electric cars, the less visible product is the platform and electronic backbone beneath the bodywork.
Volkswagen's work with Xpeng illustrates the approach. The aim is to bring a more agile architecture centered on software into vehicles for China, with possible wider use later. Yale Zhang, managing director at consultancy AutoForesight, described how that strategy might expand:
If it works in China, Volkswagen could apply the strategy globally.
Industry consultants see a practical exchange. Established brands buy time and reduce development risk while rebuilding their own software and battery capabilities. Chinese companies sell technology already used in a demanding and intensely competitive market.
Experience in that market can reduce uncertainty about quality and functionality. A manufacturer still has to create its own product, but it starts with a core that has already been developed and used, rather than designing every major system itself.
CATL offers the engineering beneath the body
Battery suppliers are moving beyond selling cells. Some now offer complete rolling platforms containing battery trays, suspension mounting points and high voltage systems. These packages place more of a vehicle's essential engineering in the hands of a supplier.
CATL's Bedrock chassis, shown recently in Europe, is designed to standardize the heavy engineering underneath while allowing manufacturers to vary the body above it. Hu Guoliang, an executive at CATL, presented the idea as a way to give buyers more choice:
The chassis will allow consumers to decide what an EV looks like, rather than having giant carmakers decide what to sell.
Sharing a base could allow manufacturers to spend more of their resources on appearance, cabin design and the features customers see and use. The commercial question is how much of the value remains with the brand selling the car and how much moves to the company supplying its core.
China protects technology as it sells it abroad
China is also tightening control over sensitive battery expertise. New rules require licenses to transfer several key battery manufacturing technologies overseas, including processes associated with cathode materials and lithium extraction. Cathode materials are part of the chemistry that allows a battery to store and release energy.
The controls aim to protect China's technological lead and guide foreign cooperation through controlled routes, including plants in China and licensing agreements. This creates a tension for companies that want both international customers and continued control over valuable manufacturing knowledge.
Europe and North America, meanwhile, want more battery production within their own borders. One model is technology licensing without Chinese equity control: a Western partner operates a factory using Chinese battery expertise, rather than the Chinese company owning a stake in the plant.
Such arrangements separate the location and ownership of production from the origin of the technology. They give manufacturers another option as governments scrutinize where batteries, software and vehicles are made.
Tariffs redraw the routes into overseas markets
The United States raised its tariff on Chinese electric cars to 100 percent, a level that largely shuts those vehicles out of its market. Canada also lifted its tariff to 100 percent. These measures protect domestic industrial ambitions but can limit access to cheaper vehicles and slow adoption in the near term.
The European Union announced provisional duties of up to 37.6 percent to counter subsidies while finalizing its investigation. Mexico proposed a 50 percent tariff on cars from countries without a free trade agreement. That proposal would weigh heavily on vehicles made in China and could also affect models routed through Mexico by brands without local factories.
Mexico's proposal still required congressional approval. Chinese manufacturers therefore faced different conditions across their target markets, from very high barriers in North America to opportunities elsewhere.
China has responded through trade forums and targeted retaliation, while signaling that controls on exports of critical minerals and battery processes are available. Manufacturers have responded by considering assembly in third countries, accelerating European factory projects and using licensing to separate technology transfers from final assembly.
Europe is seeking battery and vehicle investment to retain more production value within the bloc. Hungary has become a focal point for major battery factories and new vehicle projects connected with Chinese partners.
A price war at home pushes expansion abroad
China's domestic market combines excess production capacity with aggressive price competition. Only a fraction of manufacturers operate their factories close to efficient utilization, meaning many plants produce less than the volume needed to spread costs effectively.
BYD has more room than many rivals to lower prices because it produces much of what goes into its vehicles, from battery cells and chips to power electronics. This vertical integration, or making more components within the same company, helps it reduce sticker prices while remaining profitable.
Tesla's Shanghai operation has also maintained very high factory utilization, showing how production scale and disciplined processes support lower costs. Smaller Chinese brands face pressure to consolidate, even as new manufacturers emerge and technology companies enter the car market.
Exports offer growth, although they will not rescue every manufacturer. Chinese vehicles are reaching more showrooms in Southeast Asia, the Middle East and parts of Europe. With the United States largely closed by tariffs, companies are also concentrating on Australia and parts of South America.
Mexico has been a strong market for growth, although its proposed tariff could alter that opportunity. European factory plans offer another route around the cost of importing complete vehicles. Chinese technology can also reach customers inside cars carrying European or US badges.
What established brands gain and put at risk
Established manufacturers gain speed and greater certainty when a proven platform and electronics layout can support several models. They can direct more money and engineering time toward styling, suspension tuning, user interfaces and features specific to their brands.
Modern centralized computing systems can also simplify software updates. For companies built around engines and transmissions, a Chinese partnership offers a bridge toward vehicles organized around software, batteries and power electronics.
The risk is dependence. Sharing the same core can make cars less distinctive, while relying on a partner can reduce control over costs, future product plans and data. Former Aston Martin chief executive Andy Palmer warned about outsourcing too much of the vehicle:
In the long term, you're screwed because you're just a retailer.
Some manufacturers are mixing purchased technology with their own work. They use a partner's platform but retain their own human machine interface, the controls and displays through which people interact with the car, along with safety software and chassis tuning.
Others jointly develop electronic systems while keeping software, data handling and cloud services within their own organizations. Partnerships often begin in China, where pressure to launch quickly is greatest, with the possibility of adapting the approach elsewhere if it succeeds.
What buyers and climate goals stand to gain
Consumers continue to judge electric vehicles on price, range and charging access. Desired range in everyday driving clusters around 500 kilometers, and many buyers are unwilling to pay more than they would for a comparable gasoline model.
Chinese cost structures help manufacturers address those demands. LFP batteries, integrated production and efficient factories can support lower prices without removing features. Rivals then face pressure to reduce costs themselves or work with partners that already have those capabilities.
Electric car sales remain concentrated in China, Europe and the United States, but growth is picking up in Southeast Asia and Latin America. Faster development can bring more models to these markets, while partnerships put established battery systems, driver assistance and infotainment into familiar brands.
Buyers can expect more choice, better range for the money, larger screens and smarter voice controls. Small, efficient cars are receiving renewed attention as some countries explore incentives favoring lighter vehicles. A growing used electric vehicle market can also widen access as early models pass to second owners.
Climate goals depend partly on whether those cars become affordable quickly enough. Electric vehicles can reduce emissions, with greater benefits when their electricity comes from cleaner grids. Tariffs may support local industry while slowing access to cheaper models, and fragmented supply chains can increase costs and delay production.
Governments are balancing consumer adoption with energy security and industrial strategy. Battery recycling and more varied mineral supplies are gaining attention as ways to reduce environmental damage and dependence on concentrated supply chains. The practical test for licensing, partnerships and local factories is whether they can preserve affordable vehicles while meeting political constraints.
What to Know
- Audi developed its E5 Sportback for China in 18 months using SAIC batteries, motors, infotainment and driver assistance technology.
- Volkswagen, Toyota, Renault, Ford and Stellantis are pursuing different forms of cooperation with Chinese companies.
- China registered about 8.1 million of nearly 14 million electric cars sold globally in 2023, roughly 58 percent.
- Chinese suppliers are selling complete platforms as well as batteries, electronics and software.
- New Chinese licensing rules cover transfers of several battery manufacturing technologies abroad.
- The United States and Canada raised tariffs on Chinese electric cars to 100 percent; the EU announced provisional duties of up to 37.6 percent.
- Mexico proposed a 50 percent tariff on cars from countries without a free trade agreement, subject to congressional approval.
- Overseas factories and technology licensing offer alternative routes to customers facing import barriers.
- Established brands gain development speed but risk dependence on suppliers for core technology and data.
- Consumers may gain more choice and better value, while tariffs and supply chain divisions can slow access to affordable electric cars.