A new cost could reach the checkout
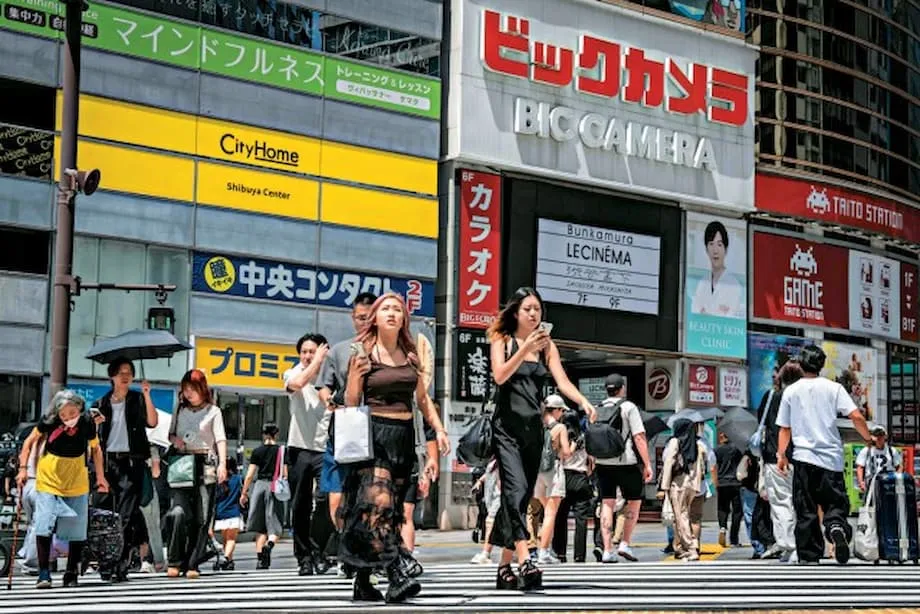
Japan's major card companies are studying a surcharge of 1 to 3 percent on purchases made with credit cards issued abroad, as a record tourism boom puts pressure on payment processors. Companies including Mitsui Sumitomo Card and Mitsubishi UFJ Nicos have examined the option, which could add 200 to 600 yen to a restaurant bill of 20,000 yen.
Contents
- A new cost could reach the checkout
- Why overseas cards cost more to process
- How a 10,000 yen purchase can create a loss
- Who would collect the money?
- What shops and residents would need to watch
- Separate prices are already appearing
- Mount Fuji shows another response to visitor pressure
- How much could a visitor pay?
- What has happened, and what comes next?
- Ways travellers can limit payment costs
- How the proposal compares with visitor fees elsewhere
- What to Know
As of September 7, 2025, the proposal remains under review. Government officials have indicated that they will consult card companies and merchants in the coming months, with details expected afterward. No launch date has been given, and the method of collecting any charge has yet to be settled.
Japan welcomed a record 36.87 million international visitors in 2024. A large share of their spending goes through cards, creating more transactions in which Japanese payment companies must pay fees to overseas banks and global networks. Those costs can exceed what the companies collect from shops, restaurants and other businesses.
A survey of eight large card firms found that six had seen their deficits on transactions using cards issued abroad increase from a year earlier. Industry estimates put the shortfall at about 70 to 80 yen per transaction and as much as 30 billion yen annually.
The proposed charge would be a measure led by the card industry, rather than a national tourist tax. Its reported scope concerns where a card was issued. That matters for visitors carrying overseas cards, but also for residents of Japan who use an overseas bank.
Why overseas cards cost more to process
Japanese merchants often pay relatively low fees to accept cards, averaging around 1.9 percent and sometimes falling below 1 percent for large retailers. These fees are the money a business pays its payment provider for handling a sale.
A card transaction involves several organisations. The issuer is the bank or company that supplied the customer's card. The acquirer is the company that handles the merchant's card payments. Networks such as Visa and Mastercard connect the two sides so money can move from the customer's account to the business.
Japan's domestic payment structure often keeps costs in check when both the issuer and the acquirer are local. A purchase with a card issued overseas changes the calculation. The Japanese acquirer must pay brand fees to Visa or Mastercard, charges for processing payments across borders, and interchange fees to the foreign issuer.
Interchange is a payment that passes from the merchant's side of the transaction to the card issuer. The acquirer also faces domestic system costs. If the merchant pays a very low acceptance fee, these outgoing payments can add up to more than the acquirer receives.
The weak yen has helped draw more visitors to Japan, while growing card use has increased the volume of these transactions. For processors, more tourist spending can therefore mean a larger accumulated loss, even when the shops receiving the money benefit from stronger sales.
How a 10,000 yen purchase can create a loss
A purchase of 10,000 yen at a large chain illustrates the problem. If the chain pays a merchant fee of 0.9 percent, the Japanese acquirer receives 90 yen for handling the payment.
Industry commentary puts network charges at around 1.0 to 1.1 percent for Mastercard or Visa in the example, with interchange and domestic system costs also part of the calculation. The estimated result is a deficit of about 70 to 80 yen on the transaction.
Millions of purchases during busy tourism periods can turn that small shortfall into a substantial annual cost. The industry estimate of losses reaching 30 billion yen a year reflects the scale of inbound spending, rather than a large loss on any single sale.
Reducing the network charges is difficult because global networks publish standard rates that individual markets have limited ability to change. Some Japanese card companies are therefore considering a targeted charge on cards issued abroad to bring those payments back to break even.
The proposed 1 to 3 percent range would add 100 to 300 yen to a purchase of 10,000 yen. The final rate, coverage and collection method remain part of the discussions, including how the charge would fit different merchant contracts and payment costs.
Who would collect the money?
Card companies have several possible ways to pass on the additional cost. One option is a visible surcharge for the cardholder, displayed when a payment terminal identifies a card issued abroad.
Merchants could instead post separate prices, with a higher total for purchases made using an overseas card. Processors could also change settlement arrangements so the additional cost is borne by the cardholder rather than the merchant, or adjust fees behind the scenes for sectors attracting heavy tourist traffic.
Mitsui Sumitomo Card and Mitsubishi UFJ Nicos are among the major firms that have examined a surcharge. The government's expected role centres on consumer protection, clear disclosure and consistent application across businesses and sectors.
Global card networks would need to be involved. Any collection model would have to comply with their rules and Japan's requirements for displaying prices. Clear notices would be necessary so shoppers know the total before paying.
Refunds and chargebacks also need rules. A chargeback is a process through which a cardholder disputes a payment and seeks its reversal through the card issuer. Companies would need to decide how an additional fee is handled when the underlying purchase is refunded or disputed, and how it interacts with shopping that qualifies for tax relief.
What shops and residents would need to watch
Retailers would likely need to update payment software, post notices and train staff. Their terminals would have to recognise cards issued outside Japan reliably and apply the charge only to the transactions covered by the eventual rules.
Stores already handling paperwork for tourist purchases without consumption tax would face another checkout procedure. Staff would need to explain any extra amount while keeping the payment total consistent with the displayed price and the customer's tax treatment.
Residents using overseas banks are a particular concern. A rule based on the place where a card was issued could reach someone who lives in Japan, even though the discussion is often framed around tourists. Careful procedures would be needed to address mistaken application under whatever eligibility rules are adopted.
A phased introduction is possible. Companies could begin in sectors where losses are greatest, including large retailers paying very low merchant fees, or in places with heavy tourist traffic. Pilot programmes in selected cities could precede wider adoption.
The aim under discussion is to align the cost of processing a payment with the person using that payment method, while keeping the checkout simple enough for visitors to understand. The scale of adoption and the clarity of notices would shape how noticeable the change becomes.
Separate prices are already appearing
Japan's debate over different prices for visitors and residents extends beyond card payments. A new theme park in Okinawa lists higher prices on its English website than on its Japanese website, which requires local contact details.
Tabelog, a major restaurant platform, operates separate booking systems for domestic and inbound customers. Foreign users pay a system fee of 440 yen per person. Some Tokyo restaurants have also introduced tourist surcharges or higher prices for visitors, citing additional staff time and service costs.
Supporters of different pricing argue that visitors do not contribute to local budgets through income taxes and that serving international customers requires extra resources. They also say a single price can become unaffordable for residents when rising visitor demand pushes costs upward.
Critics focus on fairness and unclear eligibility. Foreign residents who have lived in Japan for a long time sometimes find themselves treated as tourists, provoking public backlash. Advocates of clearer rules favour criteria based on residency rather than subjective decisions at the door.
A charge tied to a foreign card would add another form of price difference. Its defining feature would be the payment instrument, while the other examples involve booking systems, visitor status or access to a particular service.
Mount Fuji shows another response to visitor pressure
Public authorities have also adopted charges for visitors in specific settings. Prefectures approved a trail entry fee of 4,000 yen for the 2025 Mount Fuji climbing season to manage crowding and safety.
Natsuko Sodeyama, an official with Shizuoka prefecture, described the concentration of visitors during the mountain's short climbing season and the reason for restrictions:
There is no other mountain in Japan that attracts that many people in the span of just over two months," Sodeyama said. "So some restrictions are necessary to ensure their safety.
The Mount Fuji charge pays for access under a public management system. The proposed card surcharge would address private payment processing costs. Both developments reflect the pressure that intense visitor demand can place on local services and infrastructure.
How much could a visitor pay?
A surcharge of 1 to 3 percent would add 200 to 600 yen to a restaurant bill of 20,000 yen. On shopping worth 100,000 yen, the additional cost would be 1,000 to 3,000 yen.
A traveller's own bank may already charge a foreign transaction fee of about 3 percent, unless the customer uses a card that waives it. If both that bank fee and Japan's proposed surcharge apply, the combined cost could reach roughly 4 to 6 percent of the purchase amount.
Dynamic currency conversion can add another expense. This is the option offered by some terminals or websites to charge a customer in their home currency instead of yen. The conversion rate usually adds a few percentage points compared with the customer's bank rate. Choosing yen typically produces a better result.
Eligible tourists can still save through purchases without Japan's 10 percent consumption tax. Many retail goods qualify when customers present a passport and meet spending thresholds. Even with a card surcharge, the final cost of eligible goods could remain below the resident price once the tax is removed.
Japan's Ministry of Foreign Affairs also warns about possible costs for overseas cards in its online consular payment guidance. The ministry states:
Exchange fees may be charged for credit cards issued outside Japan.
Travellers therefore need to consider several parts of a bill: the merchant's price, any proposed surcharge in Japan, their bank's fee and the exchange rate used to convert the payment.
What has happened, and what comes next?
Japan's record visitor numbers in 2024 and the pricing changes seen in 2025 provide the setting for the card industry's discussions. The sequence is:
- 2024: Japan welcomed a record 36.87 million international visitors.
- 2025: Prefectures approved a Mount Fuji trail entry fee of 4,000 yen for the climbing season.
- September 7, 2025: Major card companies were studying charges of 1 to 3 percent on cards issued abroad, with the proposal still under review.
- The coming months: Government officials indicated that consultations with card companies and merchants would take place, with details expected afterward.
Payment companies must resolve how terminals identify overseas cards, how customers see the fee, and how refunds, chargebacks and purchases without consumption tax are handled. Global networks will have a role in disclosure standards and consumer protections.
Selected sectors or cities could be used for an initial rollout. Businesses with especially low merchant fees and locations attracting large numbers of tourists are possible starting points, but these remain options under consideration.
Ways travellers can limit payment costs
Travellers would not need to abandon cards if the proposal proceeds. The most useful preparation is to check how their bank charges for overseas purchases and withdrawals, then compare the payment options offered at the checkout.
- Use a credit card without foreign transaction fees. Many cards designed for travel waive the usual fee of about 3 percent.
- Avoid withdrawing cash with a credit card. Cash advances often incur separate fees and begin accruing interest immediately. A travel debit card or prepaid travel card is an alternative.
- Decline dynamic currency conversion and choose yen. The customer's bank usually offers a better exchange rate than the merchant's conversion option.
- Carry some cash for small purchases. ATMs at 7 Eleven and Japan Post Bank tend to accept many foreign cards. Checking a bank's international ATM partners can help reduce withdrawal fees.
- Consider Suica or Pasmo transit IC cards for transport and convenience store purchases. Visitors often need cash to top up physical cards. Mobile top ups and automatic charging features are limited for people who are not residents or for particular phones.
- Keep receipts showing any foreign card fee. Residents using overseas bank cards should watch for mistaken application and raise it with the merchant or card company.
- Use shopping without consumption tax where eligible. Present a passport, meet the spending requirements and follow store instructions to remove the 10 percent tax on qualifying goods.
Available payment choices will matter as much as the surcharge rate. Clear notices and practical alternatives would help visitors decide how to pay before a purchase is completed.
How the proposal compares with visitor fees elsewhere
Other destinations charge visitors to manage crowds or fund upkeep. Examples include Bhutan's daily sustainable development fee, New Zealand's international visitor levy, Bali's tourism tax, Thailand's entry fee for air arrivals, Venice's day charge on peak dates and higher prices at prominent sites such as Machu Picchu.
Those examples concern public fees or access prices. Japan's proposed foreign card surcharge would focus on the infrastructure used to process purchases, rather than an arrival point or attraction entrance. The shared idea is that visitors contribute toward additional costs associated with their presence.
For Japan, the immediate issue is how to cover losses on overseas card payments without making transactions confusing. The companies considering the charge, the government and global networks still have technical and consumer protection decisions to make before shoppers know what would appear on their bills.
What to Know
- As of September 7, 2025, Japanese card companies were studying a surcharge of 1 to 3 percent on credit cards issued abroad.
- Mitsui Sumitomo Card and Mitsubishi UFJ Nicos were among the firms examining the option.
- Six of eight large firms surveyed saw their deficits on foreign card transactions increase from a year earlier.
- Industry estimates put the shortfall at 70 to 80 yen per transaction and as much as 30 billion yen annually.
- Japan received a record 36.87 million international visitors in 2024, increasing the volume of overseas card payments.
- The proposal concerns an industry charge, with government involvement expected on disclosure and consumer protection.
- A surcharge could add 1,000 to 3,000 yen to shopping worth 100,000 yen, before any fee charged by the traveller's bank.
- Consultations were expected in the coming months. Collection rules, coverage and any phased rollout remained under discussion.
- Travellers can reduce other costs by using cards without foreign transaction fees, paying in yen, avoiding credit card cash advances and using eligible purchases without consumption tax.