Malaysia Takes the Lead as Regional Markets Move Apart
Malaysia has overtaken Indonesia for the first time to become the largest car market in the Association of Southeast Asian Nations (ASEAN), as strong national brands and rising demand for electric vehicles reshape competition across the region.
Contents
- Malaysia Takes the Lead as Regional Markets Move Apart
- National Brands Anchor Malaysia's Rise
- Electric Sales Surge From a Small Base
- Indonesia's Buyers Face Financial Pressure
- Thailand's Recovery Depends on a Changing Market
- Japanese Manufacturers Consolidate Their Thai Operations
- Vietnam Closes In on the Philippines
- Chinese Brands Expand Across ASEAN
- Factories and Transport Networks Adapt Together
- Policy Decisions Set the Pace Through 2050
- Key Points
As of August 7, 2025, the shift brings together several different stories. Malaysia is gaining strength through domestic demand, Indonesia is struggling with weaker household purchasing power, and Thailand is seeking a recovery while some Japanese manufacturers reduce their operations. Vietnam is growing quickly enough to challenge the Philippines for fourth place.
Perodua and Proton accounted for 63% of Malaysia's car sales in the first half of 2025. Electric vehicle sales rose 91% from a year earlier to 12,733 units, while hybrid sales increased 12% to 17,480. National brands remain the foundation of the market, even as newer types of vehicles attract more buyers.
Indonesia, despite a population of more than 280 million, faces a different picture. Car sales fell 21% in June 2025, against a backdrop of tighter credit and a shrinking middle class. Thailand is showing signs of recovery, with electric vehicles helping lift demand after a prolonged downturn.
The changing sales rankings also matter for factories, battery plants and transport networks. Governments and manufacturers are competing for investment while trying to serve buyers whose spending power varies sharply between countries. Malaysia's advance therefore sits within a wider shift in where cars are bought, how they are powered and where their components are made.
National Brands Anchor Malaysia's Rise
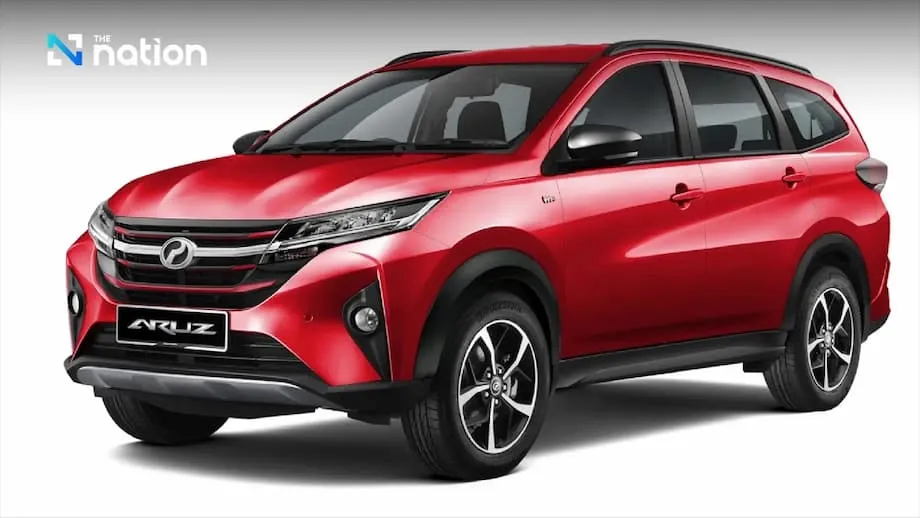
Perodua and Proton have built their position through indirect government support, partnerships with international manufacturers and close attention to local consumer preferences. Perodua works with Daihatsu, while Proton has a partnership with Geely.
The Perodua Alza and Proton Saga remain among the models leading sales charts. International models, including the Toyota Vios and Honda City, also remain popular, showing that Malaysia's market combines a strong domestic manufacturing base with continuing demand for established foreign brands.
The national brands' combined share of 63% means they accounted for nearly two out of every three cars sold during the first half of 2025. Their position gives Malaysia's market a substantial domestic anchor at a time when manufacturers across Southeast Asia face growing competition.
Electric vehicles are adding another source of growth. Government incentives, improvements to charging infrastructure and the arrival of competitively priced Chinese models have helped expand demand. The shift comes as fuel subsidies are phased out and petrol prices rise, changing the costs that buyers weigh when choosing a car.
Malaysia's leadership rests on both developments: established brands selling in large numbers and a smaller electric vehicle market growing quickly. The scale of the national brands remains much greater than the share held by electric cars.
Electric Sales Surge From a Small Base
Malaysia's 91% increase in electric vehicle sales during the first half of 2025 was much faster than the 12% growth recorded by hybrids. The two categories nevertheless contributed different volumes, with 12,733 electric vehicles sold compared with 17,480 hybrids.
Chinese electric vehicles accounted for nearly half of all new electric cars registered in Malaysia during the period. BYD delivered 5,434 units, ahead of Proton's 4,043 and Tesla's 2,399, putting the Chinese manufacturer at the front of this competition.
Models such as the Neta V, BYD Dolphin and MG ZS EV have attracted Malaysian consumers through affordability and reliability. Their arrival has widened the choices available to buyers considering a move away from petrol vehicles.
Electric vehicles still represented about 4.3% of Malaysia's total vehicle registrations. Rapid growth is therefore taking place within a relatively small part of the market. Petrol vehicles and other vehicle types continue to account for most registrations.
The government's targets point toward a much larger electric market: 15% of new car sales by 2030 and 80% by 2050. Reaching those levels would require electric vehicles to become a routine purchase for many more households, supported by the incentives, charging improvements and competitive models already helping demand.
Indonesia's Buyers Face Financial Pressure
Indonesia has traditionally been ASEAN's largest car market, but economic pressures in 2024 and into 2025 have weakened demand. The 21% fall in June 2025 was the first major decline since March 2024.
The country's middle class fell from 21.4% of the population in 2019 to 17.1% in 2024, a decrease of 4.3 percentage points. That change matters for an industry dependent on households being able to make a large purchase and, frequently, obtain financing.
Economists at Danamon Bank have linked weaker car sales to these pressures on consumers. Tighter approvals for vehicle loans, high household debt and a VAT increase have further reduced demand. Buyers face constraints both on what they can afford and on whether a lender will approve the money needed for a purchase.
Indonesia remains a major market, but the outlook for 2025 is cautious. Light vehicle sales are projected to rise only slightly, with continuing risks that demand could fall short of expectations.
The government is pursuing electric vehicle investment alongside efforts to support the wider market. The Indonesia Battery Integration Project aims to connect nickel mining, battery manufacturing and recycling in a complete battery supply chain.
Geely and Wuling are expanding their presence, while government incentives seek to attract more investment in electric vehicle production. Indonesia is therefore trying to build a stronger manufacturing role even as domestic buyers face financial strain.
Thailand's Recovery Depends on a Changing Market
Thailand has long served as a major manufacturing centre for global carmakers, particularly Japanese companies, earning the name Detroit of Asia. It produced 2.55 million vehicles in 2023, with projections pointing to nearly 3 million by 2028.
The automotive sector contributes more than 10% of Thailand's gross domestic product and supports millions of jobs directly and indirectly. Changes in vehicle demand consequently reach beyond showrooms to factories, suppliers and businesses serving the industry.
Domestic sales fell 16% in 2024, followed by a decline of 7% from a year earlier in the first quarter of 2025. High household debt, tighter approvals for vehicle loans and economic uncertainty have weighed on purchases.
The second quarter of 2025 brought an improvement: sales rose 3.6%, the first quarterly increase since the third quarter of 2022. Electric vehicles were a major driver of that recovery.
Thailand recorded 69,005 electric vehicle sales in the first half of 2025, up 33% from a year earlier and equal to 23% of total car sales. Electric vehicles therefore accounted for nearly one in four cars sold, giving them a much larger role in domestic demand than in Malaysia.
Thailand is supporting the change through subsidies, tax reductions and incentives for local manufacturing. Its goal is for electric vehicles to account for 30% of vehicle production by 2030. BYD and MG have already entered the country's top 10 brands by sales, increasing pressure on the Japanese manufacturers that have long dominated the market.
Japanese Manufacturers Consolidate Their Thai Operations
Honda is closing its Ayutthaya plant, Suzuki will shut its Thai assembly plant by the end of 2025, and Nissan is restructuring while preparing to close one of its two plants in Thailand.
These changes reflect wider shifts facing the manufacturers, including new United States tariffs and stronger competition from Chinese and other Asian automakers. For Thailand, they bring factory consolidation at the same time as investment in electric vehicles creates new areas of activity.
The country retains advantages for foreign investors. Its established supplier network, high use of locally sourced components and government incentives continue to support its appeal as a production base.
Thailand is also investing heavily in infrastructure suited to electric vehicles, research and development centres, and special economic zones such as the Eastern Economic Corridor. These efforts aim to preserve its role as a regional automotive powerhouse while the mix of manufacturers and vehicles changes.
Vietnam Closes In on the Philippines
Vietnam's economy grew 7.52% in the first half of 2025, its strongest growth in 15 years. A rising middle class and strong automobile sales are helping the country move toward overtaking the Philippines as ASEAN's fourth largest car market.
Car sales increased 18% in the second quarter of 2025 to 90,772 units. Greater purchasing power is supporting demand, while government policy is encouraging buyers to consider electric vehicles.
Battery electric vehicles receive registration fee waivers until 2027. VinFast, Vietnam's national electric vehicle manufacturer, sold 87,000 electric vehicles domestically in 2024, giving the country a substantial local participant in the shift toward electric transport.
Vietnam's growth also extends to hybrids and commercial vehicles. Infrastructure spending and new model launches are helping those categories, broadening the sources of demand beyond electric passenger cars.
Foreign investment, export growth and a favourable policy environment are supporting the market. Ongoing tariff negotiations and global trade tensions remain risks to its growth, connecting Vietnam's domestic momentum to decisions made beyond its borders.
Chinese Brands Expand Across ASEAN
BYD, MG, Wuling and Chery are investing heavily in local manufacturing, supply chains, and research and development across Malaysia, Thailand, Indonesia and Vietnam. Their affordable models and new technology are changing consumer choices and increasing competition with Japanese and Western brands.
Malaysia's electric vehicle registrations show how quickly these manufacturers have gained ground, with Chinese vehicles taking nearly half of the market. Thailand offers another measure of their progress, with BYD and MG among the top 10 brands by sales.
Singapore provides a further example: BYD was its leading electric vehicle brand in 2024. In Indonesia, Wuling and BYD have each secured 4% of the market as Chinese manufacturers increase their investment.
Their strategy reaches beyond selling imported cars. Investment in factories, batteries, components and development work is making ASEAN both a destination for vehicles and a production base serving broader electric vehicle ambitions.
For established manufacturers, the competition now involves price, model choice, technology and local production. For governments, attracting a factory or battery investment is part of a wider contest for manufacturing activity and the businesses connected to it.
Factories and Transport Networks Adapt Together
Automakers are localising production, establishing battery and component plants, and adjusting to changing trade flows within Southeast Asia. The growing presence of electric vehicles is changing what factories produce and what logistics companies must move.
Governments are investing in charging stations, electrification at ports and dedicated areas for handling and recycling batteries. Those investments connect the sale of a vehicle to the infrastructure needed to build, deliver, power and eventually recycle it.
Logistics providers face pressure to improve their digital capabilities, coordinate transport across different modes and keep supply chains dependable despite uneven demand and uncertain policy. A market containing electric vehicles, hybrids and vehicles with internal combustion engines also requires production and distribution networks to manage several technologies at once.
ASEAN's position as a competitive production base and an emerging electric vehicle export hub is expected to grow. Regional light vehicle sales are projected to reach 3.19 million units in 2025, representing a modest recovery rather than a uniform rebound across every country.
Global economic uncertainty, protectionist trade policies and the continuing need for infrastructure and innovation remain risks. Strong electric vehicle demand in one market can coexist with weak household spending or factory consolidation in another.
Policy Decisions Set the Pace Through 2050
Trade tensions, new tariffs imposed by the United States and policy uncertainty are affecting investment patterns and growth expectations across ASEAN. Vietnam and the Philippines are showing resilience, while Indonesia and Thailand are adjusting targets and adopting more accommodative monetary policies to support recovery.
Foreign direct investment presents a mixed picture. Electric vehicle projects are attracting a surge of investment, but global uncertainty has reduced the total number of projects. Governments are responding with incentives, infrastructure improvements and strategic alliances intended to attract investment and retain competitiveness.
The regional shift stretches across several years, with past changes in household finances, recent sales results and future policy targets all shaping manufacturers' decisions:
- 2019 to 2024: Indonesia's middle class shrank from 21.4% to 17.1% of the population.
- 2023: Thailand produced 2.55 million vehicles.
- 2024: Thailand's car sales fell 16%, while VinFast sold 87,000 electric vehicles in Vietnam and BYD led Singapore's electric vehicle market.
- First half of 2025: Malaysia's electric vehicle sales rose 91%, Thailand's rose 33%, and Vietnam's economy expanded 7.52%.
- End of 2025: Suzuki is due to close its Thai assembly plant.
- 2027: Vietnam's registration fee waivers for battery electric vehicles run until this year.
- 2028: Thailand's vehicle production is projected to approach 3 million units.
- 2030: Malaysia targets electric vehicles at 15% of new car sales, while Thailand targets them at 30% of vehicle production.
- 2050: Malaysia aims for electric vehicles to represent 80% of new car sales.
Malaysia's new position captures a regional market moving at different speeds. Domestic brands remain central to its success, electric vehicles are opening space for new competitors, and financial pressures continue to limit purchases elsewhere. The next stage of competition will involve both winning customers and securing the factories, components and transport systems needed to serve them.
Key Points
- Malaysia has overtaken Indonesia as ASEAN's largest car market for the first time.
- Perodua and Proton held 63% of Malaysian car sales in the first half of 2025, while electric vehicle sales rose 91%.
- Indonesia's June sales fell 21% as weaker purchasing power and tighter credit weighed on demand.
- Thailand returned to quarterly sales growth, with electric vehicles accounting for 23% of sales in the first half of 2025.
- Japanese manufacturers are reducing some Thai operations as Chinese brands expand their regional presence.
- Vietnam is moving toward fourth place in ASEAN, supported by economic growth, rising sales and electric vehicle incentives.
- Regional light vehicle sales are projected at 3.19 million in 2025, with trade uncertainty and uneven demand remaining risks.