Retirement savings overhaul targets unpaid benefits and weak returns
South Korea plans to require employers to keep money for retirement benefits outside their businesses, starting with workplaces employing at least 100 people in 2028 and reaching the smallest firms in 2030. The change would protect benefits earned after each workplace's implementation date by placing the money with outside institutions before employees leave their jobs.
Contents
- Retirement savings overhaul targets unpaid benefits and weak returns
- Which workplaces would have to comply, and when?
- How the government would pursue missing contributions
- What smaller businesses would receive
- Why the government wants professional pension funds
- Three kinds of funds, with rules for trustees
- Higher returns would come with investment risk
- Investment choices and provider disclosures would change
- Regular pension payments could become the default
- Public fund management and wider coverage await decisions
- Key Points
The Ministry of Employment and Labor and the ruling Democratic Party discussed the Retirement Pension Function Enhancement Plan after consultations with labor and business groups. Their proposal addresses two problems: workers losing retirement payments when employers cannot pay, and pension savings producing relatively low investment returns.
Unpaid retirement benefits reached 822.9 billion won last year, accounting for 41.1% of all unpaid wages. Retirement pension assets, meanwhile, stood at 501.4 trillion won at the end of last year, yet only 26% of workplaces had adopted the pension system introduced in 2005.
The government also wants professional trustees to manage pooled retirement savings through new funds. Those arrangements would be available for defined contribution pensions and individual retirement pension accounts, commonly called IRPs. Workers could gain access to professionally managed portfolios, while investment gains and losses would remain theirs.
Labor Minister Kim Young-hoon described the plan as an agreement among the groups involved in shaping it:
the result of an agreement among labor, management and the government
The government and ruling party intend to prepare amendments to the Employee Retirement Benefit Security Act in November and seek passage in December. Parliamentary approval would turn the proposed timetable and operating rules into legal obligations. For employers, the central change is having to finance future retirement benefits regularly instead of finding the money when a worker leaves.
Which workplaces would have to comply, and when?
The proposed timetable gives smaller employers more time to prepare. External funding means transferring retirement money to a pension arrangement outside the business, where it is separated from the employer's operating cash.
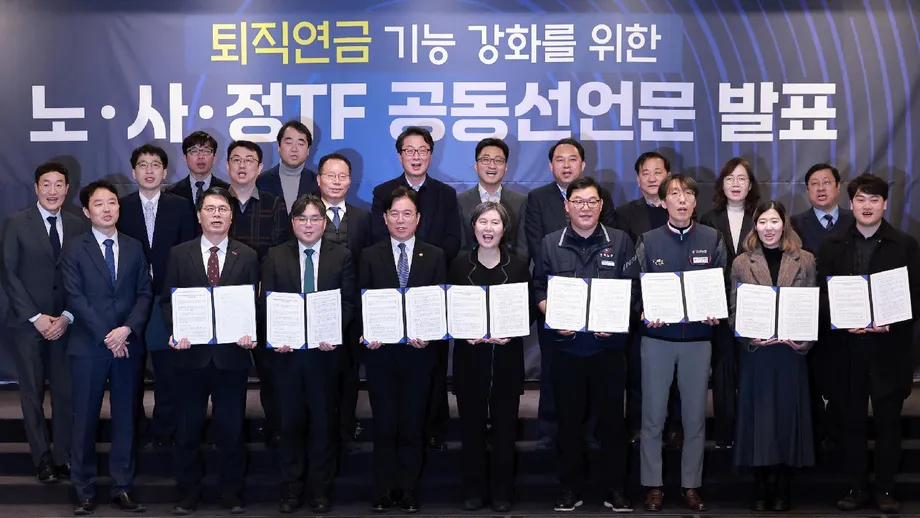
- February: Labor, management and government agreed on the direction of retirement pension reform in a joint declaration.
- November: The government plans to prepare legislation putting the measures into law.
- December: The labor minister aims to secure passage at a National Assembly plenary session.
- 2028: External funding would become compulsory for workplaces with 100 or more employees.
- 2029: Workplaces with 10 to 99 employees would join.
- 2030: The requirement would extend to workplaces with fewer than 10 employees.
The obligation would cover employment from the date the rule begins at each workplace. Employers would not have to move money into outside accounts under this mandate for service completed before that date. A worker's benefits could therefore include an earlier period handled under the existing arrangement and a later period covered by mandatory external funding.
Workplaces that fail to adopt a retirement pension after their deadline would be automatically enrolled in the Small and Medium-sized Enterprise Retirement Pension Fund. They would receive contribution notices, with administrative sanctions, including fines, for persistent refusal to pay.
How the government would pursue missing contributions
The ministry plans to expand inspections of employers that fail to make required external contributions. The aim is to identify missing money while a worker is still employed, rather than after retirement or a business failure.
Defined benefit pensions promise a benefit calculated under the plan's rules, leaving the employer responsible for maintaining adequate funding. Under the proposal, companies funded below 95% of the minimum required amount would have to cover at least 33% of the shortfall within a year. Failure could bring a fine of up to 10 million won.
Defined contribution pensions work differently: the employer pays money into an account, and the eventual balance depends on contributions and investment performance. Employers would face a new duty to provide wage information, helping authorities check whether the required payments have been made.
What smaller businesses would receive
Businesses with fewer than 30 employees would receive the lowest pension fees under the plan. The government also proposes replacing the existing pension adoption process, which involves regulatory filing and review, with a contract to reduce administrative work.
Employers adopting a pension before the law takes effect could receive support covering 10% of contributions for workers earning less than 130% of the minimum wage. The proposed budget for this early adoption support is 6 billion won next year.
Companies with fewer than 50 employees that newly adopt a pension could also qualify for support covering two percentage points of borrowing interest after one month. The government has allocated 6.2 billion won for that measure in next year's budget proposal, bringing the two proposed support budgets to 12.2 billion won.
The Korea Enterprises Federation, an employers' organization, supports the goal of protecting retirement benefits but wants implementation to reflect the financial and administrative capacity of small and micro businesses. For those employers, regular pension contributions would become a continuing cash requirement alongside wages and other expenses.
Why the government wants professional pension funds
Retirement pension assets are projected to exceed 1,000 trillion won by 2040, almost twice the 501.4 trillion won held at the end of last year. The government wants that expanding pool of savings to provide more retirement income through professional management and broader participation.
Retirement pensions returned 6.47% last year, compared with 18.82% for the National Pension, 17.2% for the government employees' pension and 18.9% for the private school teachers' pension. The gap between retirement pensions and the National Pension was 12.35 percentage points. Each system's investment mix and exposure to market risk affect its returns.
The government's stated ambition is to lift the retirement income replacement rate from about 13% into the 20% range. A replacement rate describes how much of a person's previous income a pension replaces. Achieving that goal would depend on contributions, investment results and the way workers receive their savings.
Under the proposed fund model, a professional trustee would pool and manage assets for participants. Workplaces could introduce it with employee representative consent and other required procedures. Existing contract arrangements and fund arrangements could operate at the same workplace, and employers could offer more than one fund.
Three kinds of funds, with rules for trustees
The proposal would create three routes into fund management. Banks, securities firms and insurers could establish commercial trustee companies, either alone or together, to serve multiple workplaces. Groups of employers or national labor and management organizations could establish nonprofit trustees. Public institutions could operate funds open to eligible workplaces.
The public route includes expanding Blue Seed, the pension fund operated by the Korea Workers' Compensation & Welfare Service. Access would widen to workplaces with up to 100 employees next year and up to 300 employees in 2028.
Financial institution trustees would need minimum capital of 12 billion won and seven essential staff members for functions including internal controls. Those directly managing investments would need another five to eight investment professionals. A preliminary licensing stage followed by final approval would allow authorities to assess applicants before they begin operating.
The proposed governance rules include at least four independent directors and at least two directors recommended by participants for financial institution trustees. Consortium funds would generally have equal representation from labor and management. Trustees would also have to reserve 0.25% of assets for operating risks and use outside organizations for asset custody and performance evaluation.
Participant interests would take priority under the law, with damages liability for trustees that breach their duties. To avoid liability, a trustee would have to demonstrate the absence of intent or negligence. The labor ministry and financial authorities would coordinate supervision, while the ministry would handle sanctions.
Higher returns would come with investment risk
The Korea Enterprises Federation has called for safeguards to accompany the expansion of professionally managed funds. Its concern is that workers bear the financial outcome when investments rise or fall.
The federation explained its position in a statement responding to the plan:
Unlike the national pension, whose payouts are guaranteed by the state, gains and losses from a fund-type retirement pension accrue entirely to the subscriber depending on investment performance,
For a worker in a defined contribution fund, professional management changes who makes investment decisions. The amount available at retirement still depends on what goes into the account and how those investments perform. Trustee qualifications, independent oversight and accountability therefore matter alongside the effort to improve returns.
Investment choices and provider disclosures would change
The government plans to gradually raise the current 70% ceiling on risky assets in IRPs. It would also expand eligible investments for IRPs and defined contribution pensions to include investment management accounts and issued notes, giving participants more choices for their savings.
The default option notification would move from four weeks after an investment product matures to two weeks before maturity. Default options provide a predetermined investment route when a participant makes no active choice. Earlier notification is intended to reduce the time money spends waiting in cash or similar holdings after a product ends.
The plan also calls for removing products with low returns from default options. Pension provider assessments would focus more on numerical returns and measures that account for the amount of investment risk taken to produce them.
Rankings and performance information for all providers would be disclosed, replacing the practice of publishing only the top 10%. Workers and employers would have a broader view of provider performance when choosing where to place retirement savings.
Regular pension payments could become the default
The government is considering making retirement benefits payable as a pension unless the recipient specifically requests a lump sum. That would shift the starting choice toward regular income while preserving the option to take the money at once.
Most retirees currently receive their benefits as a lump sum, a pattern the government wants to change as it seeks a larger role for employment pensions alongside the National Pension. Regular payments spread retirement savings across time, while a lump sum places the full balance under the recipient's immediate control.
Rules allowing early withdrawals would remain unchanged. Workers could continue using eligible withdrawals for needs such as buying a home or securing a jeonse deposit, the large refundable housing deposit used in many South Korean rental contracts.
The government would instead pursue legislation raising the ceiling on loans secured against pension assets from 50% to 70%. Borrowing against savings would offer an alternative to withdrawing them, although workers would take on repayment and interest costs. Authorities are also considering tax support to encourage people to keep saving for retirement over longer periods.
Public fund management and wider coverage await decisions
The National Pension Service's possible participation in managing the new funds remains unresolved and will be discussed in the National Assembly. Labor, business, government and specialists have disagreed over its role, leaving that issue outside the settled parts of the proposal.
The Korea Enterprises Federation argues that adding the National Pension Service to a market already served by private providers and Blue Seed could blur the roles of public and private pensions and weaken fair competition. The government's plan also leaves out the establishment of a separate retirement pension corporation.
Workers employed for less than one year and those working fewer than 15 hours a week are another unfinished part of the reform discussion. The ministry and the Korea Labor Institute are studying their retirement benefit arrangements and possible mandatory coverage. The Economic, Social and Labor Council began discussions on related issues in June.
For workers already covered by retirement benefit rules, the immediate legislative priorities are the external funding timetable, stronger contribution enforcement and the new trustee system. For employers, the proposed preparation period and financial support would shape how quickly they need to change payroll, pension contracts and cash planning.
Key Points
- Mandatory external funding would begin in 2028 for workplaces with at least 100 employees and reach all workplace sizes by 2030.
- The obligation would apply to service after each workplace's implementation date, without retroactive funding of earlier service.
- Unpaid retirement benefits totaled 822.9 billion won last year, or 41.1% of all unpaid wages.
- Professional trustees would manage new funds for defined contribution pensions and IRPs, with investment gains and losses belonging to participants.
- Proposed support for early adoption and borrowing interest totals 12.2 billion won in next year's budget.
- The government aims to prepare legislation in November and secure passage in December.
- National Pension Service participation and coverage for workers with short service or very short hours await further decisions.