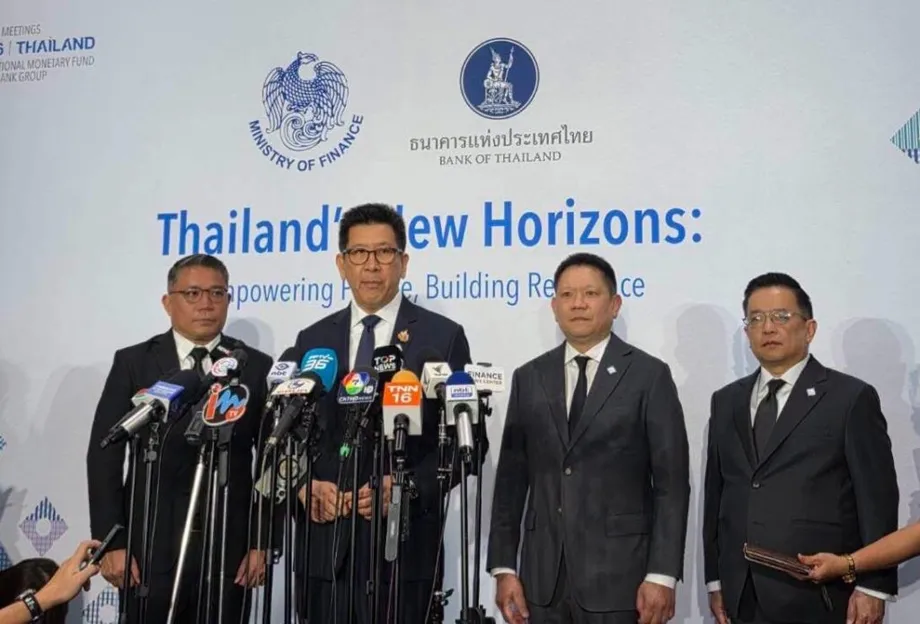
A global fraud plan with a launch date in Bangkok
Thailand plans to launch the Bangkok Blueprint on 14 October 2026 at the International Monetary Fund and World Bank Group Annual Meetings, proposing a shared response to digital fraud that costs the world an estimated $1 trillion a year. The Bank of Thailand is developing the document with both institutions as a practical guide for governments, regulators and financial firms, rather than a new set of binding international rules.
Contents
- A global fraud plan with a launch date in Bangkok
- What the blueprint would ask countries to do
- The scale of losses needs careful interpretation
- Why an authorized payment can still be a scam
- Thailand's domestic rules put providers under scrutiny
- Cash, gold and reported progress against fraud
- Regional action shows why banks cannot work alone
- Financial safety sits within a wider Thai agenda
- The timetable and decisions still to come
- Key Points
The stakes are substantial at home. Thailand recorded $1.76 billion in fraud losses in 2024, according to Bank of Thailand Assistant Governor Chayawadee Chai-anant and economist Pithiwat Pruksachat. Their World Economic Forum article describes a blueprint containing 12 policy considerations and five core areas of action, including legal frameworks, fraud safeguards, cooperation and consumer protection.
Bank of Thailand Governor Vitai Ratanakorn wants the initiative to address a problem extending beyond Southeast Asia to the United States and Latin America. He has also cautioned that producing an international document does not mean Thailand has completed its own work. The country must apply the principles and continue improving its response.
Speaking about the initiative, Vitai explained its intended role:
Our ambition is for the Bangkok Blueprint to become a practical reference for countries seeking to strengthen their response to digital fraud.
The annual meetings are scheduled for 12 to 18 October in Bangkok, with more than 15,000 delegates from 191 countries expected. Thailand is hosting for the second time, using the gathering to connect financial safety with its wider economic agenda.
What the blueprint would ask countries to do
The blueprint is intended to cover the full course of a fraud incident: preventing it, detecting suspicious activity, limiting damage, responding to victims and tracing or recovering stolen funds. Its scope also includes financial product design, laws and coordination between agencies, recognizing that vulnerabilities can arise before a payment reaches a bank.
The five essentials described by the Bank of Thailand authors are:
- A clear national strategy and legal framework.
- Safeguards to prevent, detect and recover from fraud.
- Better use of cybersecurity and tools against money laundering.
- Stronger cooperation between sectors and across borders.
- Consumer protection, awareness and redress.
Countries would adapt these principles to their own legal systems, financial services and digital development. That flexibility matters because a country expanding access to basic mobile payments may face different operational problems from one with extensive instant payment networks and international transfers.
Vitai has described the wider initiative through three priorities: reducing digital fraud, strengthening cybersecurity and improving the readiness of the digital financial ecosystem. Member countries are expected to contribute ideas and policy experience, making the blueprint a vehicle for shared learning rather than simply an export of Thai regulation.
The document also follows the 2018 Bali Fintech Agenda, launched by the IMF and World Bank to help countries adopt financial technology while managing risks. The Bangkok initiative addresses a more specific challenge: protecting people who already use digital finance from criminals exploiting those services.
The scale of losses needs careful interpretation
Vitai has cited estimated economic damage from cyber related fraud and threats of approximately $1.03 trillion, with more than two thirds occurring in Asia. The Bank of Thailand authors use a rounded global estimate of $1 trillion annually and say around 50% to 70% of adults worldwide have faced a scam attempt.
These figures describe different things. Exposure to an attempted scam is not the same as losing money, while a broad estimate covering cyber threats should not be treated as identical to a narrowly defined payment fraud total. The estimates establish the scale of concern, but they do not provide a single comparable measure of every country's losses.
A regional assessment offers another important distinction. In its digital scam assessment, published on 12 October 2026, the ASEAN+3 Macroeconomic Research Office says evidence of effects on financial stability across the entire system remains limited.
That finding does not dismiss the damage to households and businesses. It separates documented losses and threats to confidence from a stronger claim that scams are already destabilizing the financial system. Authors Benyaporn Chantana, Ivan Lim and Prashant Pande nevertheless argue that the scale and persistence of scams require coordinated action across sectors and jurisdictions.
The distinction is useful when assessing Vitai's description of fraud as a structural global risk. Scams can divert savings, burden financial providers and discourage people from using digital services without necessarily producing an immediate banking crisis.
Why an authorized payment can still be a scam
One of the most difficult problems is fraud in which victims approve the payment themselves. A criminal may build trust through an investment group, impersonate a relative or persuade someone that an urgent transfer is necessary. The bank receives a payment instruction from its genuine customer, even though deception caused that instruction.
The ASEAN+3 Macroeconomic Research Office identifies these authorized payment scams as particularly difficult because manipulation often happens before financial institutions become involved. Important parts of the criminal process can therefore sit outside the direct authority of financial regulators.
The Bank of Thailand authors illustrate the problem through Ploy, explicitly described as a composite of real scam experiences rather than an individually identified victim. A digitally capable Bangkok café owner is drawn into an investment group, encouraged by apparent trading gains, and persuaded to commit savings and borrowed money. When she seeks a withdrawal, she encounters a frozen account and a fake tax demand.
The example explains why identity checks alone are insufficient. Verifying who is making a transfer does not establish whether that person has been deceived. Responses must connect unusual transaction detection with action by banks, telecommunications operators, digital platforms and law enforcement.
It also shows how fraud can undermine financial inclusion. Losing money is the immediate harm, but fear, stress and lost confidence can push victims away from banking applications and other services intended to make finance easier to access.
Thailand's domestic rules put providers under scrutiny
Thailand's preparations extend beyond the international blueprint. Draft Bank of Thailand guidelines opened for public comment until 18 March 2025 proposed fraud management policies covering prevention, monitoring, response, resolution and support for affected customers. Implementation was tentatively planned for 1 April 2025, alongside measures addressing mule accounts and customer checks.
A mule account is a bank or electronic money account used to receive and move proceeds of crime. The draft called for providers to assess the risk of such accounts, monitor customer transactions continuously and update risk classifications. Authentication requirements would reflect the risk of the transaction, the product and the service channel.
Directors and senior executives would be responsible for fraud policies and measurable performance targets. Commercial banks, special financial institutions and providers of transferable electronic money were expected to meet every requirement. Other providers could apply the guidelines according to their services.
Customer response measures included support channels operating 24 hours a day, specified response timeframes, and reporting to the central bank when incidents caused widespread customer damage or affected a provider's reputation. Information sharing with other providers, the Anti-Money Laundering Office and the Royal Thai Police was also part of the draft.
The later account by the Bank of Thailand authors describes a responsibility framework effective since April 2025. Financial institutions and other providers that fail prescribed fraud prevention standards must share responsibility for resulting losses. According to the authors, providers must demonstrate that required safeguards were in place, rather than leaving customers to prove a failure.
That description should not be read as a promise that every scam victim automatically receives reimbursement. Responsibility depends on the applicable standards and whether a provider met them. The earlier draft timetable and the later account of an effective framework also concern related measures, not necessarily an identical final regulatory text.
Cash, gold and reported progress against fraud
A separate sector framework was announced for launch on 10 September, bringing together the central bank, commercial and state banks, payment providers, lenders outside the banking sector and more than 2,000 money changers. Participants were to commit not to support illicit financial activity or corruption.
Concrete measures included additional due diligence for cash deposits exceeding 5 million baht and tighter restrictions on cash purchases of gold bullion worth at least 10 million baht. These controls target channels through which illicit proceeds can move beyond ordinary digital payment accounts.
Vitai cited a 52% decline in large cash withdrawals and a 70% decline in large gold withdrawals over the preceding 12 months. Those changes were presented as signs of reduced money laundering activity, although withdrawal volumes alone do not measure the full amount of criminal proceeds.
A more direct fraud indicator was reported for payments authorized by victims: losses fell to 1.8 billion baht in the second quarter of 2026, down 80% from the same quarter in 2024. The stated reduction implies a comparison figure of about 9 billion baht in the second quarter of 2024, or a decline of roughly 7.2 billion baht.
That quarterly payment fraud measure cannot be directly compared with Thailand's $1.76 billion annual fraud loss estimate for 2024. The periods, currencies and categories differ. It supports a narrower conclusion: reported losses in this payment fraud category fell sharply, while the broader fraud problem still requires attention.
Regional action shows why banks cannot work alone
The Philippines offers a parallel example of the coordination the blueprint seeks. ASEAN Foundation Executive Director Piti Srisangnam has said scam centers have spread into the Philippines, Myanmar and Timor-Leste from earlier concentrations around Cambodia, Thailand and Vietnam.
Citing a Global Anti-Scam Alliance study, he said nearly 80% of Filipinos are contacted by scammers. That exposure figure is higher than the 50% to 70% worldwide range cited by the Bank of Thailand authors, but different populations and survey methods mean the figures should not be treated as a precise country ranking.
The Scam Ready ASEAN Program aims to reach 3 million people through a planned network of 2,000 master trainers. At the time described, it had 105 trainers, equivalent to 5.25% of that target. The Philippine program aims to reach about 1 million beneficiaries, one third of the regional goal, through partners including the Bank Marketing Association of the Philippines, Google and the Philippine central bank.
Bernadette Romulo-Puyat, deputy governor of the Bangko Sentral ng Pilipinas, explained the need to go beyond education:
Fighting scams requires more than awareness. It requires action and collaboration.
The Philippine central bank also signed an information sharing agreement with the Philippine National Police for cases under the Anti-Financial Account Scamming Act. Police became the fifth government agency with such an agreement, following arrangements with investigative, justice and securities authorities.
These initiatives address different parts of the same problem: helping people recognize manipulation, strengthening fraud controls inside financial institutions and giving investigators access to information needed to follow criminal activity.
Financial safety sits within a wider Thai agenda
Vitai connects digital fraud prevention to four domestic priorities: household debt, access to credit for small and medium enterprises, financial services at fair cost, and illicit money linked to fraud, scams or corruption. The relationships are practical. A scam can consume household savings or borrowed funds, while criminal money moves through services also used by legitimate businesses.
The Bank of Thailand authors identify two further threats to trust. Dependence on a small group of technology providers can allow a single outage to disrupt many institutions, as demonstrated by the 2024 CrowdStrike incident. Digital platforms can also restrict users' choices, while biased data used in artificial intelligence decisions can exclude people with limited financial histories.
These issues are distinct from criminal fraud, but they help explain the meetings' theme, "Safe and Inclusive Digital Finance for Financial Wellbeing." Access matters less if services are unreliable, unfair or unsafe.
Thailand's meeting agenda also covers digital and artificial intelligence transformation, resilience amid global fragmentation, finance for climate adaptation, and demographic change and the longevity economy. Vitai has cited average annual economic growth of 2.4% since the pandemic, compared with 5.3% after the 1997 Asian financial crisis. The difference is 2.9 percentage points, although the comparison concerns separate economic periods and does not establish fraud as the cause of slower growth.
The timetable and decisions still to come
The main dates connect Thailand's domestic preparations with the international launch:
- 18 March 2025: Public comment closed on draft digital fraud management guidelines.
- April 2025: The provider responsibility framework took effect, according to the Bank of Thailand authors.
- 10 September: Announced launch date for the separate sector pledge and cash and gold controls.
- 12 October 2026: The annual meetings begin and the ASEAN+3 Macroeconomic Research Office publishes its scam assessment.
- 13 October 2026: Thailand's Ministry of Finance flagship event on resilience is scheduled.
- 14 October 2026: The Bangkok Blueprint is scheduled to launch.
- 18 October 2026: The annual meetings are scheduled to conclude.
The Ministry of Finance event is set to include IMF Managing Director Kristalina Georgieva, World Bank Group President Ajay Banga and Finnish Deputy Prime Minister and Finance Minister Riikka Purra. Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas has placed fraud prevention alongside investment, technology and opportunities for Thai businesses.
The central unresolved issue is implementation. The blueprint's five essentials are described publicly, but how individual countries will translate all 12 considerations into laws, supervision, recovery procedures and responsibility for losses is not yet settled. Its status as a practical guide means publication will not itself create enforceable duties worldwide.
Thailand's own message is that the launch should begin further work, not certify success. The meaningful tests will be whether institutions share information quickly, prevent suspicious transfers, support affected customers and recover funds while keeping legitimate financial services accessible.
Key Points
- The Bangkok Blueprint is scheduled to launch on 14 October 2026 at the IMF and World Bank Group Annual Meetings.
- It contains 12 policy considerations and five core areas for combating digital fraud, without creating binding international rules.
- Thailand recorded $1.76 billion in fraud losses in 2024, according to Bank of Thailand authors.
- Reported losses from payments authorized by scam victims fell to 1.8 billion baht in the second quarter of 2026, down 80% from two years earlier.
- Thailand's provider responsibility framework has operated since April 2025, with liability linked to failures to meet prescribed safeguards.
- The ASEAN+3 Macroeconomic Research Office calls for coordinated action while noting limited evidence of effects on financial stability across the entire system.