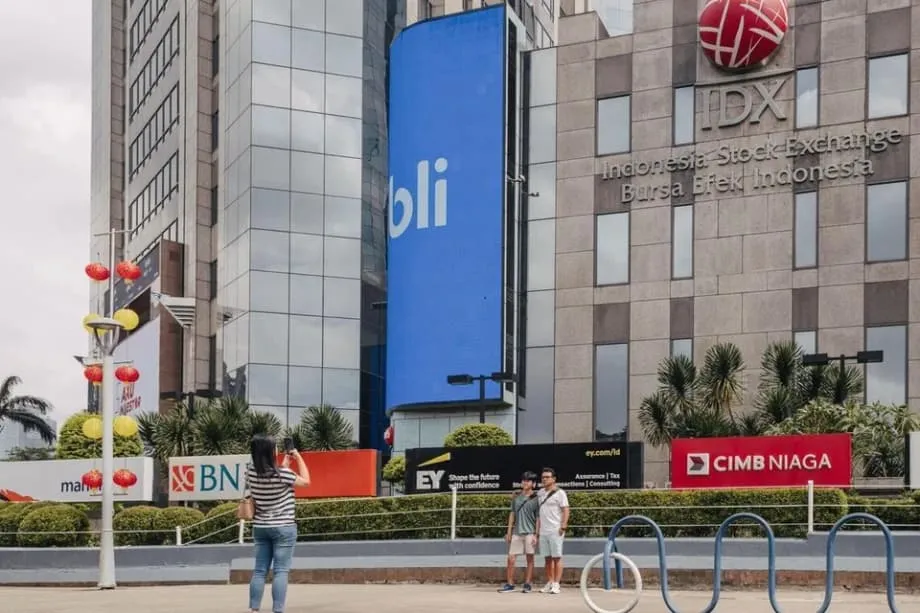
A 7.35 Percent Fall Brings Years of Investor Losses Into Focus
Indonesia's Jakarta Composite Index fell 7.35 percent to 8,320.56 on January 28, 2026, after global index provider Morgan Stanley Capital International, known as MSCI, froze its review of the country's market status and warned of a possible downgrade from Emerging Market to Frontier Market. The fall pushed the index below critical support levels, price points traders watch for signs that a decline might stop, and erased billions of dollars in market value.
Contents
- A 7.35 Percent Fall Brings Years of Investor Losses Into Focus
- Ordinary Savings Caught in the Rally
- How Stock Frying Turns Buying Into Losses
- Research Finds Risks Beyond Small Companies
- Warnings and Price Surges Before the Crash
- Why MSCI's Warning Carries Such Weight
- Existing Powers and the Enforcement Gap
- What Enforcement Elsewhere Shows
- Reforms Target Ownership, Share Supply and Social Media
- Key Points
MSCI cited poor visibility over share ownership and persistent weak enforcement against market manipulation. Its warning turned a longstanding problem for individual investors into a threat to Indonesia's position in global investment portfolios. Within days, Financial Services Authority chairman Mahendra Siregar, his deputy Mirza Adityaswara, and Indonesia Stock Exchange chief Iman Rachman submitted their resignations.
For Bambang, a 39-year-old employee at a digital advertising firm in Jakarta, the damage began much earlier. About five years before the latest crisis, the father of two bought shares in Bank MNC, a Jakarta lender, hoping to improve his family's finances. Social media chatter suggested that ByteDance, the Chinese technology company behind TikTok, would back the bank through a major rights issue.
Bambang bought near the peak of a rally and lost more than half the value of his investment within days. The rights issue went ahead, but ByteDance did not participate. His experience illustrates the human cost of what Indonesians call "goreng saham", or stock frying: schemes that push share prices up before those driving the rally sell, leaving later buyers facing a collapse.
Ordinary Savings Caught in the Rally
Rivki Maulana, a 37-year-old bank employee, lost at least 100 million rupiah, approximately $7,500, after trusting companies that promised fast, large gains without the need for fundamental analysis. Fundamental analysis means examining a company's business and financial condition to judge whether its share price makes sense.
Muhammad Avisena, a trader working full time in Pekalongan, Central Java, also suffered losses. He observed that manipulation reaches beyond small companies with low market capitalization, the total value of a company's shares. Some targets are large companies, including members of the LQ-45 index, which groups highly capitalized and liquid shares. Liquidity describes how readily shares can be bought or sold.
Indonesia has more than nine million registered retail stock investors, meaning individuals who invest their own money. Millions have fallen victim to stock frying practices that have troubled the exchange for decades. The Financial Services Authority, known as OJK, has put public losses from various financial scams at 7 trillion rupiah, approximately $460 million. That figure covers a wider range of scams than stock manipulation alone.
Bambang's purchase shows how a convincing corporate story can draw household savings into a speculative rally. The prospect of backing from a recognizable technology company gave buyers a reason to expect further gains. Coordinated buying then made the rumor appear to have support in the market, encouraging people to purchase shares at increasingly expensive prices.
How Stock Frying Turns Buying Into Losses
Bank MNC's rally followed a familiar sequence. The ByteDance story spread through stock trading forums and social media. Groups bought aggressively, creating the appearance of strong demand and pushing prices higher. Once investors such as Bambang entered, the original buyers sold their holdings at inflated prices. The subsequent collapse left later buyers carrying the losses.
A rights issue allows a company to raise money by offering additional shares to existing shareholders. In this case, the fundraising proceeded, while the anticipated participation by ByteDance never happened. The combination of a real corporate transaction and an unfulfilled investment rumor helped make the story persuasive.
Academic research on the Indonesia Stock Exchange describes a technical pattern called a "buy-buy and sell-sell" strategy across four consecutive trading days. During the first two days, manipulators buy large quantities at the highest bid prices, the prices buyers offer. This creates artificial liquidity and attracts attention as the share price rises.
During the third and fourth days, the manipulators sell their entire positions, often at the lowest ask prices, the prices sellers request. They capture cumulative abnormal returns, meaning gains beyond the return used as a comparison in the research. Investors arriving late can be left with shares that have become worthless.
The process depends on timing. The people creating the apparent demand buy before the wider crowd and sell after that crowd pushes the price higher. Retail investors following a rumor or a sudden price rise can therefore enter just as the people behind the rally are preparing to leave.
Research Finds Risks Beyond Small Companies
A study of 149 companies listed in late 2015 found a higher probability of manipulation among stocks with large market capitalization, 0.48, than among stocks with small market capitalization, 0.25. The result challenges the familiar assumption that manipulation mainly affects penny stocks or very small companies.
Indonesia's relatively large companies can still be small enough for actors with substantial financial resources to influence through coordinated trading. Avisena's observation about companies in the LQ-45 index fits that concern: a company can have a prominent market position and still attract manipulation.
Research examining trading periods in late 2015 found evidence of pump-and-dump activity in 14 of 16 observed cycles lasting four days. It identified 73 specific instances involving a stock on a particular trading day. Within the periods examined, manipulation appeared repeatedly rather than as an occasional disruption.
The exchange itself identified 41 stocks suspected of pump-and-dump practices in 2020. Those stocks accounted for 8.3 percent of its average daily transaction value. The figure connects suspected manipulation to a substantial share of trading activity, showing why the problem matters to the functioning of the wider market.
Warnings and Price Surges Before the Crash
President Joko Widodo called for action in 2020, citing stock manipulation that had led to fraud and criminal activity. He urged capital market stakeholders to:
clean up
The Asuransi Jiwasraya scandal exposed the damage that risky stock investments could cause beyond individual trading accounts. The troubled insurer, owned by the state, suffered massive losses after investing in stocks of poor quality that were widely believed to have been subject to pump-and-dump schemes. Consistent enforcement remained elusive despite the prominence of the case.
Several later price surges brought renewed attention to concentrated share ownership. Barito Renewables Energy rose more than 1,000 percent within months during 2024. In April 2025, plastic pipe manufacturer Multi Makmur Lemindo gained 130 percent within a month. Around the same period, real estate company Diamond Citra Propertindo recorded a 2,900 percent increase.
Individuals or groups accumulated large portions of the available share supply in these cases, allowing them to dictate prices artificially, while investigations remained conspicuously absent. When a small group controls much of the stock available for trading, other buyers have fewer shares to compete for, giving that group greater influence over the price.
The sequence leading to the January crisis stretched across years:
- Late 2015: Research examined 149 listed companies and detected manipulation in 14 of 16 observed trading cycles lasting four days.
- 2020: The exchange identified 41 stocks suspected of pump-and-dump activity, and President Joko Widodo demanded action against manipulation.
- 2024: Barito Renewables Energy's value rose more than 1,000 percent within months.
- April 2025: Multi Makmur Lemindo gained 130 percent within a month, while Diamond Citra Propertindo rose 2,900 percent around the same period.
- January 28, 2026: The Jakarta Composite Index fell 7.35 percent to 8,320.56 after MSCI's warning.
- Within days of the fall: Senior OJK officials and the exchange chief submitted their resignations.
Why MSCI's Warning Carries Such Weight
MSCI indices serve as benchmarks for trillions of dollars in global investment funds. A benchmark gives funds a market reference to follow or measure themselves against. Moving Indonesia from Emerging Market to Frontier Market status would make its equities ineligible for many institutional portfolios.
A downgrade could therefore trigger substantial capital outflows as affected funds withdraw money from Indonesian shares. It could also cause lasting damage to companies' ability to raise financing through the stock market for projects and expansion over many years. The threat reaches beyond the immediate losses recorded on January 28.
MSCI's concerns centered on opacity over shareholdings and weak enforcement. Investors need to understand who owns a company's shares and how much stock is genuinely available for trading. Hidden concentrations of ownership make it harder to assess whether market prices reflect broad demand or the actions of a small, coordinated group.
Indonesia's currency added to the pressure. The rupiah had already fallen to historic lows against the US dollar amid concerns over fiscal imprudence and aggressive state intervention under President Prabowo Subianto. Currency weakness and doubts about market integrity combined to strain investor confidence.
The resignations of Mahendra Siregar, Mirza Adityaswara and Iman Rachman acknowledged a regulatory framework that had failed to keep pace with mounting structural risks. As of February 9, 2026, the threatened MSCI downgrade remained a warning, while reform promises were being developed in response to the crisis.
Existing Powers and the Enforcement Gap
The 1995 Capital Market Law gives OJK independent authority to investigate stock market crimes without relying on police intervention. Market participants nevertheless widely describe the regulator as appearing to turn a blind eye to suspicious activity. Enforcement actions remain rare despite the authority's investigative powers.
OJK also has disgorgement instruments. Disgorgement means requiring wrongdoers to return money gained illegally. Those proceeds can be directed into compensation funds for victims, connecting punishment with the recovery of investor losses.
Giovanni Mofsol Muhammad, a senior partner at the Dentons HPRP law firm, stresses that existing legal frameworks already provide powerful tools for restitution. His assessment places the central problem in the consistent use of those tools, rather than the creation of an entirely new legal mechanism.
The Indonesian National Police has recently secured convictions against former exchange officials and corporate directors for capital market crimes, with prison sentences and fines totaling multiple billions of rupiah. Observers describe such outcomes as exceptions rather than a consistent deterrent. Police investigators are also working alongside regulators to identify specific actors who exploited the recent market volatility.
What Enforcement Elsewhere Shows
South Korea provides a technological comparison. The Korea Exchange uses surveillance powered by artificial intelligence to examine online posts, YouTube videos and spam text messages for signs of pump-and-dump activity. Its system compares that content with recent share price movements and automatically generates reports for regulatory investigation.
South Korea's Financial Supervisory Service is expanding its capabilities with powerful servers equipped with advanced central processing units and graphics processing units, known as CPUs and GPUs. The equipment supports monitoring of cryptocurrency trades made at high frequency. Together, these efforts connect digital promotion with trading behavior.
In the United States, the Department of Justice recently secured $214 million in forfeited proceeds from a pump-and-dump scheme involving Chinese Liberation Education Holdings. It is preparing to distribute the money directly to investor victims through formal remission processes, procedures for returning forfeited funds to people who suffered losses.
The US Securities and Exchange Commission has established a Cross-Border Task Force targeting companies based abroad that engage in ramp-and-dump activity, particularly companies with China links. Such activity involves pushing share prices upward and then selling into the rise.
Penalties in other jurisdictions show the scale of financial and criminal consequences available. In the Philippines, the Villar family faced fines equivalent to 3.4 trillion rupiah for stock manipulation. Chinese investment expert Xu Xiang received 5.5 years in prison and fines of 26 trillion rupiah for manipulating 13 listed companies. French courts have ordered asset seizures exceeding 8 billion rupiah for market manipulation convictions.
Bernard Madoff received a prison sentence of 150 years for his Ponzi scheme, a fraud in which money from later investors pays earlier investors. His case offers a further example of severe punishment for investment fraud, alongside the stock manipulation penalties elsewhere.
Reforms Target Ownership, Share Supply and Social Media
Luhut Pandjaitan, chairman of the National Economic Council, has pledged to accelerate changes to make Indonesia's capital market more transparent. One proposal is the demutualisation of the Indonesia Stock Exchange, which would change an ownership structure in which the exchange belongs to the brokerages it regulates.
The current arrangement creates a conflict of interest and hesitation over punishing members that break rules. Changing that relationship is intended to give the exchange greater distance from the firms whose conduct it supervises.
A proposed increase in the minimum free float from 7.5 percent to 15 percent would double the required share of stock available to public investors. A larger public supply would make it harder for a small group to corner a stock, meaning gain enough control over available shares to dictate its price.
Legal counsel Erwin Kurnia Winenda has highlighted the importance of that increase. Companies could expand public ownership through rights issues or private placements to legitimate investors. A private placement involves selling shares to selected investors rather than offering them broadly.
The exchange plans to introduce surveillance systems powered by artificial intelligence, modeled on South Korean approaches, to monitor unusual transactions and detect manipulation patterns automatically. OJK also intends to tighten supervision of financial influencers on social media, where modern schemes increasingly begin rather than on traditional trading floors.
The Indonesia National Agency for Consumer Protection has called for criminal prosecution of manipulators, describing pump-and-dump practices as white-collar crimes that weaken public trust and damage the market's role in supplying financing over many years. No implementation dates for the proposed reforms were given.
For Bambang and other investors whose savings disappeared after persuasive rumors and abrupt reversals, reform has two practical goals: reducing the opportunity to manipulate prices and using existing powers to recover illegal gains for victims. The January collapse has made those longstanding demands urgent for both ordinary households and the institutions responsible for Indonesia's market.
Key Points
- The Jakarta Composite Index fell 7.35 percent to 8,320.56 on January 28, 2026, after MSCI warned of a possible downgrade to Frontier Market status.
- OJK chairman Mahendra Siregar, deputy Mirza Adityaswara and exchange chief Iman Rachman submitted their resignations within days.
- OJK put public losses from various financial scams at 7 trillion rupiah, approximately $460 million, in a country with more than nine million registered retail stock investors.
- Research on 149 companies found manipulation probabilities of 0.48 for stocks with large market capitalization and 0.25 for smaller stocks.
- The exchange identified 41 stocks suspected of pump-and-dump activity in 2020, accounting for 8.3 percent of average daily transaction value.
- Proposed reforms include changing exchange ownership, doubling the minimum free float from 7.5 percent to 15 percent, introducing surveillance powered by artificial intelligence and tightening oversight of financial influencers.
- OJK already has powers to investigate market crimes and recover illegal gains for victim compensation, but consistent enforcement remains a central concern.