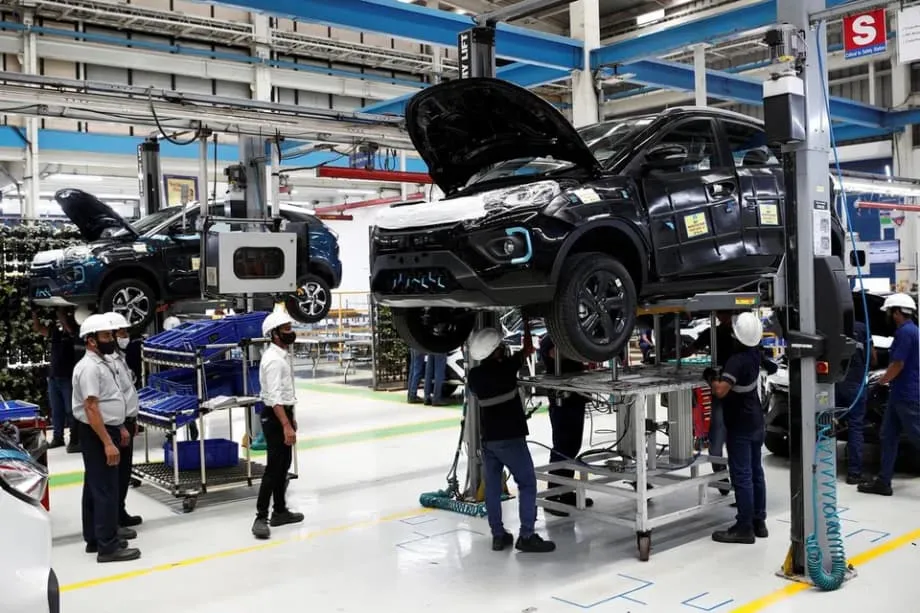
Reliance Faces a Battery Technology Bottleneck
Reliance Industries has paused plans to manufacture lithium-ion battery cells in India after negotiations with China's Xiamen Hithium Energy Storage Technology Co. stalled over tighter restrictions on technology transfers. The setback, described as of January 23, 2026, puts access to Chinese manufacturing expertise at the centre of India's effort to build its own clean energy supply chains.
Contents
- Reliance Faces a Battery Technology Bottleneck
- Reliance Says Its Broader Plans Remain Intact
- Why Alternative Technology Costs More
- Manufacturing Subsidies Meet Practical Delays
- What China's Battery Controls Cover
- Engineers Become Part of the Supply Chain Problem
- Rare Earth Restrictions Add Another Pressure Point
- The Dates Behind the Manufacturing Squeeze
- India Considers More Flexible Investment Rules
- Domestic Battery Efforts Offer Other Routes
- The Bottom Line
Mukesh Ambani, Reliance's chairman and Asia's richest person, had already adjusted his massive oil refinery operations to meet demands from Washington to stop purchasing Russian petroleum. His clean energy expansion now faces pressure from Beijing, whose control over battery technology and rare earth processing gives it considerable influence over how quickly Indian manufacturers can expand.
Reliance had aimed to begin cell manufacturing this year and was in advanced negotiations to license lithium iron phosphate technology, known as LFP, from Xiamen Hithium. LFP is valued for its relatively low cost and stability in energy storage applications. The Chinese supplier withdrew as Beijing tightened controls on overseas technology transfers in strategic sectors.
Reliance is now concentrating its immediate efforts on assembling battery energy storage systems, or BESS. These containerised units are intended mainly for the company's own renewable power projects rather than wider commercial sales. Storage allows electricity generated by renewable energy projects to be held for later use.
The obstacle reaches beyond one company. India's Production-Linked Incentive scheme, or PLI, encourages domestic manufacturing through financial support, but money alone cannot supply production methods, machinery or experienced technical staff. China's strength across those parts of the supply chain gives it what amounts to a veto over the pace of some Indian green energy projects.
Reliance Says Its Broader Plans Remain Intact
Reliance's shift towards storage system assembly comes alongside its public insistence that its wider manufacturing programme remains on schedule. A company spokesperson said BESS manufacturing, battery pack manufacturing and cell manufacturing all remain part of its energy storage plans.
The spokesperson, responding on behalf of Reliance, said the company had made no change to its planned battery manufacturing ecosystem:
We would like to categorically affirm that there has been no change in our plans for creating a world leading battery storage manufacturing ecosystem from cell to containerised ESS and they are progressing well in line with our target timelines.
Reliance's statement presents a broader commitment than its immediate focus on assembly. A battery cell is the basic unit that stores energy. Battery pack manufacturing combines cells into larger units, while a containerised storage system brings batteries together in equipment that can serve an energy project. Building the final system and manufacturing its cells are different stages of the same supply chain.
The withdrawal of Xiamen Hithium leaves Reliance facing execution risks and higher costs as it seeks proven technology for the cell manufacturing stage. Its public position remains that the complete programme, from cells to containers, is progressing against its target timelines.
Why Alternative Technology Costs More
Reliance's internal assessments concluded that proceeding without established Chinese cell technology would sharply increase costs. The company evaluated alternatives from Japan, Europe and South Korea, but found them substantially more expensive for deployment at large scale in India's price sensitive market.
Indian manufacturers must therefore solve two problems together: securing a technology they can use and keeping the resulting batteries affordable. A production method that is accessible but too expensive can weaken the business case for a factory, especially when cheaper imported batteries are already available.
Adani Group and JSW Group face similar choices. Both have outlined aggressive clean energy expansion plans, yet are currently prioritising battery pack and container assembly over full scale cell manufacturing. They are looking for technologies that can be expanded economically, a search made harder by China's export restrictions.
Cheaper Chinese batteries entering the Indian market add pressure to domestic producers. Companies that cannot license economical Chinese technology or obtain subsidised inputs struggle to compete with imported finished products. The result is a difficult transition: assembling batteries locally can move projects forward, while the more demanding task of making cells remains dependent on access to technology and competitive costs.
Manufacturing Subsidies Meet Practical Delays
India's PLI scheme for advanced chemistry cell manufacturing was designed to encourage domestic production through subsidies tied to project milestones. Reliance New Energy was among the successful bidders in 2022. The account of its manufacturing difficulties also says the company was penalised earlier this year for missing deadlines.
Milestone based support connects government payments to progress on a project. For manufacturers, that means obtaining technology and equipment is part of meeting the conditions for financial assistance, rather than a separate issue that can be dealt with later.
Reliance's missed deadlines illustrate the gap between India's manufacturing ambitions and the practical requirements of building a cell factory. Other beneficiaries of the programme have also faced delays connected with technology access and equipment sourcing.
Government incentives can help support investment, but companies still need production expertise, machinery and inputs that allow them to compete. Restrictions on those supplies make the subsidy programme harder to deliver, particularly when imported batteries offer a cheaper alternative to domestic manufacturing.
What China's Battery Controls Cover
China's Ministry of Commerce and General Administration of Customs announced export controls in October 2025 covering a range of lithium-ion battery components and the technologies used to manufacture them. The restrictions extend across materials, production knowledge and specialised equipment.
The controlled categories include cathode material compositions such as lithium iron phosphate, nickel, cobalt and manganese hydroxides, alongside graphite anode materials and related production technologies. Cathodes and anodes are the two sides of a battery cell involved in storing and releasing electrical energy. Restricting their materials and production methods affects the ability to establish manufacturing facilities.
For lithium-ion cells or packs, the controls require a licence when weight energy density is greater than or equal to 300 watt-hours per kilogram, written as 300 Wh/kg. Energy density describes how much energy a battery stores for its weight. A higher number means more stored energy for each kilogram.
Most mainstream electric vehicle and consumer electronics batteries operate in the 100-280 Wh/kg range. Their energy density is below the stated 300 Wh/kg threshold. Indian companies planning factories with Chinese partners nevertheless face restrictions on the production technologies they need to build those facilities.
The controls took effect on November 8, 2025. Chinese exporters must obtain a licence from the State Council to transfer the restricted technologies. Licensing creates uncertainty and delays for partnerships that Indian companies had regarded as a fast route to building domestic industrial capacity.
Specialised manufacturing equipment is also covered, including winding machines, lamination machines and liquid injection machines. A company seeking to manufacture batteries may therefore encounter restrictions at several points, from the production method it wants to license to the machinery needed to put that method into practice.
Engineers Become Part of the Supply Chain Problem
Chinese restrictions reach beyond physical materials and equipment. Chinese officials have reportedly given verbal encouragement to regulatory agencies to curb the movement of specialised employees and equipment to India and Southeast Asia.
The effort is viewed as an attempt to prevent companies from shifting production bases in anticipation of higher tariffs from the United States. Tariffs are taxes on imported goods, and the prospect of higher charges can influence where companies choose to manufacture.
Foxconn, an Apple assembly partner and a major participant in India's electronics manufacturing expansion, has recalled hundreds of Chinese engineers from its Indian factories. The recall included staff from Yuzhan Technology, a Foxconn component unit in Tamil Nadu.
Foxconn has begun bringing in Taiwanese engineers as replacements. The disruption shows how manufacturing expansion depends on experienced people as well as investment and equipment. High precision production requires technical expertise, and replacing that expertise can complicate efforts to establish more operations locally.
The battery and electronics difficulties share a practical feature: opening a factory requires access to the knowledge needed to run it. Restrictions on technology transfers and limits on the movement of specialists can both slow India's localisation efforts.
Rare Earth Restrictions Add Another Pressure Point
Beijing imposed export restrictions on seven rare earth elements in April 2025, including samarium, gadolinium, terbium and dysprosium. These materials are used in defence technologies, electric vehicles and wind turbines, making their supply relevant to several Indian industrial priorities at once.
China accounts for the vast majority of global heavy rare earth processing. New licensing requirements create potential supply bottlenecks for Indian companies making electric vehicle motors or permanent magnets for wind turbines.
The United States and other Western countries face similar dependence, but India is exposed while it is still building its industrial base. Limited access to processed materials can complicate projects even when a company has secured other equipment and technology.
Restrictions involving critical minerals such as lithium, gallium and graphite add to the challenge. Graphite is a crucial battery anode material, and China's control over its processing and export gives it considerable influence over the global battery supply chain. Indian manufacturers trying to secure materials for cell production face this pressure alongside the limits on production technology.
The Dates Behind the Manufacturing Squeeze
India's difficulties have developed across several stages rather than through a single restriction. Government incentives, mineral controls and battery technology rules now overlap in the decisions facing manufacturers.
- 2022: Reliance New Energy was among the winning bidders under India's PLI programme for advanced chemistry cell manufacturing.
- April 2025: Beijing imposed export restrictions on seven rare earth elements, including samarium, gadolinium, terbium and dysprosium.
- October 2025: China's Ministry of Commerce and General Administration of Customs announced controls on lithium-ion battery components and manufacturing technologies.
- November 8, 2025: The battery related export controls took effect, introducing licensing requirements for restricted technology transfers.
- January 23, 2026: Reliance's cell manufacturing setback and its immediate focus on storage system assembly formed part of the account of India's clean energy supply chain difficulties.
Reliance's commitment to its broader manufacturing plans sits alongside the stalled Hithium negotiations. No replacement technology agreement or revised start date for cell production was given.
India Considers More Flexible Investment Rules
New Delhi is reportedly considering easing some restrictions on foreign direct investment from countries that share land borders with India. The discussion reflects a possible shift towards judging investment by its economic contribution and potential for technology transfer, rather than solely by the investor's nationality.
Senior government sources have indicated that investment creating jobs and domestic capacity should be welcomed when it does not compromise sensitive areas. Telecom, defence and strategic infrastructure remain central security concerns in that assessment.
Indian manufacturers forced to import finished goods because they cannot obtain technology or machinery for local production lose opportunities to create employment at home. That trade off is helping drive the argument for a more selective approach to Chinese investment and procurement.
Industry leaders are calling for changes tailored to individual sectors. Textiles and engineering are among the industries with substantial dependence on Chinese machinery and intermediate goods, meaning products or components used to make other products. Controlled access to partnerships in those sectors is seen as necessary for international competitiveness.
India's objective remains greater self reliance over time. The policy debate concerns how much flexibility companies need now to bridge technology gaps while protecting sensitive industries.
Domestic Battery Efforts Offer Other Routes
Indian companies are also exploring technologies that could reduce dependence on Chinese inputs. Research into sodium-ion and solid-state batteries offers a possible longer term advantage through materials that are more abundantly available domestically or from countries considered friendlier suppliers.
Ola Electric has announced the successful indigenous development of lithium-ion battery cells and plans to integrate them into vehicles by 2026. That effort represents one route towards domestic cell technology alongside the search for overseas licensing agreements.
Mahindra has developed an automated assembly line using patented processes. Even these domestic initiatives often rely on Chinese cells in the immediate term, showing that local assembly expertise and local cell production can develop at different speeds.
China's controls may push Indian firms to invest more in research and development as they respond to uncertain access to suppliers. Continued investment in academic institutions and research partnerships across the battery value chain will be crucial to expanding India's capabilities.
Reliance, Adani and JSW meanwhile face immediate decisions about technology, costs and the scope of local manufacturing. India's response combines a debate over investment rules with efforts to develop domestic alternatives, while companies continue assembling systems that depend on a wider international supply chain.
The Bottom Line
- Reliance paused lithium-ion cell manufacturing plans after technology negotiations with Xiamen Hithium stalled.
- Reliance says its broader programme, from battery cells to containerised storage systems, remains on its target timelines.
- Adani and JSW are prioritising battery pack and container assembly while seeking economical cell technologies.
- China's battery export controls took effect on November 8, 2025, covering specified materials, equipment and production technologies.
- Restrictions on seven rare earth elements and the movement of specialised engineers add pressure to Indian manufacturing.
- India is considering more selective investment rules while companies pursue domestic battery development and alternative technologies.