A 350,000 person waitlist and a costly India launch
Revolut plans to launch its digital payments app in India later in 2025, starting with 350,000 people on its waitlist before opening access more widely. The London born financial technology company aims to reach 20 million Indian customers by 2030, combining domestic payments through the Unified Payments Interface (UPI) with international spending through a Visa prepaid card.
Contents
- A 350,000 person waitlist and a costly India launch
- What customers will get at launch
- Why UPI gives a new app immediate reach
- What the licenses allow and why identity checks matter
- Why India required more than £40 million in technology work
- PhonePe, Google Pay and banks already serve the market
- Travel, education and overseas work shape the appeal
- How Revolut plans to make the business work
- Which additional features could follow
- The rollout from late 2025 to the 2030 target
- What to Know
As of October 15, 2025, the plan rests on two regulatory permissions: a prepaid payments instrument license granted by the Reserve Bank of India (RBI) and a separate license permitting foreign exchange services. Customers will receive a digital wallet and a prepaid card, bringing everyday rupee payments and overseas spending into one app.
Revolut says it has invested more than £40 million to localize its technology and store required payments data in India. India is the only market where the company has undertaken this work at such scale. The investment makes regulatory compliance a substantial part of the launch, alongside attracting customers and building payment connections.
The company already operates in more than 30 countries across Europe, Asia and the Americas. Its brand has grown around money management through an app, travel spending and clear fees. India will test whether that combination can win customers in a market where instant payments and inexpensive digital services are already familiar.
Young, aspirational consumers who use smartphones for daily money tasks are the main audience. They already have many ways to pay, including PhonePe, Google Pay, Paytm and banking apps. Revolut's task is to make its domestic and international services useful enough for people to add another financial app.
India is one of the world's largest digital payments markets, supported by UPI, a nearly universal network of merchant QR codes and improving mobile internet. Revolut is making its entry into that established network while pursuing wider expansion, including recent product moves in the UK and growth plans in the Americas.
What customers will get at launch
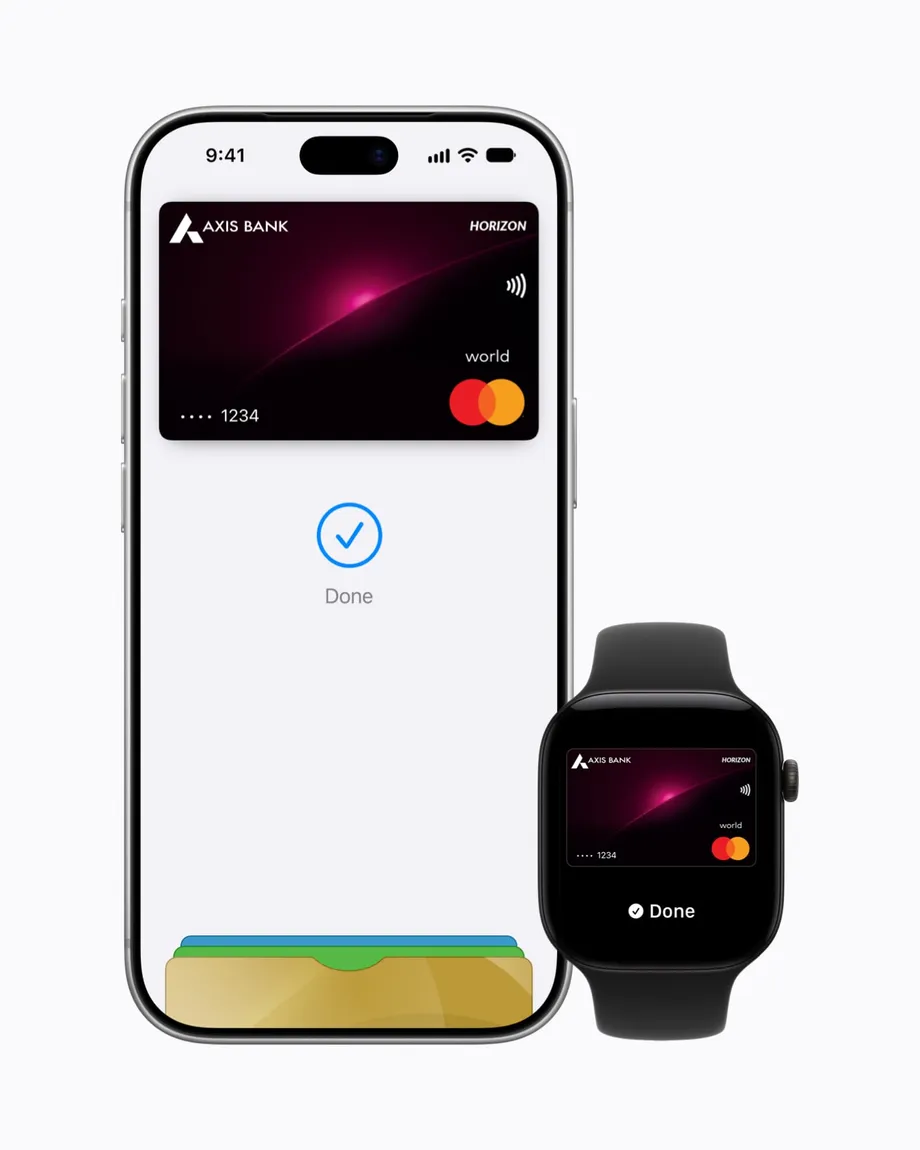
Indian customers will be offered a digital wallet supporting UPI for domestic transactions and a prepaid card using the Visa network for global spending. A prepaid product works with money loaded in advance: customers put funds into the wallet, then use that balance for eligible transfers or purchases.
Revolut wants the combination to cover local shopping, travel, education and other expenses involving another country. Its foreign exchange capability, already central to its business elsewhere, is intended to sit beside rupee payments so customers can manage both needs in one place.
Domestic UPI connections are expected to depend on partnerships with banks and the National Payments Corporation of India (NPCI). Once those integrations are live, users should be able to pay through standard UPI handles and QR codes, reaching neighborhood shops, online checkouts and people receiving transfers.
The Visa card serves a different purpose. Outside India, where UPI is not the usual payment method, Visa acceptance would let customers use their prepaid funds for card purchases. Revolut plans to pair this with currency conversion in the app and clear information about rates and charges.
The exact launch date, complete feature list, customer fees and partner details have not been specified. The initial rollout is planned for later in 2025, with wider public access following the waitlist phase. Features beyond the core wallet, UPI and card services are expected to depend on local rules and partnerships.
Why UPI gives a new app immediate reach
NPCI developed and operates UPI as an instant payment system connecting accounts across banks. A person can send or receive money using a virtual payment address, a phone number or a QR code, rather than entering full bank details each time. NPCI describes the system on its UPI information page.
Transfers happen in near real time and are typically free for consumers. For a merchant, accepting a payment can be as simple as displaying a printed QR code at the counter. Partner banks process transactions, and two factor authentication provides two checks on a user's identity when authorizing a payment.
UPI's central advantage is interoperability: an app can connect with accounts across many banks. Customers and merchants can use different services while still paying one another. For Revolut, joining that network offers broad acceptance without asking shops to adopt a payment system used only by its customers.
The network already handles billions of transactions each month. It has also added UPI Lite for payments of small amounts and support for credit on UPI through selected networks. These developments have made UPI part of a wider range of everyday transactions.
Revolut is building on this domestic infrastructure rather than creating a closed payment network. That provides reach and a familiar way to pay, but also means its basic local payment service will use the same underlying system as many competitors.
What the licenses allow and why identity checks matter
RBI's prepaid payments instrument license allows Revolut to issue a wallet and prepaid card in India. Wallets do not pay interest, and their permitted use and limits are linked to the customer's identity verification status.
Know your customer checks, usually called KYC, require customers to verify who they are. Users will need to complete these checks to unlock full limits. Under RBI rules, wallets with full KYC can connect to UPI, allowing their balances to be used across the wider payment network.
Revolut's separate foreign exchange permission covers services such as travel cards, currency conversion and certain outward remittances within regulatory limits. An outward remittance is money sent from India to another country. The permitted service depends on both the company's authorization and the rules governing the transaction.
Credit products, investment features and crypto services would require additional permissions in India. Revolut may consider such products later, but they are not assured additions. The immediate plan centers on prepaid payments and foreign exchange rather than the complete range of services available through Revolut in other markets.
For customers, the practical sequence is to join the rollout, complete the required checks, fund the wallet and activate the prepaid card. UPI use will depend on live partner integrations, while international transactions and currency conversion must remain within Indian regulations and the terms of Revolut's foreign exchange permissions.
Why India required more than £40 million in technology work
India requires specified payments data to be stored within the country. RBI introduced the data localization policy to strengthen security, improve access for supervision and help authorized entities respond promptly to lawful requests.
For a global app, meeting those requirements can mean building separate technology systems rather than relying entirely on infrastructure shared across countries. Revolut says its investment of more than £40 million has gone toward localizing technology and meeting India's storage requirements.
The company says India is the only market where it has gone this far with localization. That makes the launch a substantial technical commitment as well as an expansion into a new customer market.
India's regulatory environment has become stricter as digital payments have grown. Prominent supervisory actions involving payment firms outside the banking sector in recent years have reinforced the focus on data security, operational resilience and KYC. Operational resilience means keeping services working reliably and being able to recover when systems fail.
Revolut will need to maintain compliance throughout customer onboarding, transaction monitoring and data handling to avoid interruptions to its services. Its local leadership team is led by Paroma Chatterjee, and its India infrastructure has been built to meet RBI and NPCI standards.
PhonePe, Google Pay and banks already serve the market
PhonePe and Google Pay dominate UPI transaction volumes. Paytm remains a widely recognized name in wallets, merchant payments and other services. Banks promote their own UPI apps and issue foreign exchange cards aimed at travelers, while newer consumer finance brands compete through polished interfaces, rewards and lifestyle features.
Many of these providers use the same payment networks Revolut is joining, especially UPI and Visa or RuPay cards. Access to those networks gives Revolut acceptance, while leaving it to compete on the quality and usefulness of the service built around them.
Revolut's proposed difference is a single app combining domestic payments with international spending and transparent foreign exchange costs. It is targeting people who travel, study overseas, work with foreign clients or buy from international websites.
In other countries, Revolut has attracted attention through predictable foreign currency spending, instant transaction alerts, competitive exchange rates and card controls. Bringing comparable clarity to India could help it find a place among consumers whose needs extend beyond paying local merchants.
Trust will also depend on reliable service, quick handling of disputes and clear explanations of fees and limits. Customers already accustomed to convenient UPI payments will judge the new app against services they use every day.
Travel, education and overseas work shape the appeal
Indian students and professionals traveling abroad need ways to pay in foreign currencies. Families funding tuition and living expenses face similar needs. Leisure travel is growing from major cities and smaller cities, while freelancers and founders increasingly work with clients outside India.
Revolut has targeted these uses in other markets through currency conversion in the app, balances in supported local currencies and instant spending notifications. The proposed Indian service is intended to bring domestic payments together with tools for managing international costs.
A prepaid Visa card paired with a wallet could make travel spending easier to organize than carrying cash or managing several bank cards. Functions associated with Revolut's services elsewhere include converting currency before a trip, locking a misplaced card in the app, creating virtual cards for online bookings and exporting spending records for expense claims. Their availability in India will depend on the local product rollout.
Clear foreign exchange charges would matter to students, travelers and small businesses paying for global services. The attraction is being able to understand how much a purchase or conversion costs and to follow spending as it happens.
Money sent abroad from India is regulated under the Liberalised Remittance Scheme, which sets limits for permitted outward remittances. Tax collection at source may apply to certain transfers. Revolut's foreign exchange permissions would allow specific services, such as travel spending, education payments and approved transfers, within those rules.
UPI remains mostly domestic, although acceptance partnerships are growing in places including Singapore and the United Arab Emirates. Visa provides much of the international card acceptance that Revolut wants to combine with UPI's reach inside India.
How Revolut plans to make the business work
UPI payments typically carry no consumer charge, and merchant fees are low or zero for many transactions. That creates a difficult commercial setting for a new entrant: attracting and supporting customers costs money, while basic local payments offer limited direct fee income.
Revolut's possible revenue streams include foreign exchange margins, card interchange and paid subscription tiers. Interchange is a payment associated with processing card purchases. Paid tiers could bundle premium travel benefits, while other services that might arrive later include merchant payment acceptance and bill payments.
The business will depend on keeping service costs low while persuading customers who use it frequently to pay for additional benefits. Competitors already use rewards and cashback to attract users. Revolut must make exchange rates, spending controls and international reach valuable enough to compete with those incentives.
The target of 20 million Indian customers by 2030 will require sustained spending on product development, marketing and support. Fast identity checks, smooth onboarding and responsive help will be central to turning interest from the initial waitlist into regular use.
Payment reliability is another practical test. Repeated card declines or problems paying through UPI would damage confidence. As a third party app, Revolut will rely on partner banks to route UPI transactions, making coordination and uptime essential parts of the customer experience.
Which additional features could follow
Revolut has indicated that the Indian app could eventually include budgeting tools, spending analytics, savings vaults, prepaid card rewards and supervised accounts for teenagers. These would broaden the app from a payment service into a place to organize everyday finances.
Other possible additions include instant card freezing, virtual cards and dynamic CVV for online payments. A CVV is the security code used for card transactions; a dynamic version changes rather than remaining fixed. Security controls and rewards are among the features that could arrive in phases.
Local regulations and commercial partnerships will determine the final feature set. Credit, investments and crypto would need additional approvals and may arrive later, if at all. The phased approach leaves the core payment products as the starting point while other services are considered.
Changes to rules covering wallets, credit on UPI or international transfers could also require product changes. Localizing technology is intended to reduce policy risk, but Revolut will still need to adapt as regulatory guidelines develop.
India forms a central part of the company's wider expansion. Revolut has also explored a credit card launch in the UK and a larger US presence. In India, its immediate challenge is to connect its global spending proposition with a domestic payment system that customers already use extensively.
The rollout from late 2025 to the 2030 target
Revolut plans to begin with its 350,000 person waitlist and then open the app to the wider public. Customers entering each phase will need to complete the relevant checks before using the full range of permitted wallet and card functions.
The milestones set out so far are:
- October 15, 2025: Revolut's India plan includes a UPI enabled wallet, a Visa prepaid card, prepaid payments and foreign exchange permissions, and more than £40 million invested in localized technology.
- Later in 2025: The company plans to begin access for the 350,000 people on its waitlist, followed by wider public availability.
- After the initial rollout: Additional features could arrive in phases, depending on local regulations, partnerships and any further permissions required.
- By 2030: Revolut aims to reach 20 million customers in India.
The first users will test the practical combination at the heart of the launch: familiar UPI payments at home and Visa spending abroad, managed through one app. Revolut's ability to deliver clear costs, dependable transactions and effective support will shape whether that combination becomes part of their daily financial lives.
What to Know
- Revolut plans to launch in India later in 2025, beginning with 350,000 waitlisted users before expanding access.
- The core products are a UPI enabled digital wallet and a Visa prepaid card for domestic and international use.
- The company holds an RBI prepaid payments instrument license and separate permission for foreign exchange services.
- More than £40 million has been invested in localizing technology and meeting India's payments data requirements.
- Revolut aims for 20 million Indian customers by 2030, with young smartphone users as its main audience.
- PhonePe, Google Pay, Paytm, banks and newer finance brands provide established competition.
- Potential revenue includes foreign exchange margins, card interchange and paid tiers, while UPI offers limited direct fee income.
- Additional features will depend on regulations and partnerships; credit, investments and crypto require further permissions.