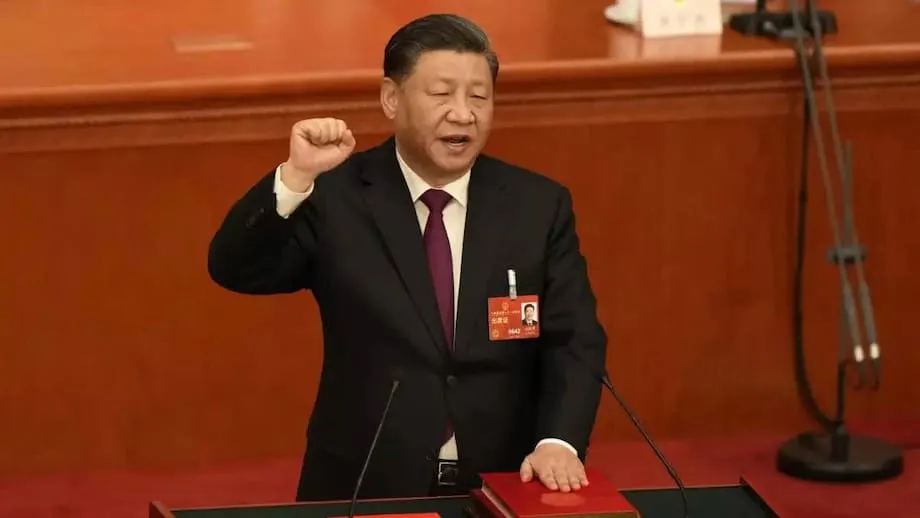
A founder's detention puts corporate China on edge
Great Microwave Technology, a Shanghai listed manufacturer of radio frequency components, disclosed on September 22 that its founder, Yu Faxin, had been taken away by China's top anti corruption agency. Known for advanced semiconductor work supporting military applications, Yu is now being held under liuzhi, a form of detention outside the criminal court system that increasingly reaches business leaders.
Contents
- A founder's detention puts corporate China on edge
- How liuzhi reaches private business
- A different route from criminal detention
- Bao Fan and the shock to investors
- Years of disappearances, different outcomes
- The political expectations facing private companies
- Zhongzhi exposes the pressure on private finance
- Why uncertainty spreads beyond a share price
- Debt blacklists add another personal risk
- Companies strengthen internal checks and continuity plans
- Foreign businesses reconsider travel and sensitive work
- What to Know
His case brings together two pressures facing Chinese companies: a widening campaign against corruption and growing uncertainty about what happens when a senior executive disappears. Liuzhi detentions rose sharply in 2024 to about 38,000 cases. For companies, the immediate problem can be much simpler than the legal questions: colleagues cannot reach the person who makes decisions, signs agreements or maintains relationships with lenders.
A familiar sequence has emerged. An executive disappears from public view, and a company filing says the board or colleagues have lost contact. Days or weeks pass without official details. Sometimes the company later says the executive is cooperating with investigators. Other cases eventually lead to trials and sentences for corruption or financial offenses.
The silence between disappearance and explanation feeds speculation among investors and leaves employees uncertain about their company's direction. Recent cases have touched technology, finance, property and consumer businesses, making the risk relevant far beyond any single industry.
China's leadership wants private companies to support national priorities and accept closer supervision. Entrepreneurs must now weigh political and legal exposure alongside products, sales and company valuations. Yu's detention shows how those pressures can reach a business working in advanced technology with military uses.
How liuzhi reaches private business
The National Supervision Law of 2018 created liuzhi, which translates as retention in custody. It allows the National Supervision Commission, or NSC, and its local branches to detain and question people suspected of offenses connected to public power.
The system covers Communist Party members, state employees, managers at public institutions and state companies, and private individuals whose work intersects with public functions. Its reach therefore extends to contractors, suppliers and business partners dealing with public bodies.
Investigators can hold people at designated locations, question them without a lawyer present and restrict contact with relatives or colleagues. Under recent changes, detention can last up to eight months, and investigators can restart the clock when new suspicions arise.
Rights advocates criticize the secrecy and lack of judicial oversight. Chinese authorities describe liuzhi as a necessary tool for breaking networks of patronage and recovering stolen money. Those competing views concern the same central feature: investigators have broad powers to hold and question people before a case reaches prosecutors.
A different route from criminal detention
Ordinary criminal detention follows China's Criminal Procedure Law. Police need court oversight for extended detention, and suspects have clearer access to legal counsel. Liuzhi follows supervision law, allowing the NSC to detain a person without court approval.
After months of questioning, supervision investigators may transfer a case to prosecutors. Statements and documents collected during liuzhi can then shape the charges that follow. Business leaders can therefore spend a prolonged period in a separate investigative process before an ordinary criminal prosecution begins.
For families and companies, restricted communication makes it difficult to understand what is happening or plan around an executive's absence. Party discipline investigators gain a broad route into corporate and financial affairs, including dealings between private businesses and public institutions.
Yu's case has entered that system, but no further details about his suspected offenses or a timetable for the investigation were disclosed. His company's employees and investors face the uncertainty that accompanies the early stages of such cases.
Bao Fan and the shock to investors
Bao Fan, the founder of China Renaissance and a prominent technology dealmaker, became one of the clearest examples of how a missing executive can unsettle a company. In early 2023, his firm disclosed in a stock exchange filing that it could not reach him.
China Renaissance shares plunged as much as 50 percent. The company later said Bao was cooperating with certain authorities. He eventually resigned from his leadership positions, while the firm worked to stabilize operations and clients and business partners reassessed their exposure.
The episode shows why an absence can become a corporate event before the public learns much about an investigation. A founder may hold relationships with customers, investors and officials that cannot immediately pass to a replacement. Shareholders must make decisions while the company itself has limited information.
Outcomes across Chinese business have varied widely. Some executives return after brief absences. Others lose their positions, give way to temporary managers or receive lengthy prison sentences. Employees, lenders and suppliers must respond during the uncertain period, when supply chains can stall, credit lines tighten and projects slip.
Years of disappearances, different outcomes
Several of China's best known business figures have vanished from public view under very different circumstances. Their cases span regulatory conflict, assistance to investigators and criminal convictions.
- In 2017, financier Xiao Jianhua was taken from a Hong Kong hotel. He was later sentenced in a mainland court to 13 years in prison for financial crimes.
- In 2018, former Anbang Insurance chairman Wu Xiaohui was tried for fraud and embezzlement and received an 18 year prison sentence. Oil and finance businessman Ye Jianming also disappeared from public view that year, and his status remains undisclosed.
- In late 2020, Alibaba founder Jack Ma withdrew from public view after criticizing financial regulators. The planned listing of Ant Group, Alibaba's finance affiliate, was halted. Ma later resurfaced abroad and has kept a low profile in China.
- In early 2023, China Renaissance disclosed its loss of contact with Bao Fan, before later saying he was cooperating with authorities.
- On September 22, 2025, Great Microwave Technology disclosed that Yu Faxin had been taken into liuzhi custody.
Property tycoon Ren Zhiqiang disappeared after attacking the leadership's handling of the pandemic. He received an 18 year prison sentence on corruption charges. His case added another prominent name to the list of business figures whose absence ended in a lengthy sentence.
Fosun's Guo Guangchang and brokerage chief Yim Fung returned to work after brief absences during which they were said to be assisting investigators. Some returning executives keep quieter profiles or give up titles. Confidence can remain damaged even after a business leader reappears.
The political expectations facing private companies
China's leaders continue to welcome private investment while expecting private economic power to serve national priorities. Regulators have tightened supervision of internet platforms, consumer financial technology, online tutoring, gaming and data security.
A new financial regulator was created to oversee most finance outside banking. The aim is to close gaps left when several agencies shared responsibility, limit risky behavior and prevent regulatory arbitrage. That term describes businesses using differences between rules or regulators to escape restrictions.
Xi Jinping, the Communist Party's general secretary and China's president, has expressed the moral expectations placed on entrepreneurs in these words:
Private enterprises and entrepreneurs should be rich and responsible, rich and righteous, and rich and loving.
Finance workers have also received warnings against the culture of excess associated with Wall Street. Authorities have tightened rules on executive pay and bonuses. In the official view, these steps should reduce incentives for risky behavior and direct money toward advanced manufacturing, social services and projects serving the real economy.
For a private company, commercial success now comes with an expectation of visible alignment with those goals. Regulatory engagement, executive conduct and the destination of investment all carry weight alongside business performance.
Zhongzhi exposes the pressure on private finance
Zhongzhi Enterprise Group brought the connection between financial distress and investigative pressure into focus in late 2023. One of China's largest shadow banking conglomerates, it told investors that it was severely insolvent, meaning it could not cover its obligations.
Beijing police soon opened a criminal investigation into its wealth management arm and said they had taken compulsory measures against suspects. Around the same period, two executives at companies controlled by Zhongzhi investment units went missing, according to those companies' exchange filings.
Missed payments by a major trust linked to Zhongzhi prompted protests by angry investors. The episode renewed fears that property losses could spread through the wider financial system. It also increased concern that senior managers connected to trust products could face investigation or detention as the government sought to contain the damage.
Shadow banking refers to lending outside traditional bank loans. Trust companies, asset managers and wealth products collect investors' money and channel it to property developers and industrial borrowers. China's shadow banking sector is worth trillions of dollars.
During the property boom, trusts financed ambitious developments. Falling sales and rising defaults later left many facing heavy losses. That strain has encouraged more aggressive regulation and increased the risks for executives managing investment vehicles subject to complex rules and changing enforcement priorities.
Why uncertainty spreads beyond a share price
Listed companies often rush to disclose when they lose contact with an executive. Traders may sell immediately, while banks review their exposure to the company and related businesses. Lawyers and compliance staff search for clarity, slowing deals.
Foreign investors can demand a higher return to compensate for political and legal uncertainty. That can mean lower company valuations or wider credit spreads, the extra borrowing cost a company pays compared with a safer borrower.
Board members may travel less and reduce their public visibility. Investor relations teams can have little to tell shareholders when secrecy rules limit discussion of an investigation. Overseas partners seek stronger compliance commitments, escrow arrangements that hold money until agreed conditions are met, and rights to take over specified responsibilities if problems arise.
The effects can outlast the initial news. Bankers and technology founders weigh the benefits of building larger businesses against the exposure that comes with prominence. An executive's disappearance can unsettle commercial relationships even when the person later returns.
Debt blacklists add another personal risk
China's national credit blacklist creates a separate source of pressure as courts and regulators pursue unpaid debts. People placed on it face restrictions on flights, high speed trains, hotel stays, private schooling and many forms of consumption.
The designation can also make it difficult to obtain credit, sign contracts or arrange suitable travel. For entrepreneurs whose businesses fail, those restrictions turn a commercial setback into a problem affecting daily life and the ability to work.
By September 2024, roughly 200,000 people had been added to the blacklist, compared with about 17,400 in 2019. Nearly half of the new entries were connected to business disputes. The two figures represent an increase of more than eleven times.
Bankruptcy law remains uneven in practice, leaving many commercial failures to end in blacklisting instead of orderly restructuring through the courts. Restructuring allows debts and business operations to be reorganized when a company cannot meet its obligations.
Public accounts have linked several executive suicides to the pressure of investigations and debt enforcement. Those pressures make risk taking less attractive at a time when policymakers are asking entrepreneurs to innovate and invest.
Companies strengthen internal checks and continuity plans
Private businesses are expanding internal compliance teams, giving risk officers greater authority and conducting audits modeled on the methods of state inspectors. These measures put more attention on how companies make decisions and manage their dealings with public institutions.
Some founders are stepping away from prominent public roles while professional managers handle regulatory relationships and external communications. Others are registering more business functions across multiple jurisdictions so operations can continue if a leader is detained.
Continuity has become a practical concern for boards. A company needs people able to maintain relationships, manage decisions and keep work moving when its most influential executive cannot be contacted. Investors and commercial partners increasingly look for protections that address that possibility.
Entrepreneurs are also trimming growth plans to balance ambition against exposure to investigations that can arrive without warning. Stronger internal controls and a quieter public presence have become part of that calculation.
Foreign businesses reconsider travel and sensitive work
International companies with operations or investments in China are reviewing staffing and data policies. Several global consultancies and firms conducting due diligence, the checks businesses make before an investment or transaction, have faced raids or staff detentions.
Security teams are changing travel procedures for employees working in sensitive areas, including finance, data services and technology connected to defense. A growing number of foreign executives arrange visits to avoid major political events, when controls tighten and inspections increase.
Domestic entrepreneurs see closer alignment with state priorities as the safest course. Advanced manufacturing, green energy projects and rural revitalization give businesses a clearer account of how their work supports government goals when regulators or investors ask questions.
Those choices still leave companies balancing growth with the possibility of sudden scrutiny. Yu Faxin's detention, Bao Fan's disappearance and the financial strain surrounding Zhongzhi show how quickly leadership uncertainty can become a problem for workers, lenders, investors and business partners.
What to Know
- Great Microwave Technology disclosed on September 22 that founder Yu Faxin had been taken by anti corruption investigators and placed under liuzhi.
- The National Supervision Law of 2018 created liuzhi. It permits detention outside criminal courts, without court approval and with restricted access to lawyers and relatives.
- Recent changes allow detention for up to eight months, with the clock able to restart when new suspicions arise. Liuzhi detentions rose to about 38,000 in 2024.
- Executive cases have ended in brief absences, resignations and lengthy prison sentences. China Renaissance shares fell as much as 50 percent after it disclosed losing contact with Bao Fan.
- Zhongzhi's insolvency and the investigation into its wealth management arm connected financial distress with wider concern about missing executives.
- Roughly 200,000 people had been added to the credit blacklist by September 2024, compared with about 17,400 in 2019. Nearly half of the new entries involved business disputes.
- Companies are strengthening compliance, planning for leadership absences, reducing public visibility and aligning investment with state priorities.