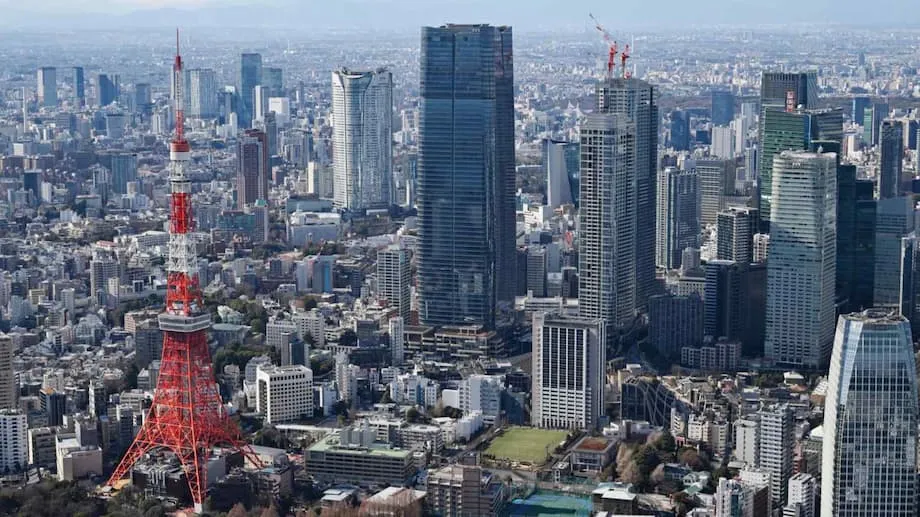
Foreign investment reaches 1.14 trillion yen
International investors put roughly 1.14 trillion yen into Japanese property in the first half of 2025, while Tokyo recorded about $13.2 billion in property deals. The buying wave is reaching office towers, apartment buildings, logistics parks, hotels and luxury condominiums, as global investors seek dependable rental income and opportunities for prices to rise.
Contents
- Foreign investment reaches 1.14 trillion yen
- Why the investment arithmetic favors Tokyo
- Office demand returns, with newer towers ahead
- Corporate sales give large funds more to buy
- Apartments, warehouses and hotels attract capital
- Central Tokyo's housing prices pull away
- How foreign buyers enter the market
- Affordability becomes a political concern
- Tourist rentals bring gains and neighborhood friction
- Digital tokens offer another route into property
- Key dates in the investment surge
- Growth forecasts face financing and supply risks
- Key Points
Tokyo's appeal rests on a combination that is becoming harder to find elsewhere: office rents that remain comparatively low by global standards, a weak yen that makes purchases cheaper for investors using dollars or euros, and borrowing costs that remain low internationally. By several measures, the gap between property yields in Tokyo and those in New York or London now favors the Japanese capital.
Japan's nationwide land prices rose 2.7 percent as of January 2025, their fourth consecutive annual increase and the strongest since the early 1990s. Benchmark land prices in the biggest Japanese cities also rose in the first half of 2025, supported by record foreign buying. In the Tokyo Metropolitan Area, the home price index increased 10.7 percent in January compared with a year earlier.
Tokyo's recovery in leasing demand after the pandemic has helped keep property values firm, even as commercial real estate in the United States and parts of Europe faces pressure from refinancing. Refinancing means replacing an existing loan with a new one, potentially at a higher interest rate. Rental occupancy in prime Tokyo neighborhoods is in the middle to upper 90 percent range, supported by migration into the city and brisk hiring by global companies.
As of September 17, 2025, investors see a market with dependable tenants, opportunities to buy and sell large assets, and room for prices to catch up with other global capitals. Residents face a different consequence: rising rents and purchase prices in the districts attracting the most money.
Why the investment arithmetic favors Tokyo
Property investors are looking closely at the difference between rental yields and financing costs. A capitalization rate compares a property's annual operating income with its purchase price. When that rate is comfortably above the cost of borrowing, rental income has more room to cover interest payments.
Quality Japanese assets still offer that gap, while the Bank of Japan guides short term interest rates at very low levels. Nationwide rental yields averaged about 4.2 percent in early 2025. Prime Tokyo properties typically offered 3 to 4 percent, alongside very low vacancy.
The weaker yen lowers the effective entry price for buyers using dollars or euros. Exchange rates also affect the value of rent collected in yen when investors report their returns in another currency. The currency advantage therefore matters both when buying a building and when calculating income from it.
Yu Kawamata, who leads Japan real estate at Morgan Stanley Real Estate Investing, described the attraction in terms of the economy, corporate behavior and financing:
Japan has a positive macroeconomic outlook driven by inflation and wage growth, regulatory changes shifting corporate behavior toward efficiency, and attractive yield spreads with favorable financing terms.
Japan's predictable legal and regulatory environment is another draw. Foreign buyers can purchase freehold property, meaning ownership of the property rather than a lease for a limited period, without special restrictions. That degree of openness is uncommon in Asia.
Foreign capital's share of Japanese real estate transactions has risen to roughly 27 percent from about 21 percent five years earlier, an increase of six percentage points. Rental demand has strengthened alongside investment: residential rents in Tokyo's 23 wards rose around 6 percent compared with a year earlier in late 2024, and occupancy reached about 97 percent in many central districts.
Office demand returns, with newer towers ahead
Tokyo's top tier office market has recovered as businesses seek well located space. In the five central wards, Grade A vacancy hovered near 3.4 percent by late 2024. Grade A refers to the market's premium office buildings. Demand exceeded new supply around major transport hubs, including Tokyo Station and Shinagawa.
Average rents for prime space reached about 32,400 yen per square meter per month, nearly 5 percent above a year earlier. Tenants have favored newer buildings with environmental credentials and smart systems. Older buildings in less central locations face pressure to renovate, lower rents or adapt their floors for more flexible use.
Hybrid working has reshaped demand. Some companies have reduced the size of their headquarters while spending on satellite offices and digital meeting spaces. Many still want well located floors that help bring employees back to the office and provide a base for teams that meet clients.
Premium buildings are benefiting from those choices, widening the gap with secondary properties. Tokyo's office recovery therefore reaches some buildings more strongly than others, even within a market where demand has improved.
Corporate sales give large funds more to buy
Large Japanese companies are selling properties outside their main business activities, giving international funds access to substantial office and mixed use assets. Disposals by automakers and brewers have helped expand the supply of properties suitable for institutional investors while Western markets have been quieter.
Corporate governance reforms are part of this investment story. Investors expect pressure for companies to use their assets more efficiently to encourage further sales. Some managers estimate that such reforms could eventually prompt as much as $3 trillion in sales of assets outside companies' core operations. No timetable was given for that estimate.
Morgan Stanley Real Estate Investing closed a dedicated Japan fund at roughly 131 billion yen, exceeding its original fundraising target. The fund was already investing in residential buildings. A foreign buyer also agreed to purchase Tokyo Garden Terrace Kioicho for about $2.6 billion in a record transaction.
Another global firm joined a regional operator to develop more than 3,000 rental units across Japan. Major investment strategies focused on Asia, including vehicles that raised more than $5 billion, are making Japan a primary focus.
These purchases bring together two sources of opportunity: existing buildings released by corporate owners and new housing developed with local partners. For global funds, the growing pool of large transactions makes it possible to deploy substantial sums into Japan.
Apartments, warehouses and hotels attract capital
Foreign investment in Japanese residential assets rose about 18 percent in 2024 to roughly 740 billion yen. Apartment buildings are central to the buying wave because they combine regular rent payments with strong occupancy in central Tokyo.
Rental buildings in central districts generally maintain occupancy in the middle 90 percent range. Popular apartments with one bedroom, often measuring 25 to 40 square meters, have average asking rents of around 150,000 yen a month. One fund recently acquired five apartment properties containing about 700 units in central wards and is seeking more purchases with global partners.
Logistics properties are another major destination. By some tallies, warehouses and related facilities accounted for about 40 percent of foreign inflows in recent years. High use of e commerce and demand for modern distribution hubs near major cities support the sector, while stable leases appeal to investors seeking predictable income.
Blackstone, GIC and ESR have invested large sums in logistics assets. Developers continue to add capacity in corridors around Tokyo and Yokohama to meet the needs of online commerce.
Hotels have returned to favor as inbound tourism rebounds. Tokyo, Osaka and resort areas are attracting interest from investors seeking exposure to visitor spending. Across these sectors, buyers are pursuing different sources of income: household rents, warehouse leases and hotel stays.
Central Tokyo's housing prices pull away
Condominium prices in Tokyo's 23 wards have risen roughly 64 percent since 2021, far faster than prices across the wider metropolitan area. The average price of a new condominium in the core wards exceeded about 112 million yen in 2024.
In March 2025, the average across greater Tokyo briefly reached about 104.9 million yen before easing the following month as the mix of properties sold changed. Used apartments also became more expensive, with an average price of roughly 44.5 million yen in April 2025, more than 28 percent above a year earlier.
Redevelopment districts have recorded some of the sharpest land price increases. Surveys show double digit gains in places such as Nakano and Suginami, while the Sakura Stage district in Shibuya recorded an increase of roughly 33 percent.
Luxury housing demand has grown as multinational executives and wealthy buyers seeking second homes return to Tokyo. In Daikanyama, large apartments above 200 square meters on high floors are scarce, and prices of $1 million or more are no longer unusual.
Rents reflect the same pressure. Asking rents in the middle of the market rose around 6 percent in late 2024 across the 23 wards, while well located buildings recorded occupancy near 97 percent. New condominium supply in central Tokyo was unusually limited in 2024. Developers plan more projects, but the pipeline still trails demand.
Private buyers are increasingly searching outside the Golden Triangle of Minato, Chiyoda and Chuo. Koto, Sumida, Nakano and Meguro are among the areas attracting attention as buyers look beyond the most expensive central districts.
How foreign buyers enter the market
Foreign nationals can buy homes, land and commercial buildings in Japan without citizenship, a visa or special permits. Nonresidents generally follow a process similar to that used by domestic buyers, beginning with viewings and an offer.
Buyers typically sign a contract and pay a deposit, then settle the transaction once financing is finalized and registration is completed. Licensed brokers and judicial scriveners handle much of the paperwork. Judicial scriveners are legal professionals who help prepare documents and complete registration procedures.
Transactions usually close within 60 to 90 days. Upfront costs often total 5 to 6 percent of the purchase price, covering brokerage, registration, taxes and insurance. Most taxes are calculated using government assessed values, which can be below market prices.
Banks increasingly assess foreign borrowers according to income and their capacity to make debt payments, rather than looking only at collateral and residency status. Collateral is an asset a lender can claim if a borrower fails to repay. Japan's low lending rates remain an important part of the purchase calculation for residents and overseas investors alike.
Affordability becomes a political concern
Rising prices have widened the gap between property values and local incomes in prime Tokyo wards. The increase since 2021 has intensified debate about foreign buyers, with some opposition parties proposing a vacancy tax aimed at speculative purchases or targeted acquisition limits in districts where prices have become especially heated.
Japan currently places virtually no restrictions on foreign ownership of residential property. Other markets require approvals or charge overseas buyers extra taxes. Japan's openness helps attract investment, while the rise in housing costs puts pressure on policymakers to address affordability.
Reliable data on the precise scale of foreign buying is limited. Surveys suggest that in several central wards, nonresident owners purchase 20 to 40 percent of new condominiums. Domestic investors are also active, and substantial local funds continue to flow into urban property.
Tokyo's population continues to grow even as Japan's national population declines, concentrating demand in the capital. Residents looking for homes face competition in the same districts where investors see reliable tenants and potential rental growth.
Japan also has about 9 million vacant homes, known as akiya. Many are in rural or suburban areas far from employment and services. National and local programs are trying to return more of them to use, but substantial renovation costs can make the economics difficult.
Central Tokyo's tight housing market and the empty homes in regional towns reflect demand in different places. A vacant house far from jobs and services offers a very different proposition from an apartment in a central ward.
Tourist rentals bring gains and neighborhood friction
Land values in Asakusa's Kaminarimon area rose about 29 percent in 2025 and now stand at nearly twice their level before the pandemic. The increase has been linked to rapid growth in rentals for short stays and an influx of overseas capital.
Some buyers have paid aggressive prices for small buildings and apartments that can be rented to tourists. Their calculations depend on strong occupancy rather than the relationship between the purchase price and the property's current income.
Rentals for short stays have been legal since 2018. By May 2025, about 32,000 properties were registered nationwide, with more than a third in Tokyo's 23 wards. In Taito Ward, which includes Asakusa, listings had increased about 80 percent compared with May 2019.
During February and March 2025, roughly 465,000 people stayed in such rentals across Japan, nearly half as many again as a year earlier. Foreign visitors made up more than half of guests, and Chinese travelers accounted for the largest share among nationalities.
The growth has raised rents in tourist corridors and brought complaints from residents about noise and waste disposal. City officials are considering targeted enforcement and rules to protect quiet hours while allowing hosts to accommodate demand during busy travel periods.
Investors relying on tourist stays will need to follow changes in municipal regulations. Their income depends on visitor demand and on the rules governing how properties can operate.
Digital tokens offer another route into property
A company based in Tokyo plans to tokenize about $75 million of central city property on the Oasys blockchain. Tokenization divides economic interests in assets into digital tokens that investors can hold, providing a way to invest in a building without buying an entire apartment or property.
The company's longer term ambition is to tokenize more than $200 billion in assets, equivalent to about 1 percent of Japan's property market. It plans to work with licensed entities and special purpose vehicles overseas to meet compliance requirements. A special purpose vehicle is a separate legal entity established for a particular transaction or investment.
Yushi Sekino, the chief executive leading the effort, said the aim was to reduce practical barriers for nonresident buyers by digitizing ownership and simplifying fees and paperwork:
We are building next generation investment infrastructure to make Japanese real estate globally accessible.
Real estate tokenization is gaining traction worldwide, and Japan's sophisticated market and established rules make it a candidate for wider adoption. Smaller investors could obtain a fractional interest in Tokyo properties that generate income, rather than having to fund a whole purchase.
For large institutions, digital systems could speed settlement and allow investments to reach more buyers. The quality of execution and the protection given to investors will help determine how quickly these models grow.
Key dates in the investment surge
Tokyo's current property market reflects developments over several years. Housing prices, tourism rentals and investment flows have grown at different speeds, with the strongest housing gains concentrated in the capital's central wards.
- 2018: Rentals for short stays became legal.
- Since 2021: Condominium prices in Tokyo's 23 wards have risen roughly 64 percent.
- 2024: Foreign investment in Japanese residential assets reached roughly 740 billion yen, up about 18 percent. The average new condominium price in the core Tokyo wards exceeded about 112 million yen.
- Late 2024: Residential rents in the 23 wards rose around 6 percent compared with a year earlier, while Grade A office vacancy in the five central wards stood near 3.4 percent.
- January 2025: Nationwide land prices were up 2.7 percent, and the Tokyo Metropolitan Area home price index rose 10.7 percent compared with a year earlier.
- March and April 2025: The greater Tokyo new condominium average briefly reached about 104.9 million yen in March. Used apartments averaged roughly 44.5 million yen in April.
- May 2025: About 32,000 properties offering rentals for short stays were registered across Japan.
- First half of 2025: International investors put roughly 1.14 trillion yen into Japanese property, while Tokyo recorded about $13.2 billion in deals.
By September 17, 2025, these developments had brought international investment, rising rents and resident affordability into the same policy debate. The market's attraction to global capital had grown alongside the cost of securing a home in its most sought after districts.
Growth forecasts face financing and supply risks
Several private forecasts point to a 5 to 6 percent rise in Tokyo property prices during 2025, following an 8 percent gain in 2024. That would mean continued growth at a slower pace. Developers intend to increase condominium launches, although central ward supply is still expected to fall short of demand.
Urban migration and international hiring are expected to keep residential occupancy tight, with hiring also supporting luxury housing demand. In offices, high quality towers near transport links are expected to retain leasing momentum, while older buildings may need improvements or a different market position to compete.
Construction figures suggest limits to future housing supply. Authorized housing starts fell about 1 percent in 2024 and dropped 4.6 percent in January 2025. Slower additions to the housing pipeline could put further pressure on prices and rents, especially in the central city.
Interest rates and exchange rates remain central risks. A faster increase in Japanese rates would narrow the gap between property income and borrowing costs, even if rates remained low internationally. A stronger yen would reduce the currency advantage for overseas buyers.
Stricter rules on tourist rentals could change income for properties dependent on short stays. Policymakers could also revisit measures affecting foreign ownership in particular districts. For now, liquidity, stable demand and rental growth continue to support investor interest in Tokyo real estate.
Key Points
- Foreign investors put roughly 1.14 trillion yen into Japanese property in the first half of 2025; Tokyo recorded about $13.2 billion in deals.
- Nationwide land prices rose 2.7 percent as of January 2025, their fourth consecutive annual increase.
- Low borrowing costs, a weak yen, rental demand and open ownership rules attract international buyers.
- Foreign capital's share of Japanese property transactions rose to roughly 27 percent from about 21 percent five years earlier.
- Apartment buildings and logistics assets are major destinations for investment, while tourism supports renewed interest in hotels.
- Condominium prices in Tokyo's 23 wards have risen roughly 64 percent since 2021, increasing pressure on affordability.
- Tourist rentals are expanding, bringing income opportunities alongside complaints about noise and waste.
- Digital token projects seek to widen access to property investment, including a planned $75 million project using Oasys.
- Private forecasts point to Tokyo price growth of 5 to 6 percent in 2025, with interest rates, currency movements and possible rule changes among the risks.