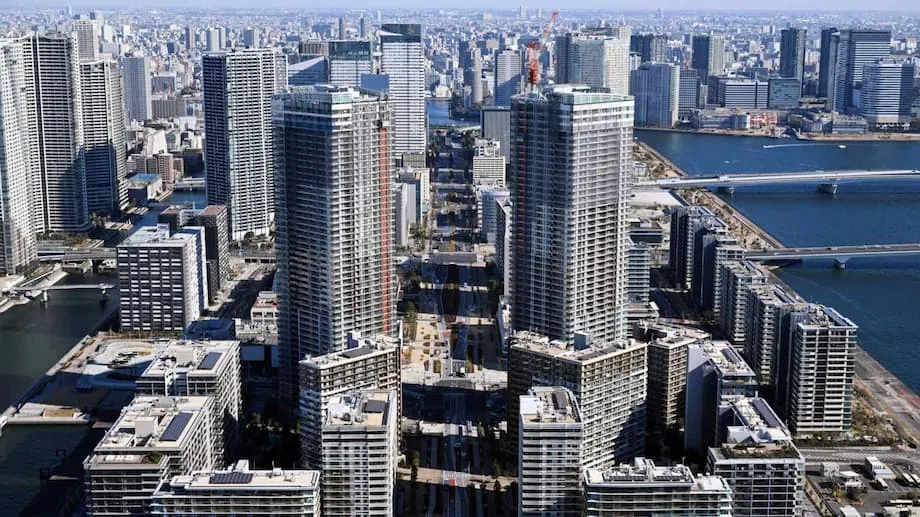
Higher rents squeeze the budget for city life
Private sector rents in Tokyo's 23 wards rose 1.1 percent from a year earlier in March 2025, the fastest increase since October 1994. Behind that relatively small percentage is a growing strain on household budgets: more renters in Tokyo and other large Japanese cities are spending over 30 percent of their income on housing.
Contents
- Higher rents squeeze the budget for city life
- Family apartments face the steepest increases
- Why households are returning to central neighborhoods
- Higher costs make new housing harder to add
- Tourist accommodation competes for some homes
- How the pressure developed over time
- What a rent share above 30 percent means
- Rent limits bring choices over protection and supply
- Adding homes where demand is strongest
- How tenants can manage the next renewal
- What would ease the strain on household budgets
- Key Points
The 30 percent threshold is a common affordability benchmark used by researchers and housing agencies. Crossing it leaves less money for food, education, healthcare and savings. For households hoping to buy a home, a higher monthly rent can also push a down payment further out of reach.
Families are returning to city centers after the pandemic, competing for scarce apartments in convenient neighborhoods. Employers have revived office attendance, tourist flows are back near record levels, and households are seeking short commutes, better schools and easy access to rail networks.
Tokyo's 23 wards face the most visible pressure, although Osaka, Nagoya and Fukuoka show similar patterns. Construction, financing and property operating costs have risen, while record condominium prices are keeping would be buyers in rented homes for longer.
The squeeze has several connected causes. Limited supply, changing preferences and a shift toward smaller average apartment sizes all affect what renters can find and afford. Family homes face especially sharp increases. The choices facing households are concrete: pay more for the same space, accept a smaller home, or move farther from the places they need to reach each day.
Family apartments face the steepest increases
Asking rents for smaller apartments in Tokyo's 23 wards rose about 7.6 percent over five years, while rents for family sized dwellings climbed roughly 26.1 percent. The increase for family homes was more than three times the increase for smaller units, a gap of 18.5 percentage points.
Families seeking space near schools or childcare often search in the same neighborhoods. When few suitable homes are available, competition becomes concentrated in a narrow part of the market. Central neighborhoods in Osaka and other large metropolitan areas also command a growing premium where transport links and amenities are strong.
Around the University of Tokyo's Hongo campus, typical studio asking rents are near ¥140,000 a month, according to local market trackers. That is ¥10,000 to ¥20,000 more than five years earlier. The figures illustrate how even a small apartment near a major destination can require a substantial monthly payment.
The official rent index and advertised rents measure different parts of the market. The index follows rent prices across the housing it covers; asking rents show what owners seek from people searching for a home. Rent is also a large expense that households cannot easily reduce from one month to the next. Economists warn that increases can weaken other spending while food, energy and service prices remain elevated. The rent and condominium figures capture both the monthly squeeze and the difficulty of buying instead.
Why households are returning to central neighborhoods
Tokyo's dense rail network makes commuting convenience a valuable part of a home's price. Central wards offer shorter travel times and access to more jobs. As office attendance returns, those advantages have become more pressing for people who must travel to work regularly.
Research into Tokyo's rental market found that both proximity to stations and the clustering of train and subway stations have a measurable effect on rents. A home's appeal depends on more than the distance to its nearest station. The rank order of nearby stations matters too, with access to several stations offering different lines and service patterns helping a property command a higher rent.
The study of station clustering helps explain why neighborhoods where multiple lines meet can face stronger price pressure when demand returns. Several useful transport choices can save time across a household's working week, increasing competition for homes nearby.
City centers also concentrate childcare, programs after school, health services and cultural amenities. Parents balancing work and school schedules may accept a smaller floor plan in exchange for easier daily journeys. Tourism has revived service sector jobs in central districts, adding another reason to live close to the core.
Households are therefore weighing space against time. An apartment farther out may cost less, while a central address can reduce commuting and make several daily tasks easier. When many people make the same choice, demand rises most strongly in the neighborhoods offering those practical benefits.
Higher costs make new housing harder to add
Builders face more expensive materials and labor, and financing has become less favorable as interest rates rise from historic lows. Those costs make it harder to add homes quickly enough to meet demand in popular urban districts.
Landlords also face higher refurbishment and utility costs. Owners seeking to maintain their returns often ask for higher rents when leases come up for renewal. Major real estate companies have begun notifying tenants of upcoming increases, and industry surveys suggest most households accept adjustments when they are presented against wider cost pressures.
Condominium prices add to the competition for rentals. Newly built apartments in the Tokyo metropolitan region recently averaged about ¥81.35 million, while those in the 23 wards averaged roughly ¥116.32 million. The difference is about ¥34.97 million, with the ward average around 43 percent higher than the metropolitan figure.
Households whose purchase budgets fall short remain in the rental market. That adds demand to the existing pool of available apartments, and the pipeline of new rental buildings has not been large enough to offset the shift. Rising purchase prices and rising rents therefore reinforce the pressure on people trying to secure a home.
Tourist accommodation competes for some homes
Short term rentals have changed parts of the housing market, especially districts popular with tourists. A peer reviewed study of Tokyo and Osaka found that tourist accommodation can create a rent gap that encourages owners to move homes away from longer residential tenancies.
A rent gap is the difference between what a property earns under its current use and what it could earn under another use. If renting to visitors becomes more attractive financially, an owner may choose that business instead of offering a home to a resident.
The study of tourist rentals described a larger immediate effect in Osaka, where more landlords shifted vacant or low rent units into tourist accommodation. Tokyo's risk was more oriented toward future conversion, especially if residential rental revenues weaken in certain districts or tourism grows faster than regulation adapts.
Researchers used two concepts to describe the pressure. A closed rent gap measures the current effect of tourist rentals on residential housing supply. An open rent gap captures the future risk in places where changing a property's use could become attractive. In Tokyo, the open gap appeared larger in areas with strong tourist appeal and limited vacant housing.
Japan's Private Lodging Business Act took effect in 2018, setting limits on operating days and requiring management oversight. Many municipalities added ordinances to reduce neighborhood friction. Some wards have stricter rules than the national baseline, although tourism continues to test those arrangements in certain districts.
How the pressure developed over time
Tokyo's current rental squeeze brings together changes that unfolded over different periods. The March rent index marks a recent acceleration, while the figures for advertised apartments show the cumulative effect of five years of increases.
- October 1994: The historical comparison point for the pace of private sector rent growth recorded in Tokyo's 23 wards in March 2025.
- 2018: Japan's Private Lodging Business Act took effect, introducing operating day limits and management requirements for tourist accommodation.
- Over five years: Asking rents in the 23 wards rose about 7.6 percent for smaller apartments and roughly 26.1 percent for family sized homes.
- March 2025: Private sector rents in Tokyo's 23 wards rose 1.1 percent from a year earlier, the fastest pace since October 1994.
National rent components have also risen for many consecutive months. By September 5, 2025, the pressures described here included returning demand for central locations, elevated building and operating costs, and expensive condominiums keeping more households in rentals.
What a rent share above 30 percent means
The 30 percent benchmark is a rough measure rather than a complete household budget. It offers a quick way to identify pressure, but the money left after rent still has to cover each family's particular needs. The proportion of renters above that threshold is not specified.
Households facing a higher rent share tend to reduce spending on restaurants, travel, clothing and some healthcare. Saving for a home becomes slower. Parents face difficult choices over daycare, cram school and children's activities, particularly when several of those costs arrive together.
Older renters may trim maintenance spending or delay medical visits. Their budgets can also include premiums and copayments connected to health and long term care programs, leaving less room to absorb an increase in housing costs.
Japan has experienced periods of wage growth, sometimes helped by strong seasonal bonuses, and consumer spending has shown brief upturns. Inflation limits the improvement in purchasing power, meaning that a larger paycheck may buy less than a household expects after everyday prices rise.
Middle income households that do not qualify for targeted subsidies can feel that squeeze sharply. When rent is the biggest budget item after taxes, even a modest percentage increase changes what remains for the year. A bonus may provide temporary breathing room, while rent remains a payment that comes back every month.
Rent limits bring choices over protection and supply
California's Proposition 33 sought to expand local authority to cap rent increases by repealing state limits dating from the mid 1990s. The proposal illustrates a policy debate relevant to places facing affordability pressure, even though Japan's legal framework is different.
Supporters of tighter limits argue that caps can stabilize housing costs for existing tenants. Opponents warn that strict limits can reduce investment, encourage owners to convert rental properties into condominiums and shrink the supply of homes available to rent.
The Proposition 33 explanation sets out that competing logic. Tenants benefit from more predictable payments, while owners make decisions about construction and improvements based partly on the returns they expect.
For Japan, the policy choice described is how to protect current residents while preserving incentives to build and maintain rental housing. Broad caps can help sitting tenants, but slower construction and fewer upgrades are risks if owners cannot earn a return. Any discussion of limits must account for both household security and the supply of homes.
Adding homes where demand is strongest
Cambridge, Massachusetts, recently removed zoning restricted to single family homes and minimum parking requirements across the city. The decision aims to allow more homes on the same land in established neighborhoods by reducing rules that limit the number of units.
The Cambridge housing reforms offer a comparison for the supply side of the debate. Japan's zoning system differs from the American model, but adding housing where people want to live addresses the same basic pressure: too many households competing for too few suitable homes.
Options described for Japanese cities include encouraging apartment buildings of moderate height near major stations, allowing smaller average unit sizes where appropriate, and simplifying the conversion of underused offices into rental housing. Local governments can also speed approvals for student accommodation and family sized rentals in school districts where demand is already visible.
Different households need different kinds of supply. Smaller homes may suit students or people living alone, while the sharper rise in family rents points to pressure on larger dwellings. Targeted construction can respond to those needs rather than treating every apartment as interchangeable.
Tourist rental regulation is another tool. Transparent reporting, clear operating day rules and targeted enforcement in tourist corridors can reduce pressure on residential housing. Tailored local rules and better data sharing can help planners anticipate where conversions may become attractive. Coordination across city and ward boundaries would also help avoid a patchwork that moves the pressure from one neighborhood to another.
How tenants can manage the next renewal
Households have limited room to move when a lease comes up for renewal. Checking costs early can nevertheless help tenants decide whether to negotiate, stay or search elsewhere before a higher payment becomes part of the monthly budget.
A useful comparison includes rent, moving expenses and continuing bills. A cheaper apartment may involve a longer commute, while better insulation or efficient appliances may reduce electricity and gas costs. Access, space and running costs all shape the value of a home.
- Calculate rent as a share of income and aim to keep it close to 30 percent. If it rises, review other fixed costs before reducing spending on essentials.
- Use nearby comparable rents or vacancies in the building to negotiate a smaller increase or an extra month at the current rate.
- Consider moving one or two stops farther from a major transport hub to lower rent while keeping commuting time manageable.
- Look for good insulation and efficient appliances that can reduce electricity and gas bills.
- Consider searching in late summer or winter rather than during the spring rush, when prices rise.
- Ask whether key money can be reduced or spread across payments, and check promotions without fees in newer buildings. Key money is an upfront payment associated with moving into some rentals.
- For short stays, compare managed student or corporate housing, including furnished units with flexible terms, against ordinary rentals after fees are counted.
Renewal planning is especially valuable for families whose school or childcare arrangements limit where they can move. Negotiation and careful comparisons can soften an increase, even when the wider market leaves few inexpensive alternatives.
What would ease the strain on household budgets
Tokyo's central neighborhoods continue to attract households because of their rail access, schools and services. Elevated construction and operating costs limit the market's response, while expensive condominiums keep prospective buyers renting longer. Tourist accommodation remains a source of pressure in some districts despite tighter national and local regulation.
Real wage growth would help households devote a smaller share of their purchasing power to rent. Persistent inflation tempers that relief by raising the cost of other necessities at the same time. Rent affordability therefore depends on both the price of housing and what income can buy.
The pace at which new homes reach the market will shape the choices available to tenants. Targeted supply near stations, simpler approvals for family apartments and clear tourist rental rules are among the measures described to ease competition while balancing tenant protection with investment.
Landlords can invest in energy efficiency and property upkeep to support rents and maintain occupancy over time. Tenants can plan renewals early and compare the cost of space with the value of convenient access. The practical goal is housing that lets households benefit from city life without consuming the money needed for the rest of it.
Key Points
- Tokyo's 23 wards recorded private sector rent growth of 1.1 percent in March 2025, the fastest pace since October 1994.
- A growing share of renters spend more than 30 percent of income on housing, squeezing other spending and savings.
- Over five years, asking rents rose about 26.1 percent for family homes and 7.6 percent for smaller apartments.
- Studios near the University of Tokyo's Hongo campus typically ask around ¥140,000 a month.
- New condominium prices averaged about ¥81.35 million in the Tokyo metropolitan region and ¥116.32 million in the 23 wards.
- Station access, returning demand for central locations and higher property costs are contributing to rent pressure.
- Tourist rentals affect residential supply, with a larger immediate effect described in Osaka and future conversion risks in Tokyo.
- Policy choices include tenant protection, targeted housing construction and clearer tourist rental rules; households can also negotiate and compare location, fees and running costs.