More than 370,000 customers put savings behind an extra barrier
Singapore bank customers had locked more than S$30 billion against scams by June 30, 2025, with over 370,000 people using tools that prevent protected savings from being moved through ordinary digital banking. The rapid adoption follows the launch of money lock in November 2023 and comes as banks confront phishing, malicious software and criminals who manipulate people into sending money.
Contents
- More than 370,000 customers put savings behind an extra barrier
- How locked savings remain accessible to their owner
- How quickly adoption has grown
- DBS, OCBC and UOB take different approaches
- Foreign banks and digital banks broaden access
- Who uses money lock, and how much stays available?
- Two cases show how a locked balance can limit losses
- Why banks are adding checks beyond money lock
- How customers can balance protection and access
- Further changes focus on access and stronger authentication
- The Bottom Line
The stakes are substantial. The Singapore Police Force reported about S$1.1 billion in scam losses in 2024. At least S$385.6 million was lost in the first half of that year alone. Money lock gives customers a way to put part of their savings beyond the digital routes criminals commonly exploit, while leaving other money available for everyday spending.
DBS, OCBC and UOB introduced the first versions. Other major retail banks followed during 2024, with digital banks joining in 2025. The Monetary Authority of Singapore (MAS) has worked with banks to expand availability and improve how customers lock and unlock their money.
The central idea is straightforward: customers choose savings that cannot leave through online or mobile banking until an additional security step is completed. A criminal who obtains banking credentials or takes control of a phone encounters another barrier before reaching that money.
By September 3, 2025, money lock had become one part of a wider response that includes stronger authentication, transaction alerts, waiting periods and emergency kill switches. Those switches stop digital banking access while customers regain control of their accounts. The measures address different stages of a scam, from a compromised device to an attempted transfer.
How locked savings remain accessible to their owner
Money lock allows a customer to protect a chosen amount within an existing account or a linked account. Transfers, payments and digital withdrawals are blocked for the locked portion. Access requires a more secure unlocking process, usually involving a physical step that a criminal operating remotely cannot complete.
Banks use different arrangements. Some require customers to visit a branch with identity documents. Others allow unlocking at an ATM using a physical card and PIN. Several institutions add a cooling off period before the money can be withdrawn after unlocking.
Digital banks have introduced checks involving a physical card, a phone with near field communication (NFC), an additional passcode and a waiting period. NFC lets a phone read a compatible card held close to it. These checks put another requirement between control of an app and access to savings.
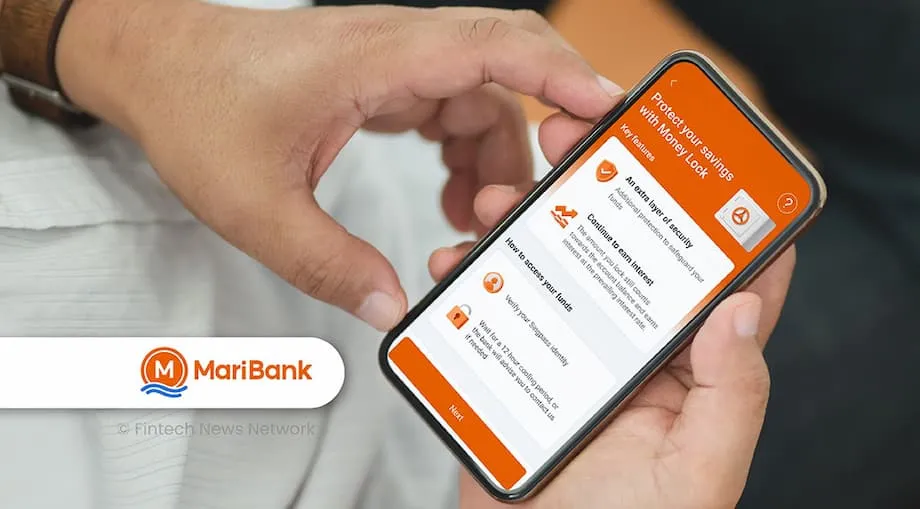
Locked money continues earning the prevailing interest rate for the account. Certain bonus interest accounts and time deposits also retain their bonus interest terms. Customers can therefore protect savings without giving up the interest available under the relevant account conditions.
MAS said early in the rollout that banks were improving the experience, including allowing money to be locked within the same account instead of requiring a separate one. In a February 2024 parliamentary reply, the regulator said locked balances had been safe from the phishing and malware schemes affecting customers. Phishing tricks people into revealing information such as passwords; malware is software that can let criminals interfere with or control a device.
MAS described the position at that time in its official reply:
To date, there have been no reports of phishing or malware scams involving funds under Money Lock.
The extra security steps, together with those early results, helped encourage adoption through 2024 and into 2025.
How quickly adoption has grown
Money lock expanded from tens of thousands of accounts soon after launch to hundreds of thousands of customers within less than two years. The milestones show both an increase in participation and a substantial rise in the amount protected.
- November 2023: DBS, OCBC and UOB launched the first money lock features.
- February 2024: More than 61,000 money lock accounts held over S$5.4 billion.
- March 2024: Locked funds reached S$6.6 billion across more than 78,000 accounts.
- End of October 2024: More than 181,000 customers had locked about S$15.8 billion.
- May 31, 2025: More than 350,000 customers had locked nearly S$28 billion.
- June 30, 2025: More than 370,000 customers had protected over S$30 billion.
The amount locked by June 2025 was almost twice the approximately S$15.8 billion recorded at the end of October 2024. Over the same period, the reported customer count rose from more than 181,000 to more than 370,000.
Bank participation widened alongside that growth. By mid 2024, the expansion included Citibank, CIMB Singapore, Bank of China Singapore, Standard Chartered, Maybank and HSBC. Standard Chartered, Maybank and HSBC had brought their features online by late 2024, in line with industry guidance. GXS Bank, MariBank and Trust Bank began introducing their versions in 2025.
DBS, OCBC and UOB take different approaches
DBS calls its tool digiVault. Early pilots required a separate vault account, but the bank later allowed customers to lock money within an existing account while continuing to earn prevailing interest. DBS has reported strong adoption across demographic groups and has expanded security controls that customers can manage themselves. Unlocking generally requires a branch visit, creating a deliberate pause before withdrawal.
OCBC integrated money lock into current accounts, savings accounts and time deposits. More than 30,000 customers locked over S$3.3 billion during the first two months after launch. The bank subsequently extended the feature to time deposits, letting customers block digital access to those deposits and unlock them at an ATM with a card and PIN or at a branch.
By late August 2025, OCBC reported nearly S$13 billion locked across more than 108,000 accounts. The bank said customers generally protected excess savings while leaving a buffer available for bills and emergencies.
UOB initially required a dedicated money lock account and said it was exploring support within existing accounts. Its customers can unlock money at ATMs. By the end of July 2025, the bank had more than 160,000 users, reflecting interest in separating daily spending from savings intended for longer periods.
UOB has also described cases in which a locked balance limited a victim's losses after the person had already begun transferring money under a scammer's influence. Such cases show the practical value of having savings protected before a scam starts.
Foreign banks and digital banks broaden access
Citibank reported more than 500 users in the first half of 2025 as it gradually introduced the feature in Singapore. CIMB Singapore said more than 6,400 customers had secured over S$310 million, while Bank of China Singapore reported more than 5,000 accounts using money lock.
Standard Chartered, Maybank and HSBC added further options for retail customers. Although unlocking procedures vary, the banks require stronger controls than the digital processes criminals seek to exploit.
Trust Bank's Trust Lock allows customers to lock individual savings pots. Withdrawing protected money requires a physical Trust card to be tapped against an NFC enabled phone and a six digit Trust Key. A mandatory wait of 12 hours follows before the money can move.
Customers without an NFC enabled phone must complete identity checks at Trust Bank's experience center. The combination of a card, a code and a delay is intended to prevent someone controlling a phone remotely from immediately transferring protected savings.
GXS Bank and MariBank also introduced money lock during 2025. Their arrival extended the protection to more customers using digital banks, alongside the options already offered by established retail institutions.
Who uses money lock, and how much stays available?
Customers across age groups have adopted the feature, with middle aged and older people accounting for most users. Early figures presented in Parliament in 2024 put customers aged 50 and above at about 44 percent of users, those between 30 and 50 at roughly 41 percent, and those under 30 at about 15 percent.
By October 2024, MAS said customers aged 30 to 49 represented the largest share, at 43 percent. Those above 50 accounted for 42 percent, while younger customers remained at 15 percent. Customers aged 50 and above tended to lock larger amounts, reflecting the use of the feature by retirees and people approaching retirement to protect accumulated savings.
OCBC's figures show how customers balance security with access. More than 70 percent of its money lock customers had protected more than S$10,000, while more than half still kept at least S$10,000 unlocked. Fewer than 1 percent locked all their funds.
Those choices leave money ready for normal expenses and unexpected needs while placing longer term savings behind additional controls. Continued interest payments make that separation possible without requiring customers to forgo the returns attached to their accounts.
Two cases show how a locked balance can limit losses
MAS highlighted in its October 2024 update that money lock had prevented larger losses in cases where victims started sending money under pressure. UOB described a customer who transferred S$700 to a suspicious account and then tried to send more.
The customer had S$50,000 protected by money lock, so the larger transfer did not happen. The interruption also gave the person time to step back and reconsider the situation.
A retiree in her mid 60s, identified as Kelly, lost about S$33,000 after clicking a fake advertisement on social media. The advertisement led her to install an app from outside an official app store. That process, called sideloading, put malware on her phone.
The criminals gained control of the device and took money from unlocked accounts. More than S$110,000 that Kelly had protected using OCBC's money lock remained secure because unlocking required a branch or ATM visit. The incident was among the earliest confirmed examples of the feature limiting losses despite attackers controlling a victim's device.
MAS's February 2024 statement about the absence of reported phishing or malware losses from locked funds described the position early in the rollout. The cases illustrate how a protected balance can reduce the money exposed during an attack and create time for a customer or bank employee to intervene.
Why banks are adding checks beyond money lock
Most scam losses in Singapore involve transfers authorised by the victim. A person may believe they are paying a seller, a romantic partner, a recruiter or an official. Some continue sending money even after bank employees warn them to stop.
Money in the unlocked portion remains available for those payments. Banks and MAS have therefore added measures intended to interrupt risky actions and draw attention to suspicious circumstances before a transfer is completed.
Over the preceding year, banks phased out SMS passwords used once for digital logins by customers who use digital tokens. The change closed a common route through which phishing criminals obtained login codes. Several banks also introduced warnings for transfers involving large amounts, prompting customers to reconsider before proceeding.
MAS has encouraged waiting periods for changes carrying greater risk, including increases in transfer limits and alterations to contact details. Such delays give banks and customers more time to respond when criminals try to prepare an account for theft.
In June 2025, banks activated stronger fraud surveillance under the Shared Responsibility Framework. The monitoring looks for rapid outflows of money and other behaviour that may signal a scam. MAS is also working with institutions on stronger authentication for online actions carrying greater risk, including a hardware security token that must be physically connected to a device for certain payments.
Singapore has strengthened police powers too. Police can freeze the accounts of suspected scam victims without their consent to prevent further losses while investigators and banks contact the person and verify what happened.
Several banking apps restrict access when they detect a suspicious app on an Android device. DBS added another control in 2025 requiring customers to switch on permission before adding a card to a mobile wallet. That extra step has already helped reduce fraud involving stored card details.
MAS leaders have said Singapore must choose security over convenience when necessary because criminals quickly exploit gaps. The approach adds pauses and checks to risky activities while seeking to keep routine banking straightforward.
How customers can balance protection and access
Customers choosing how much to lock need to consider monthly spending and an emergency buffer. The pattern at OCBC, where most customers leave some money available, illustrates how protected savings can sit alongside funds needed immediately.
Unlocking requirements also matter. A branch visit, ATM transaction or mandatory waiting period affects how quickly protected money becomes available. Customers need to know their bank's process, the time involved and any documents required before an urgent need arises.
- Lock excess savings after allowing for ordinary bills and an emergency buffer.
- Separate daily spending from savings intended for longer periods, using different accounts or savings pockets where appropriate.
- Record the bank's unlocking steps, including any branch or ATM requirements and waiting periods.
- Avoid installing apps from outside official stores. Stop and seek help if an app asks for security settings to be disabled.
- Enable transaction alerts and keep daily transfer limits low. Increase them only when necessary and lower them afterwards.
- Use the bank's kill switch when a compromise is suspected, freezing digital access while the device and account are secured.
- Be cautious when someone demands an urgent transfer. Banks and government agencies will not pressure customers to move money into accounts described as safe.
These habits address risks that remain when some money is kept accessible. Money lock protects a chosen balance, while alerts, transfer limits and prompt action help customers respond to suspicious activity involving the rest.
Further changes focus on access and stronger authentication
As of September 3, 2025, the banking industry expected adoption to keep rising as institutions improved unlocking procedures and extended support to more account types. Digital banks were developing device and card checks alongside timed delays, giving customers different ways to protect savings while retaining access when needed.
MAS had indicated that it did not plan to make money lock mandatory across all institutions. Its approach was to encourage adoption, monitor results and work with banks on stronger authentication for transactions carrying greater risk.
Trust Bank's combination of an NFC card tap, a passcode and a wait of 12 hours shows one approach. DBS's controls for adding cards to mobile wallets show another. More banks were also adopting warnings before unusual transfers or movements involving large amounts.
The practical objective is to place more checks between a compromised phone and a substantial transfer, while helping customers recognise scams and find help quickly. Money lock works alongside device checks, alerts, waiting periods and powers allowing police and banks to intervene. Its central benefit is concrete: limiting the savings immediately exposed when an attack succeeds elsewhere, and giving people time to reconsider before more money leaves.
The Bottom Line
- More than 370,000 customers had locked over S$30 billion by June 30, 2025.
- DBS, OCBC and UOB launched money lock in November 2023; other retail banks followed, with digital banks joining in 2025.
- Protected balances remain interest bearing and require additional unlocking steps, which vary by bank.
- MAS said in February 2024 that no phishing or malware losses involving locked funds had been reported at that time.
- Cases involving UOB and OCBC customers showed locked savings remaining protected after other money had been transferred or stolen.
- Customers generally retain accessible funds for spending and emergencies rather than locking every dollar.
- Warnings, device checks, stronger authentication, waiting periods and police account freezes form part of the wider response.
- MAS was encouraging adoption and monitoring outcomes rather than planning a requirement for every institution.