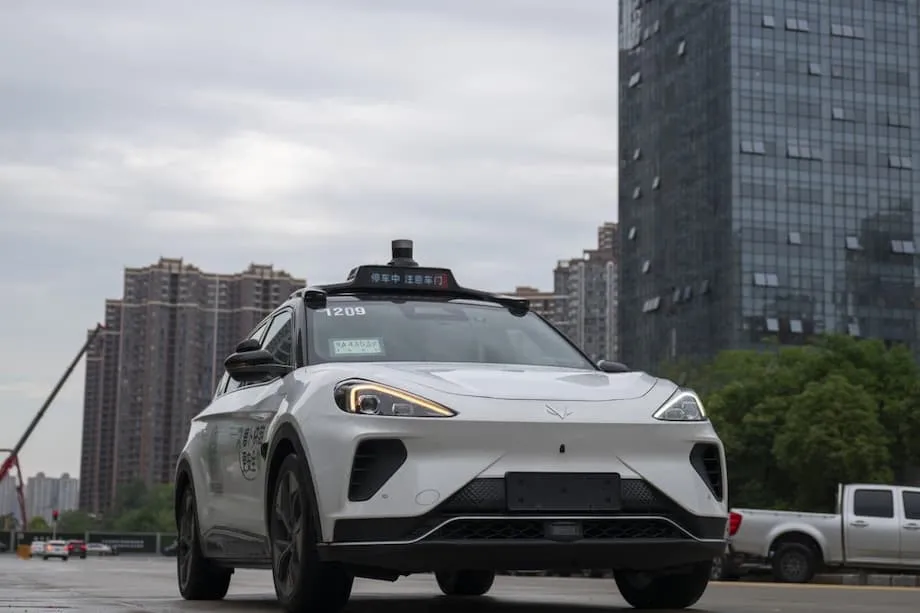
Beijing, Shanghai, Guangzhou and Shenzhen face a major transport shift
China could have 300,000 driverless taxis operating in Beijing, Shanghai, Guangzhou and Shenzhen by 2030, according to forecasts from UBS and other industry analysts. The projected expansion would bring autonomous transport into some of the country's busiest urban markets, where large populations and strong demand for rides create opportunities for fleets that can operate without a human driver.
Contents
- Beijing, Shanghai, Guangzhou and Shenzhen face a major transport shift
- Why lower vehicle costs matter
- Several forecasts describe different scales of growth
- Wuhan offers a model for expansion
- Baidu, Pony AI and Didi compete for passengers
- Chinese companies are looking beyond China
- Cheaper rides and easier access are part of the promise
- Safety and trust will shape adoption
- Global projections show a wide range of expectations
- Drivers, car owners and cities face economic changes
- The technology behind a driverless journey
- Investment depends on turning fleets into profitable services
- Key Points
As of August 31, 2025, the outlook rests on rapid advances in artificial intelligence, China's growing electric vehicle industry and government support for autonomous transport. Established automakers and technology startups are investing in a sector that could change how people book rides, how cities manage transport and how taxi operators earn money.
UBS puts the potential annual market at $183 billion by the late 2030s under a scenario in which autonomous vehicles eventually replace China's two million traditional taxis and five million cars used for ride hailing. That would mean replacing a combined seven million vehicles, a much broader transformation than the initial expansion forecast for four major cities.
Robotaxis are taxis whose driving systems handle the journey instead of a person behind the wheel. Passengers would still request a ride and travel to a destination, but the work of watching the road, steering and responding to traffic would be carried out by software using information from sensors.
China's expansion is part of a broader national strategy to bring autonomous vehicles into daily life. Government policies, regulatory frameworks and investment support that strategy. The forecasts point to a large commercial opportunity, while the pace of deployment will depend on costs, safety testing, operating permissions and public confidence.
Why lower vehicle costs matter
China's robotaxi push brings together rising labour costs, shortages of workers and demand for urban transport that can grow with the population. Consumers are increasingly open to new technology, while the government has made autonomous vehicles a priority in its smart city and innovation agendas.
Paul Gong, head of China automotive research at UBS, linked the technology to productivity in a recent report:
Given the fast development of technologies and the increasingly expensive labour cost, autonomous vehicles will be highly helpful in driving productivity.
Gong and other analysts see the falling cost of electric vehicles equipped with autonomous systems as a central reason fleets could expand. The production cost of a driverless taxi in China is expected to drop below 300,000 yuan, about $41,935. A lower purchase price would make it easier for operators to buy vehicles in large numbers.
Vehicle production costs and operating costs affect different parts of the business. The first determines how much an operator must spend to build its fleet. The second determines how much it costs to provide each journey. Robotaxi companies are seeking improvements in both, using cheaper vehicles alongside services that eliminate driver salaries and can operate around the clock.
Several forecasts describe different scales of growth
Goldman Sachs projects as many as 500,000 robotaxis across more than 10 Chinese cities by 2030, compared with the 300,000 forecast for Beijing, Shanghai, Guangzhou and Shenzhen. Goldman Sachs also sees China's fleet approaching two million vehicles by 2035.
HSBC estimates that robotaxis could account for 6% of China's taxi market, with an initial annual market size exceeding $40 billion. Barclays and MarketsandMarkets see the market reaching $45.7 billion by 2030. UBS's $183 billion estimate looks further ahead, to the late 2030s, and assumes the eventual replacement of traditional taxi and ride hailing fleets.
HSBC also estimates that logistics and delivery services involving autonomous taxis could generate $30 billion annually. E commerce and demand for delivery over the final stretch to a customer provide a second potential source of revenue beyond carrying passengers.
The main milestones in the forecasts are:
- 2025: South Korea, Germany and Japan are preparing for launches, with an emphasis on pilot programmes and integration with smart cities.
- 2030: UBS and other analysts forecast 300,000 robotaxis in China's four leading cities, while Goldman Sachs projects up to 500,000 across more than 10 cities.
- 2035: Goldman Sachs sees China's robotaxi fleet approaching two million vehicles.
- Late 2030s: UBS projects a potential annual market of $183 billion if autonomous vehicles replace China's traditional taxi and ride hailing fleets.
Wuhan offers a model for expansion
Wuhan already provides an example of driverless taxi deployment. Baidu's Apollo Go has operated more than 400 driverless vehicles there, offering a model for larger services in other cities.
Chinese authorities are working on standards, pilot programmes and infrastructure upgrades to support testing and commercial operations. Pilot zones give companies defined places to develop services, while monitoring bodies are intended to support public confidence and safe deployment.
Beijing, Shanghai, Guangzhou and Shenzhen are attractive targets because they combine dense populations with strong demand for rides. Expanding into these markets would take robotaxis beyond limited trials and make them a more substantial part of everyday transport.
Regulatory approval remains a complex process involving rigorous safety testing, data sharing and the development of new insurance models. No detailed timetable for reaching the projected 300,000 vehicles was given. The 2030 forecast sets the scale and horizon of the expected expansion, while city permissions and operating conditions will shape its progress.
Baidu, Pony AI and Didi compete for passengers
Baidu is among the leading companies in China's robotaxi sector. Its Apollo Go service is running hundreds of driverless vehicles in cities including Wuhan, and it has received approval for testing in Hong Kong.
Pony AI has begun commercial operations that charge passengers fares in leading Chinese cities. Its technical capabilities and Virtual Driver platform have helped make it a leading contender in the eyes of UBS analysts. Virtual Driver refers to the company's system for carrying out the driving work normally performed by a person.
Didi Chuxing brings a large existing base of ride hailing users to the competition. It is investing heavily in autonomous vehicle research and development and in pilot programmes. Its position connects the development of driverless vehicles with a booking service already familiar to many passengers.
Apollo is Baidu's autonomous driving division, rather than a separate competitor to Baidu. UBS identifies Apollo and Pony AI as businesses well positioned to benefit from robotaxi growth. The contest also includes established automakers and startups seeking a share of a market that could eventually be worth billions of dollars each year.
Chinese companies are looking beyond China
WeRide's partnership with Uber in the United Arab Emirates illustrates the international ambitions of Chinese robotaxi firms. Such collaborations connect autonomous driving technology with transport platforms operating outside China.
Tesla has announced plans to launch robotaxi fleets in China, although regulatory approval for its Full Self-Driving features is still pending. Its interest adds an international competitor to a field already crowded with domestic technology companies and automakers.
China's robotaxi competition therefore reaches beyond the four cities at the centre of the 300,000 vehicle forecast. Domestic companies are seeking opportunities abroad, while international companies are looking for a place in China's market. Both directions depend on securing permission to operate in the locations they target.
Cheaper rides and easier access are part of the promise
Robotaxi cost projections suggest that removing driver salaries and enabling operation around the clock could reduce the cost per mile to between $0.25 and $0.50. Rides could become 40% to 60% cheaper than traditional taxis, making price a major part of their appeal.
Most robotaxis are battery electric vehicles. Their use supports China's goals for lower emissions and cleaner urban air, while electric propulsion also offers lower operating costs and access to government incentives.
Autonomous taxis could serve places and times when taxis driven by people are scarce. That could improve transport access for older people, people with disabilities and communities with fewer existing services. The practical value would be the ability to obtain a ride when one is otherwise difficult to find.
Surveys indicate that as many as 65% of urban residents in China are willing to use robotaxis by 2030. Booking through ride sharing applications, receiving information in real time and paying digitally would make the experience familiar to people already using platforms such as Didi and Meituan.
Safety and trust will shape adoption
Autonomous vehicles are designed to reduce human error, which is responsible for most traffic accidents. Studies from companies including Waymo show far fewer crashes causing injuries compared with human drivers. Safety is therefore part of the commercial case for robotaxis as well as a requirement for their operation.
Safety incidents involving autonomous vehicles in China and abroad have also raised concerns about reliability and accountability. Operators must show that their systems can handle complex city streets, unpredictable human behaviour and adverse weather.
Public confidence will influence whether people choose a driverless ride. A serious accident attracting widespread attention could slow adoption, even as companies work to expand fleets and lower prices. Monitoring, testing and rules for insurance are central to the effort to build trust.
For passengers, safety involves a simple expectation: the vehicle must respond correctly throughout the journey. For operators and regulators, meeting that expectation requires systems that work across the varied conditions found in a city, rather than only during a straightforward trip.
Global projections show a wide range of expectations
The United States has commercial autonomous rides in selected cities, with Waymo and Cruise among the companies leading the sector. American operators face a patchwork of state regulations and continuing safety reviews. One projection puts the US fleet at about 35,000 robotaxis by 2030, far below the hundreds of thousands forecast for China.
A broader global projection gives much larger figures for the same year: an estimated 2.5 million robotaxis worldwide, with China aiming for one million and the United States for more than 500,000. The US estimates therefore range from about 35,000 to more than 500,000 vehicles, while the China figures include 300,000 in four cities, up to 500,000 across more than 10 cities and a broader projection of one million.
Europe is advancing through urban mobility programmes and emissions targets, although widespread robotaxi deployment remains at an early stage. South Korea, Germany and Japan are preparing for launches by 2025, focusing on pilots and smart city integration.
Global market forecasts put annual value at $40 billion to $45 billion by 2030, with China, the United States and Europe accounting for 80% of the total. Those worldwide revenue estimates sit alongside a China market projection of $45.7 billion for the same year. The forecasts describe substantially different expectations for the size of the business.
Adoption is projected in more than 200 cities worldwide. Expansion on that scale would require substantial changes to infrastructure and urban planning, connecting vehicle deployment with the way cities organise their streets and transport services.
Drivers, car owners and cities face economic changes
Economic models suggest robotaxis could replace 30% to 50% of journeys currently provided by ride hailing vehicles driven by people. For the traditional taxi and ride hailing industries, that would shift a substantial share of passenger demand towards autonomous fleets.
Those models also suggest traffic accidents could fall by as much as 80%, while insurance costs could decline by 50% to 70%. Fleet utilisation could exceed 70%, compared with 40% for traditional taxis. Utilisation describes how much a fleet is being used; greater use allows an operator to earn revenue from its vehicles more often.
Integration with public transport and shared mobility services could reduce the number of vehicles on the road by 30% and carbon dioxide emissions by 40%. The proposed benefit for cities is a combination of less congestion and lower emissions, alongside transport services that people can request when needed.
Mobility-as-a-Service, or MaaS, describes the shift towards flexible transport available on demand rather than relying on a privately owned car. That shift is already changing how people think about transport in many urban areas. Robotaxis are expected to contribute to lower personal car ownership and changes in city landscapes as shared services expand.
The technology behind a driverless journey
Artificial intelligence and machine learning process information from cameras, sensors and maps so a robotaxi can make driving decisions in real time. The system must combine what it detects around the vehicle with the route it is trying to follow.
LiDAR, short for Light Detection and Ranging, creates detailed maps of the surroundings in three dimensions. Radar detects objects and measures their speed, including in poor visibility. Together with cameras, these sensors give the driving system information about the road and nearby activity.
Vehicle-to-everything communication, known as V2X, allows a robotaxi to exchange information with traffic lights, other vehicles and infrastructure. That communication is intended to support safer and more coordinated driving.
Electric propulsion supplies the movement, while battery improvements help the economics of operating electric fleets. Continuing advances in artificial intelligence, sensor fusion and batteries are driving down costs and improving performance. Sensor fusion means combining information from different sensors into a usable view of the surroundings.
Companies are also investing in cybersecurity, data privacy and systems for remote operation. These areas address risks created by vehicles that depend on software, information and connections alongside their physical driving equipment.
Investment depends on turning fleets into profitable services
Automakers, technology giants, venture capital investors and public markets are directing money towards robotaxis. UBS analyst Paul Gong recommends stocks such as Pony AI and Apollo as well positioned to capture growth in China's potential $183 billion market. Both have demonstrated strong technical capabilities and are expanding commercial operations in major cities.
Investment opportunities extend beyond manufacturing vehicles. Sensors, software, mapping and fleet management are also part of the business. Suppliers of LiDAR, artificial intelligence chips and cloud computing services are expected to benefit as robotaxi networks grow.
Profitability depends on keeping vehicles in use, reducing costs and competing successfully with domestic and international operators. Regulatory changes, technical difficulties and public acceptance remain risks for investors. The central commercial task is to turn expanding fleets into services that passengers use regularly and that earn enough to cover their costs.
Key Points
- UBS and other analysts forecast 300,000 driverless taxis in Beijing, Shanghai, Guangzhou and Shenzhen by 2030.
- Goldman Sachs projects up to 500,000 robotaxis across more than 10 Chinese cities by 2030 and nearly two million by 2035.
- UBS sees a potential annual market of $183 billion by the late 2030s if autonomous vehicles replace China's seven million traditional taxi and ride hailing vehicles.
- Production costs are expected to fall below 300,000 yuan, about $41,935, per driverless taxi.
- Baidu's Apollo Go, Pony AI and Didi are major participants; WeRide is working with Uber in the UAE, and Tesla seeks entry into China.
- Lower prices, improved access and fewer emissions are projected benefits, while safety, insurance, regulation and public trust will shape deployment.
- Global fleet and revenue forecasts vary widely, including US estimates of about 35,000 and more than 500,000 robotaxis by 2030.