A valuable cargo at the centre of a global contest
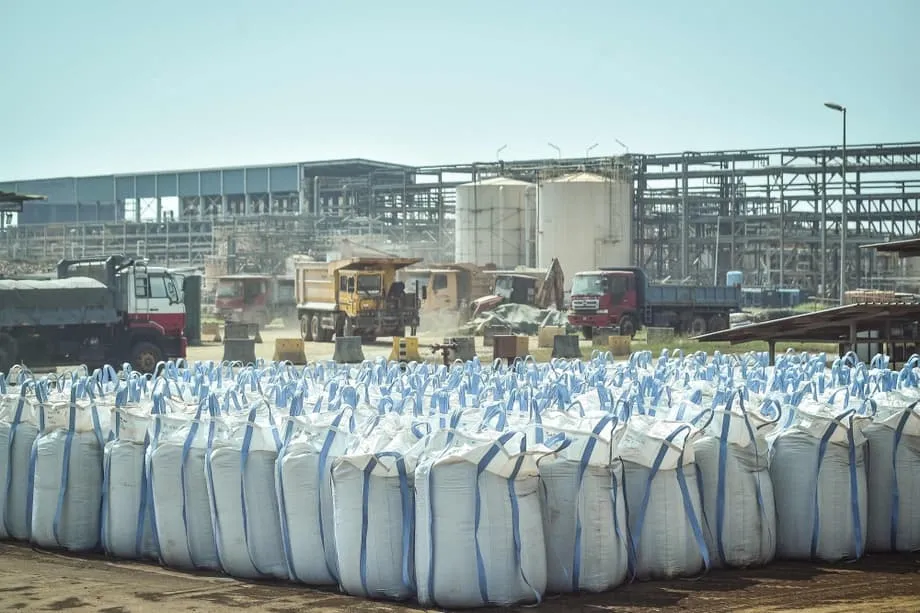
At Gebeng, near the coastal city of Kuantan in eastern Malaysia, workers pack rare earth materials into industrial bags worth about US$100,000 each, or RM395,534.24. The valuable mixture is neodymium-praseodymium, known as NdPr, a key ingredient in powerful magnets used in smartphones, electric vehicles, fighter jets and wind turbines.
Contents
- A valuable cargo at the centre of a global contest
- Why China's processing power matters
- Heavy rare earth production reaches new milestones
- The dates shaping the plant's next phase
- Japan secures a lasting supply arrangement
- Malaysia balances competing partnerships
- From Malaysian deposits to finished magnets
- A decade of operation with a waste deadline
- Environmental risks extend beyond Gebeng
- Lynas plans more capacity and new uses
- The Bottom Line
The bags leave a facility operated by Australia's Lynas Rare Earths, the world's largest single rare earth processing plant outside China. Since 2012, the Lynas Advanced Materials Plant, or LAMP, has processed material from the company's Mount Weld mine in Western Australia. Its refined powders travel through Port Klang to Japan, where manufacturers turn them into magnets for industries including electronics and aerospace.
As of April 23, 2026, the Malaysian operation sits at the intersection of commercial competition, national security and environmental scrutiny. China controls approximately 90 percent of global rare earth processing, while Lynas holds roughly 10 percent of the market. That leaves the Gebeng plant playing an unusually large role in efforts to secure supplies outside China.
Lynas currently handles 11 of the 17 rare earth elements and is expanding its ability to separate more of them. Backed by Australian mining magnate Gina Rinehart and posting record quarterly revenues, the company is seeking to turn its position into a broader alternative supply chain.
The plant's importance reaches beyond the price of any individual bag. Manufacturers need reliable access to particular rare earth ingredients, in the right form, to make equipment that works as designed. A shortage of a small but essential ingredient can disrupt production of a much more valuable finished product.
Malaysia has renewed the plant's operating licence for 10 years, while requiring an end to activities that produce radioactive waste within five years. Lynas therefore faces two demands at once: expanding production of strategically important materials and meeting a new environmental timetable.
Why China's processing power matters
China's dominance rests on its ability to process rare earths, not simply on having deposits in the ground. Processing separates elements from a mixture and prepares materials that manufacturers can use. Lynas's Malaysian facility provides one of the few viable alternatives to that Chinese industrial capacity.
Amanda Lacaze, chief executive officer of Lynas, said during a press visit to the chemical plant that China's position reflects sustained industrial planning:
China has built its success on executing a clear industrial plan.
Lacaze said building competing capacity would require a similarly sustained commitment:
Pushing against Chinese dominance will take discipline, focus and clear planning.
Beijing demonstrated the reach of its control in October 2025, when restrictions on rare earth exports unsettled markets and disrupted supply chains. A temporary agreement with Washington followed. Rare earth supply security remains a central diplomatic issue ahead of another summit between US President Donald Trump and Chinese President Xi Jinping scheduled for mid-May.
For manufacturers, an alternative supplier can reduce exposure to restrictions affecting a single country. For governments, access to minerals used in defence equipment makes the same supply problem a matter of national security. The Gebeng facility serves both concerns, supplying industries that range from consumer electronics to advanced military systems.
Heavy rare earth production reaches new milestones
Lynas became the first company outside China to produce heavy rare earth oxides on a commercial scale in May 2025, when it produced dysprosium. Terbium followed in June 2025, and samarium in March 2026. These milestones opened an alternative source of materials whose commercial processing had been concentrated in China.
Heavy rare earths are especially important in equipment exposed to high temperatures, including electric vehicle drivetrains and advanced defence systems. Powerful neodymium-iron-boron magnets, often called NdFeB magnets, need small amounts of dysprosium and terbium to retain their magnetic properties under the heat inside vehicle motors. Without those additions, thermal stress can make the magnets unsuitable for advanced drivetrains.
Lynas's new separation circuit was commissioned with a $25 million investment and can process up to 1,500 tonnes of mixed heavy rare earth compounds a year. Its capacity includes SEGH concentrate, a mixture containing samarium, europium, gadolinium and holmium.
Further expansion is intended to include yttrium and lutetium, elements used in medical imaging, cancer therapy and solid-state lasers. The company's plan therefore extends beyond the ingredients most closely associated with vehicle magnets.
Pol Le Roux, chief operating officer of Lynas, described the progression from proving the process to designing a wider separation operation:
The first step was to demonstrate that we are able to extract heavy rares.
Le Roux set out the production milestones and the next engineering task:
We demonstrated that with dysprosium in May last year, terbium in June and samarium last month. We started detailed engineering of a full heavy rare separation that will provide us the capability to extract any rare earths demanded by the market.
Lynas expects to have its full suite of extraction capabilities at Gebeng by late 2027. The expansion gives automotive and defence manufacturers outside China another potential source of ingredients that had previously been restricted.
The dates shaping the plant's next phase
Gebeng's development spans years of industrial investment, public opposition and changing trade relationships. Its recent breakthroughs come alongside a licence renewal that sets a deadline for changing how radioactive residues are produced and managed.
The main milestones show how quickly the plant's commercial role has widened, even as its environmental obligations have become more demanding:
- 2007: Construction began, with environmental opposition continuing through the plant's development.
- 2012: The facility began processing material from Mount Weld in Western Australia.
- May and June 2025: Lynas produced dysprosium and then terbium outside China on a commercial scale.
- October 2025: China restricted rare earth exports, Malaysia signed a cooperation memorandum with the United States, and Sojitz began importing heavy rare earths refined by Lynas.
- Early 2026: Lynas extended its supply agreement with Japan Australia Rare Earths through 2038.
- March 2026: Lynas produced samarium and Malaysia renewed its operating licence for 10 years.
- Mid-May 2026: Trump and Xi are scheduled to meet again.
- Late 2027: Lynas expects its full suite of extraction capabilities to be available at Gebeng.
- Within five years of the March 2026 licence renewal: Lynas must stop all activities that produce radioactive waste.
The timetable puts the planned processing expansion ahead of the waste production deadline. Both commitments will shape the operation's next phase.
Japan secures a lasting supply arrangement
Japan's relationship with Lynas grew especially close after the 2010 rare earth dispute between China and Japan. Beijing temporarily halted shipments during territorial tensions, exposing Japan's dependence on a supply chain it could not fully control.
In early 2026, Lynas extended its agreement with Japan Australia Rare Earths, or JARE, through 2038. The arrangement commits 5,000 tonnes of NdPr annually and 75 percent of all Lynas heavy rare earth oxides to Japanese industry.
The agreement includes a market linked floor price of US$110 per kilogram for NdPr. A floor price sets a minimum under the pricing arrangement, giving the producer a measure of revenue security when market prices weaken. The deal also includes mechanisms to share gains when prices exceed US$150 per kilogram.
Those two thresholds are US$40 per kilogram apart. They show how the arrangement combines protection at the lower end with a way to share the benefit of stronger prices, rather than relying solely on whatever price the market offers at a particular moment.
Sojitz Corporation, the Japanese trading house, began importing heavy rare earths refined by Lynas in October 2025. It aims to cover approximately 30 percent of Japan's total demand.
The journey from Australian mine to Malaysian processing plant and Japanese magnet factory shows why rare earth security depends on several connected industries. Extracting ore is one step. Separating the elements and turning them into usable magnets are further steps, each requiring its own facilities and expertise.
Malaysia balances competing partnerships
Malaysia is hosting the supply chain backed by Australian and Japanese interests while also discussing Chinese support for its own rare earth industry. During Xi Jinping's April visit to Malaysia, he reportedly proposed technical assistance for rare earth processing.
Khazanah Nasional, Malaysia's strategic investment fund, has also been in discussions with a Chinese state firm about a possible processing partnership. Those discussions reflect Malaysia's need for technology as it seeks to develop domestic resources, rather than limiting its role to processing Australian material at Gebeng.
The United States has courted Malaysia as part of efforts to reduce dependence on Chinese supply chains. In October 2025, Prime Minister Anwar Ibrahim signed a memorandum of understanding with Trump ensuring that no restrictions would be placed on rare earth exports to the United States.
Malaysia's position is therefore more complex than choosing one foreign partner. Lynas supports an alternative to Chinese processing, while Chinese assistance could help develop Malaysian deposits. The US agreement adds another relationship to that mix.
The country could become a relatively neutral but indispensable part of supply chains increasingly divided by geopolitical tensions. Its ability to occupy that position depends on building industrial capacity while managing the commitments it makes to different partners.
From Malaysian deposits to finished magnets
Malaysia has an estimated 16.2 million tonnes of rare earth deposits valued at approximately RM747.2 billion, or US$175 billion. The country nevertheless lacks the advanced technology needed to mine and process those resources at scale.
A 2024 reconnaissance study by the Department of Mineral and Geoscience identified substantial ionic adsorption clay deposits across Peninsular Malaysia. These are deposits in which rare earths are held in clay, with geology potentially similar to the deposits in China's southern provinces.
Malaysia currently has only one legal domestic mining project, a partnership between the Perak state government and Chinese state owned enterprise Chinalco. The National Mineral Industry Transformation Plan 2021-2030 aims to build a "mine to magnet" ecosystem, targeting annual rare earth output of 30,000 tonnes by 2030 and the creation of 4,000 jobs.
The phrase describes a complete industrial chain: mining the resource, separating its ingredients and manufacturing magnets rather than stopping at the sale of raw material. Malaysia's targets require major infrastructure investment, dependable supplies of chemical reagents and partnerships with manufacturers further along that chain.
Industry veterans point out that China took decades to build its rare earth ecosystem. Malaysia's 2030 ambitions may therefore be optimistic without substantial foreign technology partnerships.
Swiss company Bomatec and Japanese company Shin-Etsu already operate magnet manufacturing facilities in Malaysia. Their presence provides parts of the industrial chain, although the links needed for the planned domestic ecosystem remain fragmented compared with China's vertically integrated supply chains.
Malaysia imposed a moratorium on rare earth exports in December 2023, following an approach similar to Indonesia's policy on nickel. The aim was to retain processing and more of the resource's value within the country.
Tengku Zafrul, minister of investment, trade and industry, defended the US cooperation agreement against accusations that it surrendered sovereignty. He explained the purpose of Malaysia's export policy:
Malaysia is not imposing a permanent ban on rare earth exports; rather, it is to prevent the export of unprocessed, low-value raw materials, so that more added value remains within the country.
The policy makes technology access central to Malaysia's plans. Keeping raw material at home can support domestic industry only when the country has the facilities and skills to process it into more valuable products.
A decade of operation with a waste deadline
Malaysia's Department of Atomic Energy renewed Lynas's operating licence for 10 years in March 2026, with new conditions governing radioactive waste. Within five years of the renewal date, the company must stop all activities that produce such waste.
Lynas must also treat existing water leach purification residues so that they are no longer radioactive. No new permanent disposal facilities will be approved after the transition period. The renewal permits continued operation while requiring changes to both future waste production and the treatment of existing residues.
Environmental opposition has followed the facility since construction began in 2007. Local residents and activists have questioned its waste management arrangements and asked why the plant was not built in Australia if its processes are safe.
The Save Malaysia Stop Lynas campaign has sustained protests against the operation. Community concerns draw on the experience of an earlier rare earth refinery near Ipoh operated by Mitsubishi, which closed in 1992 amid health complaints and contamination problems that required years of cleanup.
Lynas says its by-products are non-toxic and safe. The company describes the materials as magnesium-rich gypsum and iron phosphate containing only very low levels of naturally occurring radioactive material. It says permanent disposal facilities are designed to prevent environmental harm.
The International Atomic Energy Agency assessed the Kuantan plant and judged it to meet all safety standards, describing the facility as state-of-the-art and well engineered. Local trust remains a central issue, with communities pointing to Western Australia's refusal to accept the waste back despite its low radioactivity.
The new licence conditions bring those concerns into the plant's operating timetable. Lynas has permission to continue processing, but its existing approach to producing and managing radioactive residues must change within the specified period.
Environmental risks extend beyond Gebeng
Malaysia's domestic mining ambitions face environmental risks of their own. Illegal mining operations in neighbouring regions have polluted tributaries of the Mekong with arsenic and cadmium, illustrating the consequences of inadequate regulation.
Malaysia is likely to develop its clay deposits using in-situ leaching methods similar to those used in southern China. This means using chemicals within the deposit to release the minerals, rather than relying solely on removing material for treatment elsewhere.
Environmental groups warn that injecting chemicals into sensitive ecosystems could cause new contamination crises. Opposition from activists and fishermen could delay permits or halt future projects.
Gebeng's operation and Malaysia's domestic deposits present connected but different challenges. Lynas is processing ore from Australia at an established facility, while developing Malaysian resources would introduce mining and chemical treatment into additional locations. The country's industrial plans depend on managing both sets of risks.
Lynas plans more capacity and new uses
Lynas plans to invest RM500 million, approximately US$118 million, in a new heavy rare earth separation plant with annual capacity of 5,000 tonnes. This is a further expansion beyond the separation circuit capable of processing up to 1,500 tonnes of mixed heavy rare earth compounds a year.
The company is also exploring uses for rare earths as catalysts in the hydrogen supply chain, particularly in ammonia cracking during gas transport over long distances. In this process, a catalyst helps the chemical reaction used to release hydrogen from ammonia.
Le Roux expects these applications to become a substantial business area over the next decade:
In 10 years from now, I expect this to be a substantial part of the business.
The research points to ambitions beyond producing oxides for existing customers. Lynas is seeking new industrial uses while expanding the range of elements it can separate at Gebeng.
Malaysia's rare earth position now rests on several tasks moving together: expanding an established processing operation, developing domestic deposits, securing foreign technology and meeting environmental requirements. The RM395,000 bags leaving Gebeng are the visible product of that effort, but the longer contest is about building a dependable chain from mineral resources to finished industrial materials.
The Bottom Line
- Lynas operates the world's largest single rare earth processing facility outside China at Gebeng, near Kuantan, using material from Australia's Mount Weld mine.
- Each industrial bag of NdPr is worth about US$100,000, or RM395,534.24, and the refined material travels through Port Klang to Japan for magnet manufacturing.
- China controls approximately 90 percent of global rare earth processing, while Lynas holds roughly 10 percent of the market.
- Lynas produced dysprosium in May 2025, terbium in June 2025 and samarium in March 2026, with wider extraction capabilities expected by late 2027.
- The JARE agreement runs through 2038 and commits 5,000 tonnes of NdPr annually and 75 percent of Lynas heavy rare earth oxides to Japanese industry.
- Malaysia's March 2026 licence renewal lasts 10 years, but Lynas must stop activities producing radioactive waste within five years and treat existing radioactive residues.
- Malaysia has an estimated 16.2 million tonnes of rare earth deposits and targets annual output of 30,000 tonnes and 4,000 jobs by 2030.
- Lynas plans a new separation plant costing RM500 million, while Malaysia pursues foreign partnerships and faces technology, environmental and permitting challenges.