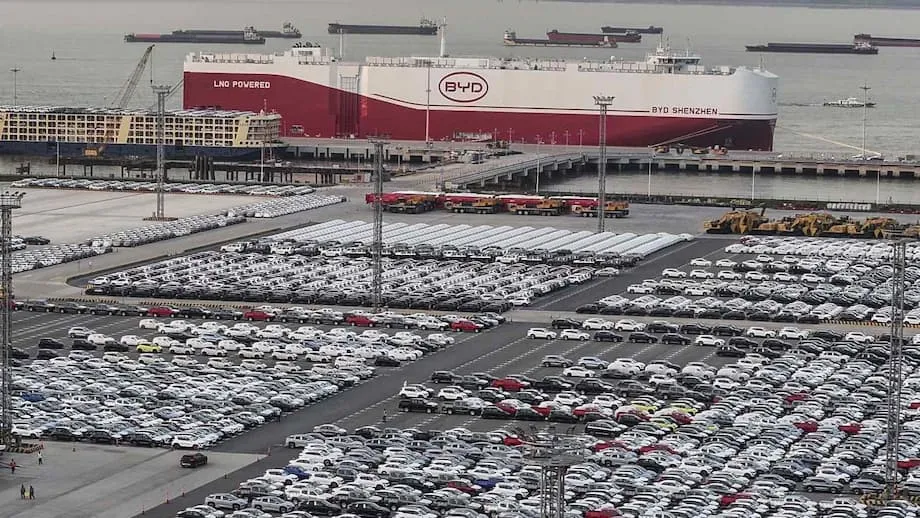
Asia takes a larger role in a more selective expansion
China's overseas investment in electric vehicles and batteries is shifting toward Asia after reaching a high in 2023 and beginning to slow in 2024. As of October 2, 2025, companies are putting greater weight on battery materials, components and vehicle assembly, while becoming more cautious about expensive acquisitions and upstream resource projects.
Contents
- Asia takes a larger role in a more selective expansion
- Pressure at home changes the investment calculation
- Western trade barriers redirect production plans
- Trade agreements and incentives strengthen Asia's appeal
- Malaysia, Thailand, Vietnam and Indonesia take different roles
- New factories replace some of the appetite for takeovers
- Battery materials sit at the center of the strategy
- Jobs are an immediate gain, skills take more work
- Governments want deeper local roots
- Selective growth is the outlook through 2027
- What to Know
Malaysia illustrates the change. BYD plans to open its first plant in the country in 2026, while Leapmotor has partnered with Stellantis to begin local assembly before the end of 2025. Thailand, Vietnam and Indonesia are also drawing activity as Chinese manufacturers seek production locations close to home and access to regional customers.
The shift follows five years of rapid international expansion. Chinese carmakers now face fierce price competition at home, tighter financing and tougher barriers in Western markets. Those pressures make the cost, timing and location of each overseas project more important.
Industry data based on announced transactions puts 2023 at the peak of Chinese global investment across the EV value chain. Battery projects dominated that spending, and most were new factories rather than takeovers. Announced transactions describe investment plans, with construction and production following their own schedules.
North America is receiving less attention, while Europe, the Middle East and especially Asia account for more of the geographical focus. Latin America remains important for resources and some vehicle assembly. Within Asia, projects are spreading across Southeast Asia, parts of South Asia and selected manufacturing hubs in East Asia.
For host countries, the change creates opportunities for factories, employment and exports. The lasting gains will depend on what those plants actually do: assembling imported parts, making batteries, developing local suppliers or building more advanced manufacturing skills.
Pressure at home changes the investment calculation
China's prolonged economic slowdown, high debt and weaker consumer confidence are weighing on its car industry. Manufacturers have cut prices to keep sales moving, reducing the money they earn from each vehicle and making new factory commitments harder to justify.
BYD, China's largest EV manufacturer, reported that profit fell by nearly a third from a year earlier in the second quarter. The decline reversed years of steady quarterly gains. A more crowded domestic market and slower sales growth are pushing the company to balance overseas expansion with cost control.
Overseas capital expenditure, the money spent on assets such as factories and production equipment, competes with other demands on company finances. When profits fall, manufacturers have stronger reasons to choose projects that can start producing sooner or expand in stages.
Financing has become more difficult as well. Venture funding across Asia fell to its lowest level in a decade in 2024, with China taking much of the hit. Newer EV brands that depend on investor funding are adjusting their expansion to the periods when money is available.
Companies are consequently looking more closely at smaller sites, faster returns and incentives from host governments. Battery and component projects still require substantial spending, but they can offer a more manageable commitment than buying a large business or developing a resource project with a long construction schedule.
Western trade barriers redirect production plans
The United States has tightened rules governing EV tax credits for vehicles with Chinese content and remains wary of Chinese investment in sensitive supply chains. Eligibility is tied to where critical minerals are processed and battery components are produced, limiting access to generous credits for vehicles with Chinese content.
Europe has increased scrutiny of support programs for Chinese automakers and is moving toward higher tariffs. Higher duties raise the cost of exporting cars made in China, changing the balance between shipping vehicles from home and producing closer to customers.
Chinese manufacturers still see Europe and the United States as large markets. Their response is to select locations where trade rules are clearer and requirements for local production are achievable. Suppliers are also building in countries with trade agreements with the European Union or the United States, then shipping products onward.
Mexico could attract more component investment because of its links with the United States and Canada. Companies nevertheless face political scrutiny and must consider possible conflict with US policy. North America continues to receive occasional investment, often from suppliers, but those projects can be volatile.
Asia offers a different combination of proximity, established manufacturing networks and governments seeking EV investment. That makes it an attractive location for companies trying to grow while keeping financial and policy risks under control.
Trade agreements and incentives strengthen Asia's appeal
The Regional Comprehensive Economic Partnership, known as RCEP, supports the regional production strategy by cutting tariffs within its large trading bloc and simplifying rules of origin. Those rules determine where a product counts as having been made when businesses seek preferential trade treatment.
Factories near China can also use shorter and simpler logistics routes. Thailand and Malaysia already have manufacturing ecosystems that can support new production, while selected East Asian hubs offer established infrastructure and production standards suited to rapid expansion.
Southeast Asian governments see electric vehicles as a source of industrial growth. Their support includes land, tax relief, grants, tax holidays, accelerated depreciation and direct assistance for strategic projects. Accelerated depreciation lets businesses account for the cost of equipment more quickly for tax purposes.
Such measures can make a meaningful difference to projects of moderate size that need predictable returns. Governments also use incentives to encourage suppliers to locate near vehicle and battery factories, aiming to create connected production networks rather than isolated assembly sites.
Asian markets offer growth opportunities alongside those manufacturing advantages. Chinese brands are increasing exports where tariffs remain manageable and charging infrastructure is improving, then supporting those sales with selected local assembly lines.
Malaysia, Thailand, Vietnam and Indonesia take different roles
Malaysia's planned factories show how vehicle assembly is spreading within Southeast Asia. BYD's first Malaysian plant is scheduled for 2026. Leapmotor and Stellantis plan to begin local assembly before the end of 2025. Both projects point toward a production base serving domestic buyers and regional export markets, with opportunities for suppliers to gather around it.
Thailand remains a major destination for EV assembly and battery projects. Its long history in vehicle manufacturing gives investors an existing industrial base, while incentives for new energy vehicles support the move into electric production.
Vietnam continues to attract manufacturing intended for export. It is also among the countries that have seen improvement in product complexity, meaning movement toward goods that require more sophisticated production capabilities. Progress across Southeast Asia in turning investment into greater knowledge and technical skill remains uneven.
Indonesia's position rests heavily on nickel refining and battery materials, supported by its resource wealth. Its experience also shows how factory prospects depend on demand: the electric two wheeler market shrank in 2025 after subsidies ended.
Subsidies reduce the cost consumers pay, so their withdrawal can make an early EV market harder to sustain. For companies considering more production lines, changes in purchase support can alter expectations about how many vehicles they will sell.
The main dates in the investment shift are:
- 2023: Announced Chinese overseas EV investment reached a high, with battery projects dominating spending.
- 2024: Investment began to moderate, while venture funding across Asia fell to its lowest level in a decade.
- 2025: Leapmotor and Stellantis plan to begin Malaysian assembly before the end of the year.
- 2026: BYD plans to open its first Malaysian plant.
- 2025 to 2027: The outlook is for steady but selective investment, concentrated on battery production and final assembly in Asia.
New factories replace some of the appetite for takeovers
Chinese companies increasingly favor greenfield investment, which means building a new facility rather than buying an existing business. Most current projects are new plants for batteries, cathode or anode materials, and final vehicle assembly.
Acquiring an automaker or resource asset can be expensive and attract political resistance. A new factory gives the investor control over its design, makes it easier to match local content rules and allows spending to be divided into phases as demand develops.
Local content requirements specify how much production or value must come from the host market. Assembly plants help brands meet those thresholds by bringing in raw materials, partly finished goods or vehicle kits, completing more work locally and supplying nearby customers.
Some manufacturers begin with semi knocked down or completely knocked down kits. These are vehicles shipped in partly assembled form or as sets of components for assembly at the destination. Companies can move toward fuller production as local supplier networks mature.
Projects in Malaysia and Thailand use this approach. It allows manufacturers to enter a market without immediately committing to every stage of vehicle production, while fitting government plans to develop skilled employment and domestic suppliers.
Battery and component production can also support expansion without requiring an entire vehicle factory in every market. Manufacturers can place particular stages of production where costs, customers and trade rules make the strongest case.
Battery materials sit at the center of the strategy
Battery investment extends beyond the factories that assemble finished packs. It includes cathode and anode materials, cell manufacturing and pack assembly. Cathodes and anodes are parts inside a battery cell; cells are then combined into packs used by vehicles.
These activities occupy the middle of the supply chain, between extracting raw resources and producing finished vehicles. They require considerable capital, but offer a different risk profile from mining and can fit into existing industrial clusters.
A cathode or anode plant can supply several carmakers rather than depend on one brand's vehicle sales. That spreads commercial risk and helps host governments secure more value from local manufacturing. Some projects bring materials suppliers alongside cell producers, creating a connected group of businesses.
This pattern is visible in Southeast Asia and selected East Asian markets with infrastructure and production standards ready for expansion. Plants located near vehicle factories reduce shipping costs and help customers meet local content requirements.
Major battery companies are expanding abroad to serve global clients, with cell factories and pack assembly operations following demand. Cathode and anode suppliers are taking a similar route. Once several stages operate close together, host markets gain a more established network of customers and suppliers.
Mining investment has cooled from the previous cycle as lithium prices have fallen from their peaks. Resource projects also take longer to develop and carry political risks. Latin America remains important for lithium and copper, and Chinese companies retain stakes in mines and refining operations there.
For manufacturers seeking market share and compliance with local production rules in the near term, Asian battery materials plants and assembly operations offer a quicker route. BYD is combining local assembly in Southeast Asia and Latin America with efforts to manage costs.
Jobs are an immediate gain, skills take more work
Asian governments expect EV investment to generate construction work, factory jobs and demand for services around industrial sites. Battery and vehicle projects can also create export opportunities, connect domestic businesses to global production and reduce reliance on imported combustion engines.
The depth of those benefits depends on the work carried out locally. A project that processes resources mainly for shipment back to China offers fewer opportunities to develop skills and suppliers than a broader manufacturing operation.
Vehicle assembly, battery cell production and pack manufacturing can build more capabilities, particularly when investors and governments support workforce training and supplier development. Local firms need opportunities to become part of the production process, rather than operate only around its edges.
Southeast Asia has seen gains in manufacturing output and employment, but progress toward more advanced activity varies. Vietnam has improved product complexity, while some other countries have struggled to turn foreign investment into production that requires greater knowledge.
Stable policy helps both investors and domestic businesses plan. Indonesia's decline in electric two wheeler sales after subsidy withdrawal shows how sensitive a developing market can be to changes in support. Clear incentive schedules, transparent local content rules and training programs make longer planning more practical.
Governments want deeper local roots
Host countries are raising expectations alongside their investment incentives. Local content requirements are increasing, while standards for battery recycling and waste are becoming stricter. Some markets are also expanding investment screening to address national security concerns.
Chinese companies are responding through local partnerships, joint ventures and research centers. These arrangements can connect new factories more closely with the host economy and help companies operate within changing industrial rules.
Governments want suppliers to locate near major plants and participate in more advanced stages of production. Companies want predictable conditions and enough demand to justify their spending. The resulting network is becoming more complex, with production spread across several countries rather than concentrated in a single overseas operation.
Policy consistency remains central to that balance. Abrupt changes in incentives or standards can weaken investor confidence, while clear requirements give manufacturers and local suppliers a firmer basis for committing money and training workers.
Selective growth is the outlook through 2027
The outlook for 2025 to 2027 is for steady but selective Chinese investment across Asia's EV supply chain. Battery materials, cells, packs and final assembly are expected to attract the most activity where incentives are clear and demand is growing.
Companies will continue watching policy changes in Europe and the United States. Most new announcements are expected to favor projects that can move more quickly in Asia, with greenfield construction remaining attractive because spending can be phased and factories designed around local rules.
Domestic competition could squeeze profits further, tighter credit could restrict financing, and policy reversals could unsettle emerging markets. Those risks make the pace of expansion dependent on company finances as well as host country support.
Asia nevertheless combines nearby supply networks, growing consumer markets and locations suited to regional trade. China's overseas EV strategy is becoming more selective about how much to spend and which stages of production to build, with Asia positioned as its main manufacturing focus.
What to Know
- Chinese overseas EV investment peaked in 2023 and began moderating in 2024.
- Price competition, weaker profits and tighter financing are encouraging more cautious factory spending.
- Western tariffs, tax credit rules and investment scrutiny are redirecting production plans.
- Asia offers proximity to China, RCEP trade preferences and government incentives.
- Leapmotor and Stellantis plan Malaysian assembly in 2025; BYD plans its first Malaysian plant in 2026.
- New factories for battery materials, cells, packs and vehicle assembly are favored over some acquisitions and mining commitments.
- Host countries can gain jobs and exports, with deeper industrial benefits depending on training, suppliers and consistent policy.
- The outlook through 2027 is for selective expansion, centered on Asia and exposed to financial and policy risks.