A currency rally powered by bonds and changing US rates
Malaysia's ringgit has gained more than 8 percent in 2025 and, as of December 8, is hovering near its strongest level against the US dollar in four years. Foreign investors bought an estimated US$1.3 billion of Malaysian government and corporate bonds in November, the largest monthly inflow since May. Some market forecasts point to the currency strengthening through 4.10 ringgit per dollar if the rally continues.
Contents
- A currency rally powered by bonds and changing US rates
- Why the gap between US and Malaysian rates matters
- Bond inflows lead, while stocks tell a different story
- Fiscal policy gives investors a domestic reason for confidence
- Exports are recovering, but investment flows move faster
- Investment and productivity determine how durable the gains become
- What could interrupt the rally?
- Households, exporters and investors feel different effects
- The milestones behind the move
- What the outlook suggests for 2026
- Key Points
Slower US inflation, expectations of further Federal Reserve interest rate cuts and improving global risk appetite have helped weaken the dollar. Malaysia's steady economic growth, moderating inflation and firm policy footing have given investors domestic reasons to buy ringgit assets.
The exchange rate describes how many ringgit are needed to buy a dollar. A move toward a lower number means the ringgit is stronger: households and businesses need fewer ringgit to pay the same dollar bill. For foreign investors holding Malaysian assets without protection against currency changes, that appreciation can also increase returns when they convert their money back into dollars.
Malaysian bonds have been central to the latest advance. Demand has benefited from a narrower fiscal deficit, stable policy rates and a view that valuations remain attractive after the currency's weakness between 2021 and 2023. Ringgit fixed income, investments that pay interest, has been among the region's better performers for international investors this year.
Trade has improved as global demand gradually recovers, but the latest currency gains appear more closely connected to investment flows and expectations than to merchandise exports alone. Foreign purchases of local shares have been more uneven. Understanding the rally therefore requires looking separately at bonds, stocks, trade and the domestic policies supporting confidence.
Why the gap between US and Malaysian rates matters
Interest rate differences and global willingness to take investment risks explain much of the ringgit's recent movement. In episodes like this, those external forces often account for 70 to 80 percent of movements over the near term. Domestic conditions help determine how well Malaysia benefits when international money starts moving.
Exchange rates are prices set by demand and supply. When US interest rates fall relative to Malaysian rates, the interest available on ringgit assets becomes more appealing by comparison. Investors buying Malaysian government securities and corporate bonds with strong credit ratings receive payments in ringgit. They weigh those payments against the returns available in the United States and the currency changes they expect.
Markets respond to the expected direction of rates, not just to a single policy meeting. As the Federal Reserve moved toward easier policy and Bank Negara Malaysia (BNM) kept its policy rate steady, expected yields on Malaysian bonds became more attractive relative to US alternatives. Demand strengthened for Malaysian Government Securities, Government Investment Issues and selected corporate bonds.
The dollar also benefits when investors become worried. As the world's dominant reserve currency and a currency widely sought during market stress, it attracts money from investors seeking safety and assets they can readily buy or sell. When anxiety eases, some of that money returns to markets offering higher yields, including emerging economies in Asia.
The third and fourth quarters of 2025 brought a broad retreat in dollar strength as global growth stabilized and investors partly incorporated tariff uncertainty into market prices. That change reinforced the effect of interest rate differences. Investors also adjusted positions built during earlier years of ringgit weakness. Several valuation measures had suggested the currency was undervalued after repeated selling between 2021 and 2023, allowing the rebound to gather momentum as portfolios were rebalanced.
Bond inflows lead, while stocks tell a different story
November's estimated US$1.3 billion inflow was the clearest recent channel connecting foreign investment with ringgit strength. Cumulative foreign purchases of Malaysian bonds during 2025 run into billions of dollars, supported by attractive returns after inflation and confidence that the government is reducing its budget deficit.
Foreign investors who leave their currency exposure unhedged can benefit twice: they receive interest on their bonds, and a stronger ringgit raises the value of those payments in their home currency. Hedging means arranging protection against adverse exchange rate changes. Without it, investors receive the benefit of appreciation but also carry the risk of depreciation.
Liquidity, the ease of buying and selling assets without causing large price changes, has tended to improve in the ringgit bond market when the currency strengthens. During earlier periods of pressure, withdrawals widened spreads and discouraged investors from holding bonds with longer repayment periods. Wider spreads mean a bigger gap between buying and selling prices, making transactions more costly.
The current environment has been more supportive. Inflation is muted, the currency is firm and new bond issuance is being absorbed without signs of stress. Market participants have also pointed to administrative steps that slowed outward remittances, helping moderate money leaving the country and supporting liquidity within Malaysia.
Local equities present a different picture. Some foreign investors have continued reducing their holdings of Malaysian shares even as bond purchases increased. The rally has therefore been concentrated in interest rate expectations and fixed income investment, with less consistent support across other assets. Officials have called for stronger economic foundations so currency performance can align more closely with corporate earnings and productivity.
Malaysia's performance also fits a wider regional pattern. Several Southeast Asian economies recorded stronger growth in the second quarter as businesses brought activity forward before tariff changes. Malaysia maintained steady growth supported by private consumption, while industrial production and exports exceeded expectations. Regional currencies generally strengthened against the dollar as central banks either held rates steady or reduced them to support growth.
Fiscal policy gives investors a domestic reason for confidence
Malaysia's government has set a course toward fiscal consolidation, meaning a gradual reduction in the gap between public spending and revenue. Subsidies have been adjusted to direct support more effectively toward households with lower incomes, while spending has continued in priority areas including healthcare, education and infrastructure.
Stable monetary policy and active communication with markets have accompanied those changes. Together, tighter budgeting and continuity in economic policy have helped build investor confidence that Malaysia can maintain growth while managing its public finances.
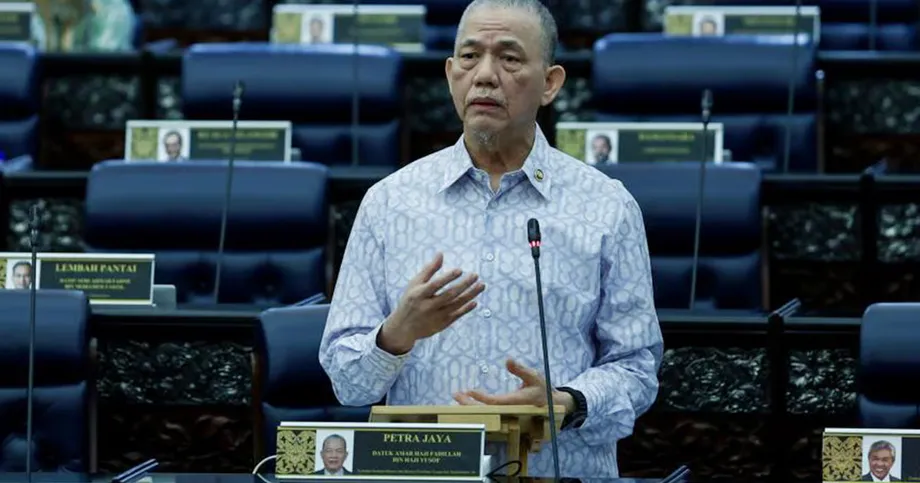
Prime Minister Datuk Seri Anwar Ibrahim told Parliament that fiscal discipline and effective economic management underpinned the ringgit's performance. He described the currency as Asia's strongest performer so far this year:
Fiscal discipline and effective management of Malaysia's economy have made the ringgit the best performing currency in Asia so far this year.
Anwar said subsidy reforms were intended to ensure assistance reaches people who need it while keeping government finances on a sustainable course. He also highlighted a surplus in the services account for the first time in 14 years. The services account records international transactions involving services rather than physical goods.
BNM's role is to support price stability and sustainable growth, backed by adequate foreign reserves. The central bank says market demand and supply determine the ringgit's value, while intervention can help manage abrupt movements. It described its exchange rate approach in these terms:
The ringgit exchange rate is determined by market forces of demand and supply. Bank Negara Malaysia does not set the exchange rate but may intervene to ensure orderly market conditions and prevent excessive volatility.
Anwar also called for stronger enforcement to ensure cheaper imports lead to fairer retail prices. Currency gains take time to reach consumers because companies adjust prices slowly and some sectors have greater power to maintain their prices.
Exports are recovering, but investment flows move faster
Malaysia's electronics and electrical products industries are receiving firmer orders as the global technology cycle improves. Palm oil and other commodities continue to support the trade surplus, while digital infrastructure and renewable energy projects are attracting investment and creating opportunities for exports with greater value over time.
Analysts expect further improvement as supply chains stabilize and regional demand strengthens. Malaysia's close connections to Asian production networks mean changes in trade relations can quickly affect both business expectations and currency sentiment.
The current account surplus has narrowed at times during 2025, even as the ringgit has strengthened. The current account brings together trade in goods and services with income and transfer payments across borders. Its movement helps explain why the latest rally looks more closely tied to bond investment and changing expectations than to a sudden increase in net exports.
Currency markets often move before trade figures because investors act on what they expect to happen. A thaw in tensions between major powers can lift confidence quickly, while new tariffs or sanctions can reverse that mood. Officials and investors therefore watch the composition of exports as well as their total value. A larger share of goods and services with greater value added can make growth and foreign earnings more resilient.
Imported energy and food components priced in dollars can become cheaper when the ringgit strengthens. The savings reach consumers unevenly and with delays. Enforcement and greater price transparency can help ensure that lower import costs are shared where retail prices have been slow to adjust.
Investment and productivity determine how durable the gains become
Foreign direct investment can provide a more lasting source of currency support than portfolio purchases. It involves commitments to factories, logistics networks and services platforms rather than assets investors can readily sell. Malaysia's electronics ecosystem, expanding data center investment and green energy projects can generate continuing foreign exchange earnings.
Investors who see Malaysia as a dependable part of regional supply chains can bring in capital while helping reduce reliance on financing that may leave quickly. Digital and physical infrastructure investment, targeted fiscal support and steady monetary policy form part of the country's policy mix in 2025.
Domestic investment matters alongside foreign commitments. A stronger pipeline of private projects, efficient public procurement and better workforce skills can improve productivity, the amount of output produced from available labor and equipment. Higher productivity can raise real incomes and support the currency over time.
Officials and economists consequently look beyond gross domestic product growth to capital deepening and technology adoption. Capital deepening means giving workers more or better equipment and infrastructure, helping them produce more. Technology adoption can improve how businesses use those resources.
Contained inflation adds another layer of support. BNM's policy rate has stayed steady in 2025, while subdued price increases have kept returns after inflation attractive. Stable policy can reduce currency volatility and encourage Malaysian and foreign investors to retain ringgit assets through changing economic conditions.
What could interrupt the rally?
A faster rise in US inflation or a pause in expected Federal Reserve cuts could strengthen the dollar again. Renewed trade friction, a sharp decline in willingness to take investment risks or a surge in energy prices would also put pressure on emerging market currencies, including the ringgit.
Malaysia faces domestic risks as well. A slower export recovery, weaker investment flows into equities or delays in policy changes could reduce enthusiasm. After a strong advance, technical indicators used to assess price patterns can point toward consolidation, a period when a currency trades within a range or gives back some gains.
Some market strategists expect a near term pullback toward the mid 4.1s to 4.2 ringgit per dollar before a possible return to appreciation in 2026. That outlook depends on economic data and policy signals. A move above 4.10 means more ringgit are needed to buy a dollar, so it would represent weakness compared with a move below that level.
UiTM Puncak Alam Associate Professor Dr Norliza Che Yahya linked improved confidence to Malaysia's economic stability and changes in US monetary policy. She said:
Malaysia's economic stability, alongside recent US interest rate cuts, had boosted investor confidence and fuelled foreign capital inflows.
Norliza cautioned that changes in global sentiment could alter the currency's direction. She also identified controlled inflation, a stable policy rate and firm growth as a solid domestic base. Those strengths can support confidence, although the ringgit remains sensitive to international financial conditions.
Households, exporters and investors feel different effects
A stronger ringgit can reduce the cost of imported food inputs, medicines and machinery. Overseas travel becomes more affordable, and students abroad need fewer ringgit to meet expenses in dollars or euros. The government's push for better transmission of import savings reflects concern that some sectors have kept prices unchanged despite lower costs.
Exporters may face narrower profit margins, especially when sales are priced in dollars and contracts cannot be adjusted quickly. Many use hedging to smooth changes in currency earnings. Importers and local companies using foreign inputs may benefit from lower costs, freeing cash for investment.
Companies with debt in foreign currencies generally need fewer ringgit to meet those payments when the currency strengthens. For bond investors, appreciation has increased returns for those carrying currency risk, while local savers have benefited from stable returns after inflation. Equity investors have remained more cautious, keeping company earnings and valuations central to their decisions.
Households and businesses can manage exposure through forward contracts, staggered foreign currency purchases and a diversified mix of savings instruments. A forward contract fixes an exchange rate for a future transaction. Spreading purchases across different dates can reduce reliance on the rate available on any single day.
Policy decisions, inflation figures and trade developments remain useful signals for those planning payments or investments. The practical effect of a stronger ringgit depends on whether someone earns, spends, borrows or saves in a foreign currency.
The milestones behind the move
The rally developed across several periods rather than from one announcement. Earlier currency weakness, changes in regional activity and the latest bond inflows each help explain how the ringgit reached its position by December 8.
- 2021 to 2023: Repeated selling left the ringgit undervalued by several measures, providing scope for a rebound as investors adjusted their positions.
- May 2025: The later November bond inflow would be the largest monthly inflow since this month.
- Second quarter of 2025: Several Southeast Asian economies benefited as businesses brought activity forward before tariff changes. Malaysia's growth remained supported by private consumption.
- Third and fourth quarters of 2025: Dollar strength retreated broadly as global growth stabilized and tariff uncertainty was partly reflected in prices.
- November 2025: Foreign investors bought an estimated US$1.3 billion of Malaysian government and corporate bonds.
- December 8, 2025: The ringgit was up more than 8 percent for the year and near its strongest level against the dollar in four years.
The next phase depends on whether supportive global conditions continue alongside Malaysia's domestic progress. No specific dates for forthcoming policy decisions or economic releases were given.
What the outlook suggests for 2026
Profit taking and seasonal factors could slow the rally toward the end of 2025. At the same time, favorable interest rate differences, credible fiscal consolidation and demand for Malaysian bonds provide support. A period of consolidation could be followed by renewed appreciation if global conditions remain calm and domestic figures improve.
Many economists expect BNM to keep its policy rate unchanged into 2026, given contained inflation and stable growth. Fiscal targets in the mid three percent range of GDP continue to support confidence in government finances. Several banks project total returns in the middle of the single digit percentage range for ringgit bond investors in 2026, assuming stable rates and modest currency gains.
GDP growth, inflation, trade and current account balances, oil prices and US interest rate decisions will help shape that outlook. Subsidy changes, tax reform and investment approvals will also influence expectations. Sustained investment of high quality, stronger productivity and continued fiscal and price discipline would support a steadier currency beyond the immediate rally.
Key Points
- The ringgit gained more than 8 percent in 2025 and was near a four year high against the dollar as of December 8.
- November brought an estimated US$1.3 billion in foreign bond purchases, the largest monthly inflow since May.
- Changing US rate expectations and improving global risk appetite supported the rally, while foreign equity flows remained mixed.
- Fiscal consolidation, targeted subsidies, contained inflation and steady monetary policy helped build confidence.
- Anwar highlighted the first services account surplus in 14 years and called for import savings to reach consumers.
- BNM says market forces determine the exchange rate and intervention can help keep trading orderly.
- A stronger ringgit can lower import and foreign debt costs, while putting pressure on some exporters' margins.
- The 2026 outlook depends on global rates, trade conditions, investment and continued domestic policy credibility.