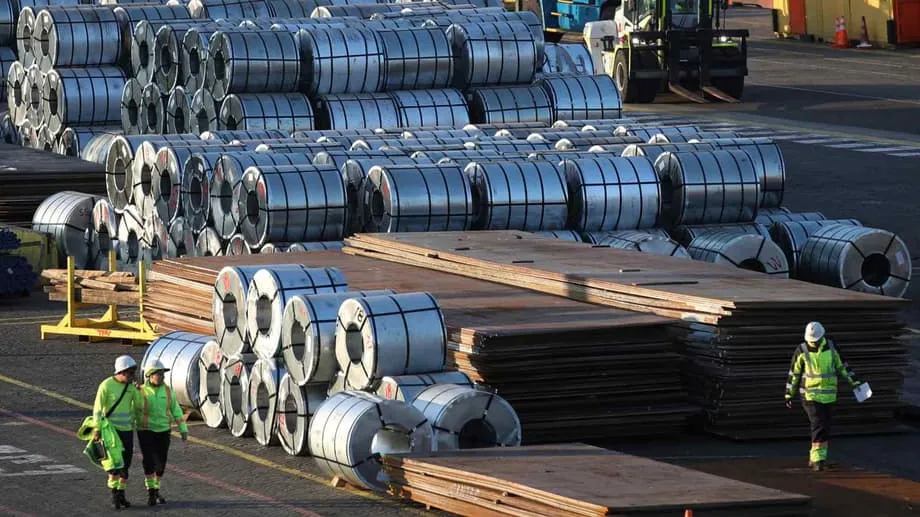
Chinese mills look abroad as the steel surplus grows
China's steelmakers are expanding overseas as falling demand at home, tougher trade rules and rising pressure to cut emissions reshape where they invest. By December 1, 2025, projects stretching from an iron ore plant in Oman to planned steel facilities in Saudi Arabia and Kazakhstan show how producers are searching for cheaper energy, better raw materials and customers beyond a slowing domestic market.
Contents
- Chinese mills look abroad as the steel surplus grows
- Why the home market can no longer absorb as much steel
- Carbon rules change the investment calculation
- Trade barriers encourage a change in products and production
- Oman anchors a larger push into the Gulf
- Southeast Asia, Africa and Kazakhstan offer different advantages
- HBIS tests a market for steel with lower emissions
- A global glut threatens both profits and cleaner projects
- The dates and costs that will shape the next stage
- Key Points
The scale of the supply problem is large. The OECD Steel Committee has warned that global steelmaking capacity could reach about 2.55 billion metric tons by the end of 2025, with excess capacity above 680 million tons. Those figures put the surplus at more than a quarter of total capacity. China exported more than 118 million tons of steel in 2024, and exports grew again in 2025.
Chinese mills have faced a faster decline in domestic demand than in production. Weaker property construction, tighter local government budgets for infrastructure and a slower industrial cycle have left factories with spare capacity and thinner margins. Cutting prices has helped keep production lines running, but has also reduced the money earned on each sale.
Overseas investment offers several possible advantages at once. A plant closer to customers can reduce transport costs and serve local demand. A location with affordable gas, suitable iron ore or cleaner electricity can support different production methods. Producing in another country can also change the trade barriers a company faces, although European carbon charges will depend on the emissions generated by the steel itself.
Chinese producers tested overseas expansion during the past decade. Their latest plans go further, combining access to markets with technology intended to make steel using less fossil carbon. The Middle East and Southeast Asia are the main destinations, alongside selected investments in Africa and eastern Europe.
Why the home market can no longer absorb as much steel
Construction remains the largest source of steel consumption in China, followed by machinery, automobiles and appliances. The prolonged property downturn has reduced orders for reinforcing bars, beams and flat steel used in building frames and exterior cladding. New housing starts remain far below levels seen in the late 2010s, while developers have struggled to finish existing projects.
Local governments have limited room to fill the gap. Strained finances have constrained large infrastructure projects beyond targeted priorities such as energy and transport. Infrastructure investment has therefore failed to compensate for the weakness in property construction.
Factories, machinery manufacturers and automotive suppliers have absorbed some steel, but their demand has not been enough to balance the business of large mills oriented toward building materials. Producers have shifted more exports toward sheets used in cars and appliances, which can command higher prices than basic construction products. Competition remains intense, however, and price gaps with rival suppliers have narrowed.
China's net steel exports rose back above 100 million tons in 2024. Net exports mean the amount sold abroad after subtracting imports. The increase reflected the shortage of buyers at home more than a lasting rise in steel consumption around the world.
Mill managers face a difficult calculation. Keeping furnaces busy spreads operating costs across more output, but selling that output at lower prices squeezes profits. Overseas plants and new product lines offer ways to reduce dependence on the domestic construction market, even as they expose companies to another set of commercial and political risks.
Carbon rules change the investment calculation
China maintains strict controls on new steelmaking capacity at home and has set output ceilings to manage emissions. Its national carbon market expanded to include steel in 2025, requiring mills to measure and report emissions and buy allowances when they exceed benchmarks.
Steel accounts for around 15 percent of China's emissions by several estimates. National carbon dioxide emissions were flat or falling for much of the preceding 18 months, helped by record additions of solar and wind power and lower output in cement and metals. Regulators are increasing pressure on older steelmaking technology as part of that wider change.
Blast furnaces rely heavily on coal to turn ore into iron. Carbon compliance adds to the operating costs of this route and strengthens the business case for electric arc furnaces, which use electricity to melt scrap or other iron inputs. The benefit depends partly on how that electricity is generated.
Direct reduced iron, usually shortened to DRI, offers another route. The process removes oxygen from iron ore without melting it, leaving solid iron that can then be melted in an electric arc furnace. Natural gas or hydrogen can perform the iron reduction step. Cleaner electricity and hydrogen can reduce the emissions associated with producing the finished steel.
China's electric arc share has not increased as quickly as planners hoped. Scrap availability and power prices remain important constraints. Overseas projects give companies opportunities to use different combinations of ore, energy and technology while China's carbon market is expected to deepen its coverage and tighten emissions benchmarks.
Trade barriers encourage a change in products and production
Chinese steel has faced trade restrictions for years. The United States retains tariff measures on many steel products. The European Union and several Asian economies apply anti dumping duties, aimed at imports sold at unfairly low prices, and countervailing duties, which address subsidies. Several economies have also widened safeguard measures designed to protect domestic industries.
Restrictions increasingly reach beyond basic steel to structures and other manufactured components. Some Chinese suppliers have responded by exporting different products. Shipments of semi finished steel, including billets that require further processing, grew rapidly in early 2025 because these products often face fewer trade remedies than coated or cold rolled flat steel.
Other producers sell machinery and equipment containing steel. These indirect steel exports connect mills to demand for finished industrial goods rather than relying entirely on sales of steel itself. New purchasing and export arrangements through port hubs have also become part of the trading picture.
Building or buying a factory abroad changes the location of production. A Serbian steel plant revived by Chinese owners during the previous decade showed how overseas investment can gain local political support and easier access to nearby markets. Companies have also upgraded existing mills and built plants where energy costs suit newer production methods.
The European Union's Carbon Border Adjustment Mechanism, or CBAM, adds another consideration. Its phase requiring payment begins in 2026 and will expand through the decade. Charges will be based on the emissions embedded in imported steel, regardless of who owns the plant. Companies seeking European customers therefore have a reason to consider both the location of production and the way the steel is made.
Oman anchors a larger push into the Gulf
Jinnan Iron and Steel Group is investing with Vale in an iron ore concentration plant at Sohar in Oman. The plan involves more than $600 million in total commitments. Jinnan will build, own and operate the facility, while Vale will upgrade connections to its existing site.
The plant is expected to produce about 12.6 million tons of high grade concentrate a year, with operations targeted to begin by mid 2027. Concentration increases the iron content of the material. The resulting concentrate can be processed into pellets and hot briquetted iron, important inputs for DRI and electric arc steelmaking.
Hot briquetted iron is reduced iron formed into compact pieces for transport and later use. High quality ore matters because the DRI route needs suitable raw material. Access to that material, alongside relatively affordable natural gas, helps explain the attraction of the Gulf for companies seeking to reduce emissions during ironmaking.
Vale is also developing large iron briquette hubs in Oman, Saudi Arabia and the United Arab Emirates. These facilities could help establish a regional supply network for iron with lower emissions, serving steel mills locally and exporting to sheet producers elsewhere.
China Baowu has developed hydrogen assisted DRI technology at home and is backing a project combining DRI with electric arc steelmaking in Saudi Arabia. The proposed production route can use local natural gas initially and more hydrogen later as supplies increase.
The Middle East also offers growing industrial demand and increasing investment in ore processing. For Chinese companies, the attraction is a combination of energy prices, raw material quality and customers. Developers are positioning ironmaking where these inputs are favorable, then supplying regional steel mills or shipping semi finished iron to plants nearer the final buyers.
Southeast Asia, Africa and Kazakhstan offer different advantages
Southeast Asia attracts Chinese steel investment through proximity to buyers, lower logistics costs and government support for industrial parks. Chinese groups have spent years building capacity in the region to serve local growth and reduce the effect of tariffs in destination markets.
Dexin Steel in Indonesia has become a major regional supplier. Chinese steel shipments to Malaysia and Myanmar have grown, while Vietnam's share has declined as duties increased. Several countries have encouraged domestic production to replace imports, creating opportunities for joint ventures and projects based in industrial parks.
Africa has offered more selective opportunities, often involving existing plants or access to particular markets. Chinese companies used early projects to gain experience with electric arc furnaces and improve their products, aiming to serve buyers in North Africa and around the Mediterranean.
Plants in Algeria and the western Balkans supply nearby demand for construction steel and flat products. Modernization is intended to help their owners qualify for more demanding uses, including automotive sheet, appliances and energy projects.
Shougang gained experience building electric arc furnaces in Algeria and is now advancing a DRI and electric arc plant in Kazakhstan. Access to high grade ore is a central attraction there. The project follows the same broad logic as the Gulf investments: match ironmaking technology with a location offering suitable inputs.
The overseas portfolio is therefore varied. Southeast Asian plants place production closer to expanding markets. Gulf projects focus on gas and ore processing. Investments in Africa and eastern Europe combine existing industrial assets with access to regional buyers. Several newer plans seek to move away from coal based blast furnaces toward gas, electricity and eventually hydrogen.
HBIS tests a market for steel with lower emissions
HBIS Group, one of China's largest steelmakers, has built a hydrogen metallurgy chain in Hebei. It connects a shaft furnace producing direct reduced iron with an electric arc furnace and a continuous casting line for automotive sheet. Continuous casting turns molten steel into forms such as slabs or billets for further processing.
HBIS chairman Yu Yong has presented hydrogen as a way to reduce dependence on fossil carbon in ironmaking. His position was described in these words:
Yu Yong, the chairman of HBIS, said hydrogen energy is the ultimate energy source of the 21st century and that using hydrogen instead of carbon in steel production can remove the need for fossil fuels.
Chinese mills have begun selling steel with lower emissions to European customers, including automotive and machinery businesses. A producer based in Hebei reported shipping steel processed using hydrogen to an Italian buyer in July 2025. The volume remains small compared with China's large fleet of plants using coal.
HBIS has cooperation agreements with international carmakers to test and source sheet with lower emissions. Automakers and appliance brands are also beginning to sign supply agreements for certified green steel. China's government has encouraged greener overseas investment and alignment of corporate practices with global climate standards.
The commercial outcome depends on production costs and the extra price customers are willing to pay. Cleaner DRI material could become more competitive if CBAM adds costs to imports with higher emissions, provided transport arrangements and certification are in place.
Natural gas and hydrogen also bring different emissions and cost profiles. The DRI and electric arc route can sharply reduce emissions compared with a blast furnace when its energy inputs are clean and affordable. Hydrogen at industrial scale remains limited and expensive, while electricity grids in host countries are not always clean. Flexible plants can begin with natural gas and gradually use more hydrogen.
A global glut threatens both profits and cleaner projects
The OECD warns that growing capacity, supported by subsidies and other practices outside normal market competition in several regions, is depressing steel prices and reducing returns. Officials have noted that one fifth of planned steel projects with lower emissions through 2027 is on hold because margins have shrunk.
Overseas plants may reduce a company's reliance on China's domestic market, but they also contribute to world capacity. If new supply arrives faster than customers can absorb it, weaker prices could delay the cleaner projects that companies and governments are trying to encourage.
Trade policy remains another risk. The United States can tighten its steel measures, while some ASEAN members are raising barriers on particular steel categories to protect new domestic mills. Semi finished products and fabricated steel structures remain areas where restrictions can shift.
Host governments can also change energy subsidies or tax rules, altering the economics of a project after investment decisions have been made. Gas price spikes and water constraints could complicate DRI and hydrogen plans in the Middle East. Limited scrap supply in many destinations could increase the cost of operating electric arc furnaces.
Exporters face financing and working capital pressures as well. Purchasing and export arrangements through port hubs can create cash flow problems and exposure to trading partners if steel prices move sharply. Emissions reporting and product certification require new systems and skills at mills that have historically competed mainly through scale and low costs.
China Oriental Group is pursuing another response: specialty materials. It has launched joint ventures with ArcelorMittal to produce soft magnetic steel used in electric vehicles and power equipment. Local governments have supported the projects with land and energy connections. The aim is to earn steadier margins from products and customers less exposed to swings in construction steel prices.
The dates and costs that will shape the next stage
China's overseas expansion will be tested by the start of European carbon payments, the delivery of new plants and the price of essential inputs. The main milestones described by December 1, 2025, are:
- 2024: China's steel exports exceeded 118 million tons, and net exports rose above 100 million tons.
- Early 2025: Shipments of semi finished steel grew rapidly as producers adjusted to trade barriers.
- July 2025: A producer in Hebei reported sending steel processed using hydrogen to an Italian buyer.
- 2025: China's national carbon market expanded to steel, while exports grew again.
- 2026: The EU's CBAM enters its payment phase.
- Mid 2027: Jinnan and Vale target the start of the Sohar concentration plant.
The Saudi Arabian and Kazakh projects will test the practicality of starting with gas and increasing hydrogen use as supplies grow. No operating dates were given for those projects. Vale's Gulf briquette hubs could support a wider regional network supplying iron with lower emissions to steelmakers abroad.
Ore prices will matter alongside energy costs. The premium for pellets suitable for direct reduction and the price index for high grade iron ore fines will help determine whether the new routes can compete. Inside China, scrap availability, electricity prices and the pace of industrial electrification will influence the share of steel made in electric arc furnaces.
Overseas mills also need reliable ore supplies, energy with lower emissions and lasting purchase commitments from automakers and builders. The combination of those inputs and buyers will determine whether foreign projects become a durable complement to a slower home market.
Key Points
- Falling construction demand and thin margins are pushing Chinese steelmakers to invest abroad.
- The OECD projects global steelmaking capacity of about 2.55 billion metric tons by the end of 2025, with excess capacity above 680 million tons.
- China exported more than 118 million tons of steel in 2024, with exports growing again in 2025.
- China's carbon market expanded to steel in 2025, and EU carbon border payments begin in 2026.
- Jinnan and Vale's Oman project involves more than $600 million and targets annual output of 12.6 million tons from mid 2027.
- Chinese groups are pursuing projects using direct reduced iron and electric arc furnaces in Saudi Arabia and Kazakhstan.
- Southeast Asia, Africa and eastern Europe offer access to customers and existing industrial assets.
- HBIS is developing hydrogen metallurgy and working with carmakers on steel with lower emissions.
- Excess capacity, changing trade rules, energy costs and limited scrap supplies threaten investment returns.